Many banks are experimenting with artificial intelligence, APIs and digital assets. What distinguishes DBS is how it is bringing these technologies into the everyday operation of banking: from processing payments and managing client relationships to moving liquidity across traditional and blockchain-based networks.
Its innovation strategy is built around a simple principle: technology should not merely improve individual banking products but change how financial services are delivered. That thinking is evident in the bank’s investment in AI-enabled operations, embedded connectivity and programmable money.
For a bank whose core strength lies in Asia, DBS has developed an innovation model with global relevance. Its progress is supported by measurable improvements in operational efficiency, growing adoption of digital solutions and practical applications of technologies that many institutions are still testing.
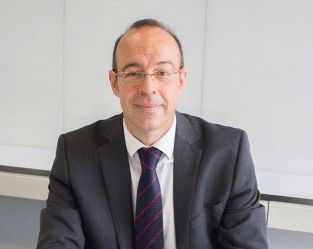
“At DBS, our approach to innovation is grounded in understanding our clients’ needs and ambitions,” says Soon Chong Lim, group head of global transaction services. “From AI to instant payments and digital assets, we combine technology with deep market insights and product expertise to deliver practical real-world value.”
Making AI part of the operating model
DBS’s approach to AI goes well beyond conversational assistants. It is applying generative AI to some of the most labour-intensive processes in transaction banking, where manual intervention remains a significant source of cost, delay and operational risk. “Businesses need greater resilience, visibility, control and flexibility over their cash positions to navigate an increasingly complex environment,” explains Lim.
Payment processing provides a strong example. DBS has deployed generative AI to extract and interpret information from payment forms, including scanned and handwritten documents. The solution operates across five markets – Singapore, Hong Kong, India, Taiwan and Vietnam – handling approximately 65,000 forms monthly.
The results are significant. Manual processing effort has fallen by more than 70%, while the bank reports extraction accuracy exceeding 82%, with no payment processing errors following production deployment. By automating data capture while retaining human validation, DBS has reduced the time employees spend on repetitive tasks without relinquishing operational control.

From AI to instant payments and digital assets, we combine technology with deep market insights and product expertise to deliver practical real-world value
Soon Chong Lim
A similar approach is being applied to payment investigations. Instead of requiring operations teams to read lengthy Swift messages and manually categorise enquiries, generative AI produces summaries and identifies the nature of each investigation. Testing in Singapore has demonstrated accuracy exceeding 90%, with more than 10,000 messages a month potentially benefiting from the technology.
DBS is also applying generative AI to sanctions screening, where high transaction volumes can produce large numbers of false alerts. A parallel-run implementation has achieved 78% accuracy, with further development focused on improving screening efficiency while maintaining human oversight.
Trade finance presents another opportunity. DBS is integrating generative and agentic AI into document checking, onboarding and transaction processing. DBS sees up to 40% improvement in transaction turnaround time from AI-supported trade processing, with implementation expanding across additional products.
The significance extends beyond cost reduction. By automating repetitive work, DBS is creating additional capacity for employees to focus on exceptions, risk management and more valuable client interactions.
From digital service to intelligent engagement
The next stage is bringing the same intelligence directly to clients.
DBS Joy, the bank’s corporate digital assistant, is already deployed for client servicing, providing an alternative to conventional digital banking navigation. The bank’s ambition is to move towards agentic AI, where digital interfaces can understand requests, authenticate actions and eventually support more complex transactions.
That distinction is important. Many banks have introduced chatbots capable of answering questions. DBS is working towards a model in which AI becomes an interface through which clients interact with banking services, rather than simply another channel for obtaining information.
Internally, the bank is also developing a generative AI client-profile agent for relationship managers in Hong Kong. The system brings together transactional information, client holdings, KYC data and research to support more relevant engagement and identify cross-selling opportunities.
Embedding banking into client workflows
AI is only one dimension of DBS’s innovation strategy. Another is its investment in API infrastructure that allows financial services to become part of clients’ existing systems. Through DBS RAPID, corporates can connect their enterprise resource planning platforms directly to the bank for payments, collections, account information and reconciliation.
For example, DBS introduced an API-based request-for-payment service through Indonesia’s BI-FAST network, allowing businesses to initiate collection requests that customers can approve digitally, with immediate settlement. For a telecommunications company operating across Asian markets, DBS RAPID connects the company’s ERP system with banking services in China, Hong Kong and Singapore, removing manual payment instructions and enabling automated reconciliation.
AI adoption, digital assets and new settlement mechanisms offer businesses opportunities to optimise liquidity and to scale effectively
Soon Chong Lim
The same principle underpins DBS GlobeSend and its enterprise payments and FX hub. Supporting payments in 125 currencies across more than 180 markets, the infrastructure brings together foreign exchange, compliance, routing and settlement into a common orchestration layer.
Rather than depending on a single payment network, DBS is building the flexibility to connect traditional clearing systems, instant-payment rails and emerging blockchain infrastructure.
Turning tokenisation into practical banking
One the strongest examples of DBS’s longer-term innovation strategy is its work in digital assets.
Having started its distributed ledger technology journey in 2020, DBS has progressively moved from experimentation into commercial applications of tokenised money, with approximately SGD10 billion ($7.83 billion) processed through its distributed ledger infrastructure. Through DBS Token Services, the bank is applying tokenised deposits to conditional payments, liquidity management and programmable rewards.
Programmable Rewards illustrates how blockchain can become useful without requiring customers to understand the underlying technology. Integrated into DBS PayLah! and the NETS merchant acceptance network, it allows issuers to create digital vouchers with predefined spending conditions.
DBS has also worked with Enterprise Singapore on conditional grant payments and participated in the Hong Kong Monetary Authority’s e-HKD pilot, where programmable digital vouchers demonstrated how settlement processes could be shortened from approximately one month to one day.
Yet the challenge for digital money is not simply creating tokens, it is enabling them to move between institutions and networks.
DBS is addressing this through its work with Kinexys by JPMorgan on a framework that would allow tokenised deposits to be transferred and redeemed across different blockchain ecosystems. The initiative remains in development as part of MAS’ Project Bloom, but it addresses one of the central barriers to wider institutional adoption: interoperability.
“AI adoption, digital assets and new settlement mechanisms offer businesses opportunities to optimise liquidity and to scale effectively,” says Lim. “The future will be defined by new forms of money and technology, and also shaped by trusted anchors who can orchestrate value movement across multiple networks.”
This is where DBS’s innovation strategy becomes particularly relevant globally. Its investments in AI, APIs and tokenisation are not separate ambitions. Together, they point towards an operating model in which banking becomes more automated, embedded and available around the clock.