|
|
For Bank of America, the third quarter of 2018 marked the 15th straight quarter since the start of 2015 of growing revenues (up 4% in the quarter) faster than its costs (down 2%). These continuous improvements in operating leverage, coupled with a strong US economy in 2018 and a decade-low cost of risk, led to a new high-water mark.
The bank managed to grow loans and revenues ahead of robust US GDP growth. And its $9 billion of pre-tax income and $7.2 billion of net income in the third quarter of 2018 marked record highs.
Investors took a long time to get behind chief executive Brian Moynihan’s mantra of responsible growth, seeming to dismiss it at first as lack of dynamism. But the bank has now hit a 1.23% return on assets and a 15.5% return on tangible common equity, up from 11% in the third quarter of 2017.
It has made itself much simpler and more efficient. Its cost-to-income ratio was down to 57% by the third quarter of 2018, a marked improvement on the 61% achieved a year earlier.
Yet, while becoming a low-cost provider of simple banking products, BofA has been investing roughly $3 billion a year in new technology initiatives.
It launched the US banking industry’s first, and so far only, artificial intelligence virtual assistant, called Erica (yes, it took us a moment too), in the second quarter of 2018.
Erica had attracted 3.4 million users by the time the bank reported the third quarter in mid October. It launched the Zelle peer-to-peer payments app in the middle of 2017, which has attracted 4.3 million users. It was early to offer digital mortgages, for example, and auto loans on its mobile app.
Time to beat the corporate chest and declare victory? Not at Bank of America.
“The economy and the markets eventually will turn,” Paul Donofrio, chief financial officer, tells Euromoney. “One of the challenges for banks in 2018 has been to avoid pursuing returns in the current environment that will prove to be detrimental to their customers, and thus to the banks themselves, when the slowdown occurs.
“Our focus for years has been growing responsibly through the cycle, which is demonstrated by 15 consecutive quarters of positive operating leverage and our returns on asset and on equity,” he adds. “The precise timing of a recession cannot be determined especially well in advance. What you can control is the manner in which you run the company during the good times.”
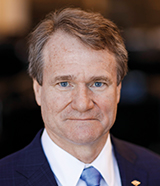 |
| Brian Moynihan |
The bank has gathered an unwelcome reputation for being risk averse. Its executives say that by not chasing earnings, it can retain the capacity to lend in once-hot sectors that may suddenly weaken and see other over-extended banks withdraw. “In commercial real estate, for example, we recently have increased our limits,” says Donofrio. “We see the right rewards for the risk. But our exposure as a percentage of our equity is considerably less than is the case at some other lenders.”
Yet there have been signs of unease at the bank. Its board went to great lengths, including hiring an outside legal team, to investigate the $292 million loss Bank of America suffered in 2017 on a margin loan to South African billionaire Christo Wiese secured by shares in Steinhoff, which collapsed in value after the disclosure of accounting irregularities at the retailer.
In the aftermath, some of the momentum that had been building in its global corporate and investment bank seemed to be lost; in September news broke that Christian Meissner, the former Goldman Sachs banker who headed that division, would leave at the end of the year.
“We have ranked between second and fourth in investment banking fees for more than five years,” says Donofrio. “We would like to be number one, of course, and we should be in the top three. We are not chasing the market but instead staying focused on responsible growth to ensure we can deliver for clients through the cycle.
“That said, this is not a risk appetite issue and I know we can do better. We have one of the best platforms on the planet; very few can do for clients what we can do for them in every major market around the world. This requires reinvigorating our focus and re-energizing our teams. There is no reason we can’t execute on the opportunity that is in front of us.”
The bank is looking for opportunities.
“There’s been an increase in provision of leveraged loans by non-bank funds that themselves have only a small amount of equity and a lot of debt,” says Donofrio. “Some of that lending has been indiscriminate. If things go wrong, that may impact good deals as well as weaker ones. And if sound borrowers who got a low price for high leverage have to refinance at higher rates in a less liquid market, we may pick up share.”


