Awards for Excellence 2018
|
|
This year’s award for CEE’s best bank for small and medium-sized enterprises goes to regional sector specialist ProCredit Holding in recognition of its unique franchise, strong development orientation and ability to transform its business model to meet the changing needs of its countries of operation.
Founded in 2003, the German group originally focused on providing finance to smaller and micro enterprises across southeastern and eastern Europe. In 2013, however, shareholders and management agreed to move towards targeting the core SME segment.
Borislav Kostadinov, a member of ProCredit Holding’s management board, explains the change of strategy.
“Access to finance for microentrepreneurs was no longer a problem in our markets, so from a development point of view we were no longer adding value,” he says. “We felt it made more sense to focus on the Mittelstand, that is SMEs with formalized structures steered by forward-looking entrepreneurs, who are responsible to their operating environment and society, and who take environmental and social issues seriously.”
The decision was also commercially driven.
“We want to provide predictable and sustainable profits to our shareholders,” says Kostadinov. “Staying in the micro sector when it is still populated by informal entities we felt was not wise from a risk perspective.”
ProCredit’s target minimum loan size was therefore raised to €30,000 and the group began exiting relationships with smaller clients. The process, which was completed last year, also involved shrinking the group’s branch network from 650 to 180, with a similar reduction in staff numbers.
At the same time, the group stepped up its investment in multichannel banking.
“The only way to increase the loan book on declining infrastructure is to take digitalization and electronic channels very seriously,” says Kostadinov.
The transition was undertaken in stages, with SME clients migrated first from cash-based operations to machine-only transactions and then to digital channels. Technology development is provided in-house by Quipu, ProCredit’s consultancy and software development subsidiary.
The move to a new business model inevitably impacted portfolio growth as smaller loans were run down. Nevertheless, ProCredit managed to grow its overall loan book by 8% last year, on the back of an 18% increase in larger exposures. The group is now targeting annual loan expansion of 12% to 15%.
ProCredit’s offering to SMEs is not limited to loans, however. The group’s network banks also offer current accounts and a full range of transaction services.
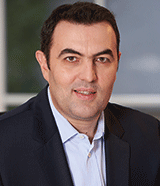 |
| Borislav Kostadinov |
“We aspire to be the only bank for these SMEs,” says Kostadinov. “For them, this ensures transparency and predictability in their operations, and for us, it strengthens the relationship and builds fee income.”
The group also provides retail banking services on a selective basis to entrepreneurs, their families and the wider middle and upper-middle class in its countries of operation. This includes current and savings accounts, as well as lending in the form of overdrafts, investment loans and mortgages. Last year saw the introduction of a new digital offering for ProCredit’s retail customers, while work is currently underway on the roll out of a new mobile banking app.
The majority of ProCredit’s funding comes from customer deposits, with the remainder provided by long-term loans from international development banks and German institutional investors. The group has been particularly proactive in channelling green financing to CEE. Green loans currently account for 13.3% of outstanding lending.
ProCredit’s main shareholder is Zeitinger Invest, a Frankfurt-based family group focused on the development of sustainable banking in emerging markets. Other leading shareholders include KfW, IFC and the Dutch lotteries foundation, Doen Participates.
The group undertook its first capital raise via the Frankfurt Stock Exchange in February. The listing raised €61 million from 18 investors, including the EBRD and IFC.
Apart from its tight focus on the SME segment, other factors that set ProCredit apart from other banking groups in CEE are its consistent offering across all markets, its policy of employing only local managers – of whom more than 50% are women – and its emphasis on long-term client relationships.
“While others advertise products, we advertise relationships,” says Kostadinov. “We don’t pay bonuses to our staff in order to avoid putting our employees under pressure.”
A combination of local expertise and stringent risk management have also ensured ProCredit’s asset quality remains superior to most of its competitors. At the end of December, impaired loans accounted for just 2.9% of the total and all were fully provisioned.
ProCredit’s largest exposures are in Bulgaria, Serbia, Kosovo and Ukraine. One-third of lending growth in Bulgaria last year came from Greece, where the bank opened a branch in Thessaloniki in late 2015. The group’s other countries of operation are Albania, Bosnia, Georgia, the former Yugoslav Republic of Macedonia, Moldova and Romania.



