|
|
|
View the Euromoney 25 |
Given all the noise around the poor performance of its fixed income, currencies and commodities division in the first half of the year – and, in particular, the hit on commodity inventory in the second quarter – it almost comes as a surprise to see how well Goldman Sachs performed overall in 2017, heading into the final quarter of the year.
In the first nine months of 2017, it grew revenues by $1.8 billion to $24.2 billion, an increase of 8% over the first three quarters of 2016.
Goldman has been cutting operating expenses, allowing senior people to leave from the partner and managing director ranks, hiring more associates and analysts, while growing back-office headcount in cities like Bengaluru in India, Warsaw and Salt Lake City.
CEO Lloyd Blankfein now regularly visits these so-called strategic cities, recently spending time happy times in Paris and Frankfurt.
Expenses grew at only half the rate of revenues in the first nine months. With the share count down following buybacks, the firm achieved a 160-basis point increase in return on equity, up to 10.3% from 8.7% a year earlier.
Strong performance in investment banking and investment management helped offset weaker FICC performance.
The big talking point in the second half of last year was the firm’s focus on fixing its FICC division and on efforts to wring $5 billion of additional annual revenues over the next three years from what it calls white space, much of that from entirely new customers.
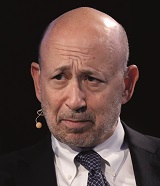 |
| Lloyd Blankfein |
In FICC, Goldman was traditionally very strong in complex and derivatives-led trades for active managers such as hedge funds and insurance companies. In that respect, it was a little like Deutsche Bank. Unlike Deutsche, however, Goldman did not also seek to dominate regular business, rather turning its nose up at thin margins for customers doing fewer large risk-transfer trades.
“Our business in FICC had tipped too far towards highly tailored activity for active clients,” David Solomon, president and chief operating officer of Goldman Sachs, tells Euromoney. “At this time, FICC market intermediation is now much more of a flow business. And while large parts of that business are still characterized by narrow bid-offer spreads and subdued client activity, the firm is determined to strengthen its client footprint by growing share with specific asset managers and banks where we have not been a top-three counterparty. We are also doing more with corporates as part of a firm-wide push for growth.”
Doubts rose last year over whether or not a firm that survived the financial crisis and managed well through the immediate aftermath had adapted sufficiently to the new financial world order.
It is worth remembering, however, what Goldman can do when it sets its mind to it. Witness its rise up the debt capital markets rankings. In 2017, it held on to big M&A financing mandates it might previously have let go to the large banks.
But the new venture to watch closely this year is in consumer lending. Euromoney is relieved that its bankers have stopped calling this platform Marcus by Goldman, which made it sound like a men’s perfume you might pick up at Century 21.
Hopes for Marcus run high. In the plan for $5 billion of additional annual revenues to be achieved in the next three years, increased firm-wide lending and financing is supposed to bring in $2 billion, with Marcus contributing half of that.
Firm executives with little direct experience of the IT engineering behind the platform or of retail customers seeking $5,000 to $30,000 unsecured loans to consolidate their credit card debts are excited.
Perhaps that is partly because this is Goldman turning the old saw about it really being a technology company into reality. It has hard cuts that reject potential borrowers due to weak traditional credit-score metrics on their capacity to repay loans. But then the talk quickly turns to big data, artificial intelligence and dynamic pricing algorithms.
A handful of people at Goldman, including some of its merchant bankers, identified an unaddressed opportunity in the near $1 trillion market in unsecured US consumer loans and figured the firm could build an offering for a smaller subset of prime borrowers seeking flexibility on payment dates on interest bearing loans and grow it quickly towards $13 billion of balances. The firm lays out hopes for a 10% net interest margin, 4% charge-offs through the cycle, 2.5% of running costs that would achieve a 3.5% pre-tax return on assets and a mid- to high-teens return on equity.
It took Goldman 11 months from writing its first line of code for Marcus to making its first loan.
“Within our first year, we have gone from zero balances to over $2 billion, which is faster than any fintech startup from Silicon Valley that has tried to do consumer finance,” Solomon says. “And we’re actually constraining that growth rate because we are being conservative on risk and rather seeking to provide products and services that address prime customers’ pain points.”
So, for example, Marcus promises no hidden fees or opaque terms or inflexible repayment dates.
For now, such commitments to retail customers still seem at odds with the Goldman way.



