|
|
If you want stark evidence of the extent of investor concerns at the fragile state of financial markets, look no further than the share price performance of Morgan Stanley. The company had a terrific year in 2018, the stock did not. From a high of $59 in March, the price had fallen by 27% to $43 in the rout at the start of December. Yet this is one of the best run companies in the business.
At the start of each year, chief executive James Gorman famously lays out some strategic objectives. In January 2018, he set targets to hit a pre-tax margin in wealth management of 26% to 28%; a firm-wide efficiency ratio of 73%; a medium-term return on tangible common equity target of 11.5% to 14.5%; to return capital yet still to position the asset management business for growth, while also expanding leadership in the institutional securities group (ISG) that encompasses markets trading and investment banking.
In the third quarter of 2018, the firm reported an annualized return on tangible common equity of 13.2% delivered against a strong common equity tier-1 ratio of 16.7%, even after buying back $1.6 billion of common stock during the third quarter.
Wealth management achieved a pre-tax margin of 27.1%; the firm’s efficiency ratio came in at 71%; asset management saw fees rise 6% after its seventh consecutive quarter of net inflows; and institutional securities grew revenues and earnings in an M&A boom. The firm has delivered.
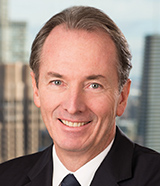 |
| James Gorman |
You don’t often hear Gorman sounding perplexed. If you’ve never met the man, Euromoney wouldn’t advise sitting down with him for a game of poker. But on the third quarter earnings call, he sounded taken aback on the share price action. “It’s a little bewildering against the backdrop of a very strong US economy and we’re overweight the US and gaining share across each of the institutional businesses,” he said. “I guess there are smarter investors than myself out there who have got this figured out. But to me it seems like with the ROE up 40% and the revenue trend that we’ve got, it’s a little hard to reconcile with the stock being down.”
There are consolations.
“What I care about frankly is the long-term positioning of the firm,” he says.
Jonathan Pruzan, chief financial officer, takes Euromoney through some highlights, starting with the institutional securities group.
“We are leaders in equities and maintained our 20% market share in a business where the revenue pool expanded 16%,” says Pruzan. “In fixed income and investment banking, we’ve continued to improve our market share by 1% to 2%, while revenue pools also grew 1% to 2%. That incremental share is important, and we feel that we have momentum.
“Additionally, we feel very good about the margin in wealth management and having hit 70% year to date on the firm-wide efficiency ratio. We have good operating leverage even while continuing to make investments.”
The firm has delivered what it set out to and investors should be optimistic, according to Pruzan. “Morgan Stanley is a strong brand with a stable senior management team,” he says. “We are very happy with the business mix and like the way that the three businesses interact.”
In between the larger wealth management and ISG businesses, asset management sometimes get overlooked. With $471 billion under management, it competes in a consolidating business where size is increasingly important and the leaders start at $1 trillion under management. What can investors look for?
“Instead of focusing on scale, we are focusing on a range of more attractive strategies – real estate, alternatives, private equity, all of which we think have attractive economics and secular growth potential – and not so much on the retail and passive markets,” says Pruzan. “We were able to complete a tuck-in acquisition in 2018.”
In March 2018, the firm bought Mesa West Capital a commercial real estate credit platform with $48 billion of client assets.
Like its eternal rival downtown along the Broadway line, Morgan Stanley is becoming more like a bank. It is lending more.
“One of the drivers in wealth management will be growing beyond where we are now with $70 billion of loans to wealth clients, mostly secured against securities portfolios and real estate,” says Pruzan. “We are also focusing on lending products in institutional securities, again mostly collateralized, where we like the returns for the risk. Additionally, we see lending as a way to deepen relationships with our clients and will continue to grow lending in both segments.”
What should investors who fear a turn the credit cycle turns make of this? Pruzan offers some reassurance.
“Several things are critical for our business, including global growth,” he says. “While estimates may be coming down slightly from their highs, we still see above 2% growth for 2019 in the US, where we do a majority of our business.
“All risk managers right now are focused on credit: both the direction and the pace of travel. We’ve all seen the buildup in credit and know that we have been in a very benign credit environment, albeit with shocks such as in the energy sector in 2015 and 2016.
“I would say that our capital, liquidity and resilience are far greater today than they have ever been and we feel very comfortable. We continue to return capital while investing in our businesses.”



