UBS’s global derivatives franchise delivered record revenue in 2025 while expanding beyond its established strength in equity derivatives. Derivatives and solutions revenue increased by 22% year-on-year to $4.26 billion, principally because of stronger client activity in equities and FX.
The result reflected UBS’s four strategic priorities: gaining share in equity derivatives, strengthening its quantitative investment strategies franchise, expanding rates and credit solutions, and connecting the investment bank more closely with its wealth management business. It also invested selectively by geography, including insurance solutions in Japan, product development in India and deeper capabilities across Southeast Asia.
The value of that structure became clearer as clients navigated concentrated equity indices, divergent monetary policy, geopolitical uncertainty and changing commodity supply chains. Institutional investors wanted to remain exposed to long-term market themes without accepting an unlimited range of outcomes. Wealth clients used structured products increasingly as recurring portfolio construction instruments rather than occasional investments.
UBS responded with capital-efficient overlays, systematic hedging, dispersion strategies, structured financing and cross-asset solutions. Its ability to originate risk in one client channel and redistribute it through another enabled it to support transactions at scale without relying solely on external markets.
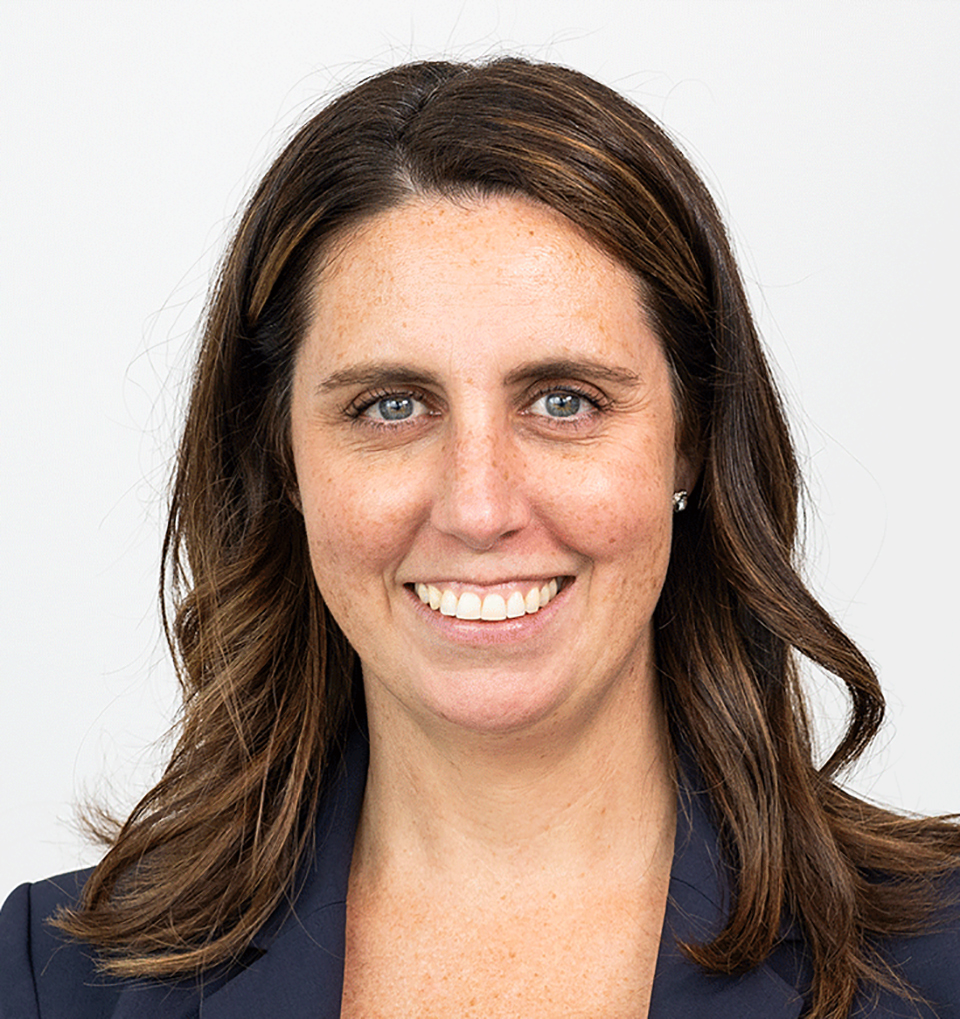
“We have built a unified, cross-asset derivatives franchise that brings together the scale, product breadth, client connectivity, trading expertise and disciplined risk-management capabilities,” says Christine Wang, co-head distribution APAC, global markets. “This has allowed us to better connect risk-recycling opportunities across client segments and deliver customized solutions based on client needs, leveraging the broader UBS platform across divisions, desks, and teams to provide a differentiated offering.”
Building a global market for client risk
Risk recycling is central to UBS’s derivatives model. Its wealth and private bank franchises generate substantial demand for yield-enhancing notes, autocallables, collars and structured financing. These trades can leave the bank with volatility or correlation exposures that institutional clients may want in a different form.
Hedge funds, asset managers, insurers and pension funds can require convexity, dispersion, tail protection or directional exposure. UBS uses its global books to connect those demands. Private bank clients selling volatility can therefore provide risk that offsets institutional purchases of protection. Commodity exposures in producer markets can be matched with consumer flows elsewhere. Regional trading teams can transfer positions across time zones and investor bases.
Our ability to connect opportunities across markets and client segments allows us to respond to clients’ most complex needs with both local insight and global capabilities
Christine Wang
This model was evident in APAC during 2025, when private bank and retail demand made structured products a more consistent source of flow. Large collar transactions, portfolio loans and structured financing trades became a recurring feature of client activity.
The advantage was not limited to originating more products. Internalisation allowed UBS to quote competitively in size, reduce external hedging and preserve capacity during volatile periods. This turned dispersion and market dislocations into a more repeatable cross-asset franchise.
From customised hedge to scalable infrastructure
UBS also demonstrated that bespoke derivatives need not remain isolated transactions. Its institutional quantitative investment solutions were designed to systematise hedging decisions that might otherwise require repeated approval from investment committees.
Traditional protective puts can be expensive, particularly when volatility is elevated. UBS developed defensive skew, thematic-dispersion and total-return strategies intended to protect portfolios while limiting carry costs. Some strategies could generate positive carry in normal markets while retaining convexity during stock-specific or index-level dislocations.
Wang says: “Given heightened market volatility, clients increasingly need us to facilitate risk and help protect against downside in their portfolios. Our cross-asset approach allows us to connect risk-recycling opportunities across client segments and deliver solutions that are tailored to client needs.”
For an insurer seeking tail protection within a regulatory-capital framework, UBS developed a customised overlay supported by crisis analysis, stress testing and capital reporting. The solution examined equity spot shocks and volatility shocks, alongside initial-margin and operational implications. A phased implementation allowed the client to test both the strategy and its supporting processes before increasing scale.
Another institutional client held a concentrated single-stock portfolio for which conventional index hedging provided an imperfect match and persistent drag. UBS designed a thematic-dispersion strategy that combined long volatility in selected shares with short index volatility. The structure targeted stock-level dislocations while offering scalable convexity with limited hedge cost.
The result is a derivatives franchise that acts not merely as a product manufacturer but as a global mechanism for transforming, distributing and managing risk.
“Our ability to connect opportunities across markets and client segments allows us to respond to clients’ most complex needs with both local insight and global capabilities,” says Wang. “The strength of that model is reflected in our sustained growth and record performance.”