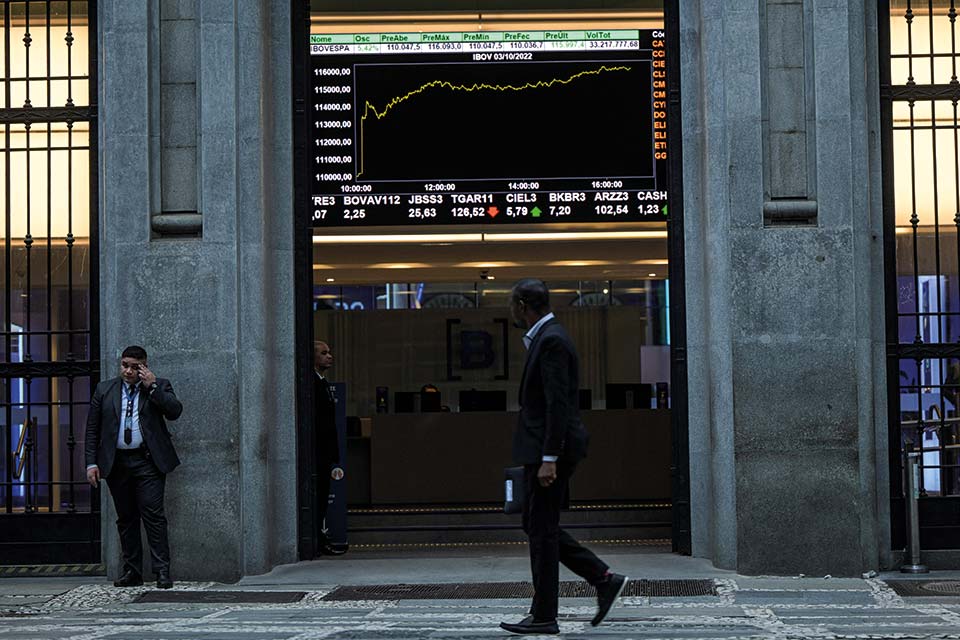
The delisting of Banco Inter from Brazil’s B3 stock exchange – and the downgrading of Nubank’s Brazilian depositary receipt (BDR) programme – will further frustrate the local exchange’s efforts to attract future fintech IPOs.
That’s the opinion of analysts and equity capital market bankers active in Latin America’s digital banking and fintech industry.
Other large Brazilian financial technology companies, such as PagSeguro, Stone and XP Inc, have simply gone direct to US exchanges.
In June, Banco Inter delisted from the Bovespa and switched to the Nasdaq. According to bankers close to the transaction, the deal represented senior management’s desire to attract US-based investors that would value the digital bank at higher multiples than were being priced by local investors.
“The comps and better valuations are in the US,” says one New York ECM banker. “In Brazil, investors tend to look to the incumbent banks – like Itaú and Bradesco – as comps for Banco Inter rather than the multiples applied to growth stocks listed in the US.”
However, the timing of the strategy has frustrated Banco Inter’s ability to generate a quick increase in its market capitalization. The stock has struggled, initially falling below its listing price before rallying back into positive territory in recent weeks.
“We’ve seen growth tech stocks go lower across the board,” says an equities banker. “And at the same time, Inter has lost the constant level of demand that comes from being an index stock – as it was when it traded on the B3. The timing for the switch hasn’t been great.”
However, a fintech analyst in New York believes these are short-term pricing dynamics, and he expects the bank’s strategy to pay off when market volatility subsides.
“The value proposition for digital banks delivering a service is far greater than for the existing banks and a fraction of the cost for providing that service,” he says. “I expect that Inter will be able to grow a market share of between 8% and 12% as customers vote with their feet and move to where they perceive greater value and incentives.
“Meanwhile, the incumbents will be slow to react, given that they have a strategy that means they would rather lose a handful of clients and keep their cost structure rather than reduce fees.”
However, if the B3 harbours hopes that future fintechs will pursue a dual-listing strategy then Nubank’s decision to downgrade its BDRs from level-3 status to level-1 creates questions about the future of such strategies.
In its 2021 IPO Nubank opted for a listing in the US and Brazil. According to one banker that worked on the IPO listing, the underwriting banks advised against such a strategy, the dual structure added huge practical issues to the transaction, such as incorporating the Brazilian regulator’s requirement to publish a pricing range two weeks before launching the roadshow, without generating any incremental demand or pricing benefit.
Financial inclusion
However, Nubank was determined to create a way to enable customers and employees to participate and so created a NuSocios programme that provided BDRs to around 7.5 million clients.
“This operation made it possible for these people to enter and access the Brazilian capital market for the first time – being one of the largest financial inclusion initiatives in the country,” Nubank’s investor relations team told Euromoney.
However, the bank has moved to restructure this programme with “the sole and exclusive objective of maximizing efficiency and minimizing redundancies, optimizing time and resources, reducing and eliminating unnecessary duplicate workloads, which consume considerable resources.”
According to ECM bankers the main impact of the change in the BDR status is a lower level of reporting in Portuguese – Nubank is keen to stress that the bank will maintain Brazilian-traded instruments contrary to many local press reports. It does, however, present a quandary for the B3: will it change its rules to make it harder for companies to downgrade BDRs – and maintain higher and costly compliance requirements – or will it effectively accede to this demand for lower local standards and allow level-1 BDRs to be issued as part of dual listing IPOs in future?
“The regulator needs to think about the distinctions between the levels in the BDRs,” says one banker. “The onus for reporting is very different and I don’t think that it necessarily provides a lot of value for the regional investors – and that’s ultimately the group of investors that we want to make sure are protected and aren’t sold things they shouldn’t be.”
Euromoney contacted B3 for comment without success.
However, not everyone thinks the B3 is in a perilously weak situation when it comes to future fintech IPOs.
By being listed on Nasdaq and/or US, fintechs and neobanks not only increase their potential to attract investors but also are easily compared with global peers
Pedro Carvalho, Fitch Ratings
“We don’t think future fintechs will ignore local listings,” says Pedro Carvalho, associate director financial institutions at Fitch Ratings in Sao Paulo. “It will be a matter of analyzing several factors before deciding for B3, NYSE or Nasdaq. For example – but not limited to – the type of the fintech, its size, the cost on each market and considering also domestic and international interest rates at the time they decide to open capital and how much capital they expect to get.”
However, Carvalho agrees that the trend is going against the Bovespa.
“The migration of fintechs to Nasdaq makes sense given the profile of other listed entities there, focused on technology,” he says. “By being listed on Nasdaq and/or US, fintechs and neobanks not only increase their potential to attract investors but also are easily compared with global peers. We also need to consider the size of Nubank’s IPO, showing a valuation that at the time placed it above several banks in Brazil, would probably be difficult to be absorbed by local investors.”
Closed window
The question is a hypothetical one at present as, given the volatility of the markets, the window for Latin American IPOs remains closed. However, bankers report strong pipelines and some expect some deals in Brazil to follow the presidential elections – although most believe the first quarter of 2023 is a more realistic schedule for the reopening of ECM activity.
In the meantime, private equity companies are continuing to support pre-IPO fintech candidates and management teams are adjusting swiftly to the lower liquidity and high cost of debt for growth companies.
For now, some private equity companies are buying public equities as privately held companies drag their feet on marking down valuation multiples while publicly listed growth companies have seen their valuations slashed.
These lower valuations themselves create obstacles for future IPOs. Given the lower multiples, companies that were once $1.5 billion IPO candidates on the back of revenues of around $100 million are now too small to go public.
“These companies are not underperforming, it’s just that the multiples have come down significantly,” says Facundo Vazquez, head of Latin America ECM at Goldman Sachs. “For companies that need capital, many have more mature pre-IPO shareholder bases, which have been willing to be supportive to the extent they may not be able to raise additional financing elsewhere.”
For companies that need capital, many have more mature pre-IPO shareholder bases, which have been willing to be supportive to the extent they not be able to raise additional financing elsewhere
Facundo Vazquez, Goldman Sachs
One senior ECM banker at a Wall Street firm tells Euromoney that: “Management teams [in Latin America] realize the severity of the impact of inflation and the potential dry-up in liquidity for their funding rounds. And the amount of cost reduction, risk reduction and cash burn reduction that these teams have done is very surprising to me in a positive fashion.”
He adds that private equity companies have been seeing the current closure of the public markets as an opportunity to step in and provide a form of “bridge capital” to fund growth companies into the next cycle. “And that’s capital at a lower valuation than is due to come at what we would expect to be the right IPO level.”
Fitch’s Carvalho reinforces this view: “Under the current scenario, we consider that the fintech segment – especially companies that had not reached a breakeven point and/or that are dependent on capital inflows to sustain their growth strategy of products and clients – may come to a point that they will need to decide between adjusting the pace of growth or accepting lower prices for new, fresh capital – maybe under a private equity structure.”
Ton of cash
Meanwhile, investors are reported to have huge amounts of cash ready to put to work in the sector once an inflection point is reached.
“They tell me that they have a ton of cash to deploy but that they’re happy to potentially lose out on the first couple of percentage points in uptake to make sure that the inflection point has been reached – that the trend is definitely going in the right direction – rather than potentially catch a falling knife,” says a New York-based ECM banker.
And that inflection point is all about US interest rates. For once, idiosyncratic risks in Latin America are far lower in investors’ minds than global macro risks. In fact, Latin America could enter the next emerging markets equities cycle at the front of the queue for international investors’ allocations. With Russia and China seeing outflows – and with Asian and European emerging markets caught up in volatility in these regions – Latin America looks to have better nominal and relative risk-adjusted reward potential than it has in the past two decades.
One senior ECM banker reckons that the return of Brazilian and Latin American ECM will depend on the actions of the US Federal Reserve, but he argues that it will also likely precede fresh US equity issuance.
“When you look at commodities cycles and Latin America, we tend to do much better than the rest of the world, even in challenging conditions. So, I think the Brazilian IPO market is going to open even more quickly than the US once we pass through our election cycles and US interest rates settle.”
He adds that he expects local consumer and retail companies to be at the front of the local IPO queue. Many in the region will be hoping that he is right.


