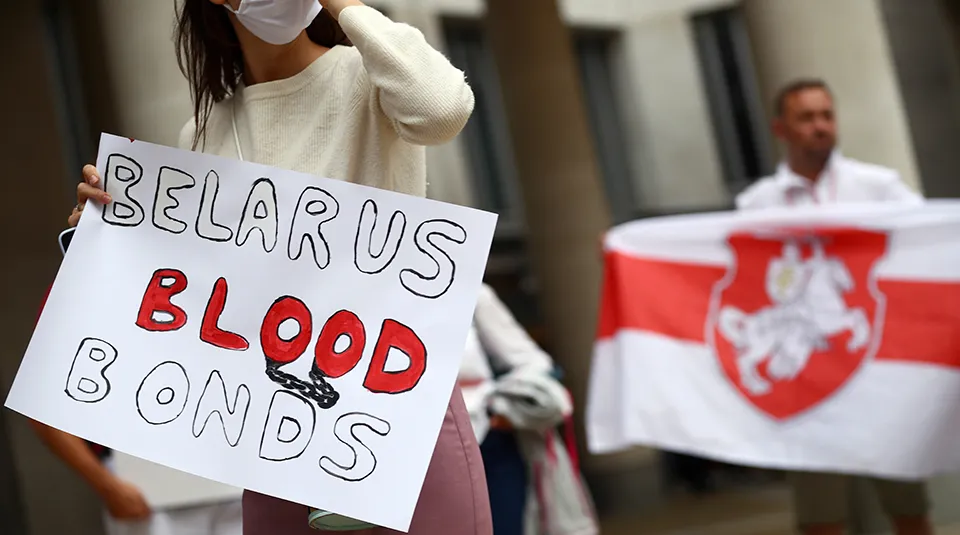
On August 9, the first anniversary of the rigged elections in Belarus that prompted a ferocious crackdown by authorities, the UK government joined the European Union in imposing sanctions on new Belarusian sovereign debt.
A fresh round of US sanctions on Belarus announced on the same day failed to mention sovereign debt. Nevertheless, the direction of travel was clear and, for the moment at least, the Belarusian regime is effectively cut off from raising funds on international bond markets.
This may or may not rattle president Aleksandr Lukashenko, who can count on grudging but sufficient financial support from Moscow in his brutal suppression of dissent. But it might come as some relief to emerging market fund managers, who will now be spared the labour of accounting for their participation in a new Belarusian sovereign deal.
Unfortunately, they are unlikely to be allowed to forget their involvement in the last one. Over the past year, commentators have repeatedly asked how funds can square claims to environmental, social and governance (ESG) awareness with their decision to buy $1.25 billion of Belarusian sovereign bonds last June – and to hold them as the regime turned ever more repressive.
Pressed to defend themselves against charges of hypocrisy, fund managers have – anonymously – offered one or both of the standard responses.
Of the two, “It’s in the index” is clearly the weaker argument. “If we started down that route where would we stop? Should we boycott China?” is more convincing but still misses a trick. What no fund manager ever quite seems to have the nerve to ask their critics, even off the record, is what exactly they think it means to invest in emerging market sovereign debt.
Characteristic
Apart from high growth rates, the defining characteristic of emerging markets – and what sets them apart from their developed counterparts – is weak institutions. This makes for unstable and vulnerable democracies and means that any slide towards authoritarianism may well go unchecked.
Anyone investing in the sovereign bonds of these countries, and particularly in a fund that tracks a broad index, is ipso facto buying instruments issued by countries with unsavoury regimes and undemocratic practices. This is a feature of the product, not a bug.
Does that mean any fund manager advertising itself as a sustainability champion – as nearly all of them are – should avoid the asset class altogether? Would critics of Belarusian bondholders really like to see the whole of the developing world cut off from international capital markets?
Apart from high growth rates, the defining characteristic of emerging markets is weak institutions. This makes for unstable and vulnerable democracies
If the answer is no, as it surely has to be, there is little point in hounding buyers of Belarusian sovereign bonds on human rights grounds.
And there is even less point in demanding, as various well-meaning but financially illiterate activists and politicians have done, that western governments ban asset managers from holding Belarusian sovereign bonds.
The authorities in Minsk already have the cash. It is hard to see what forcing funds to divest the bonds would achieve beyond offering the Belarusian government or its allies an opportunity to buy them back at a thumping discount.
A much more pertinent question for participants in last year’s Belarusian sovereign bond sale would concern their assessment of the ESG risks associated with buying the debt of a notoriously repressive regime less than two months before what was shaping up to be a contentious election.


