Axel Weber’s views on the need for European bank mergers have achieved unusual prominence recently.
One media report revealing board level discussion of a possible merger between UBS and Credit Suisse was followed by a separate article disclosing that Weber has a wish list of potential partners that also features Deutsche Bank and BNP Paribas.
Then at a Bank of America financial services conference in late September, a trio of senior bankers used their virtual appearances to echo the opinion that European banking consolidation is inevitable.
Two of these executives – Credit Suisse chief executive Thomas Gottstein and Deutsche’s chief financial officer James von Moltke – might hope to win senior roles in a Weber-sponsored European mega-bank; while the third – departing UBS chief executive Sergio Ermotti – is serving his final months at the pleasure of his chairman, Weber.
It was almost as though Weber had sent his lieutenants into the field in a coordinated attempt to speed the pace of a long-awaited wave of banking mergers.
Weber (below) may not need to go as far as mounting a diversionary bid for BNP Paribas if his real target is a merger of UBS and Deutsche

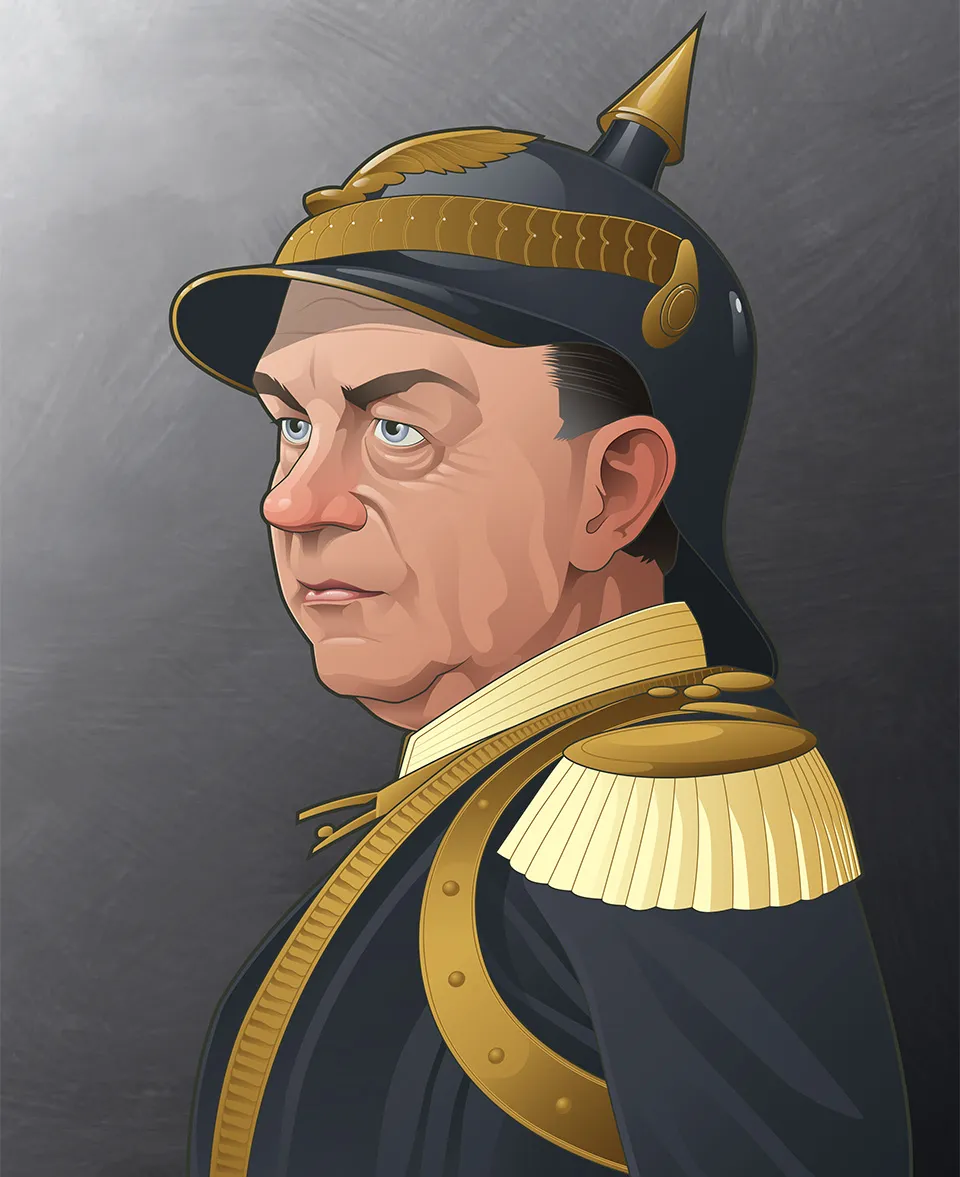
UBS declined to comment on its chairman’s strategic master plan, but Weber appears to see himself as the Otto von Bismarck of European banking: the man of vision who charts a path to unification and drags less inspired financiers in his wake.
Bismarck took over a decade to engineer the road to German unification in 1871, and Weber’s potential European bank mergers face some big hurdles, even if he thinks the time has arrived for action.
The obstacles to a merger of the two biggest banks in Switzerland are so formidable that it is tempting to speculate that this idea only emerged publicly so that the chairmen of UBS and Credit Suisse can give momentum to a broader trend of consolation that they actually aim to exploit separately, for example.
This is not because there is a lack of potential synergies from a merger, and consulting firm McKinsey should have little trouble completing its reported commission to produce a plausible justification for a deal.
Wealth management franchise
The core appeal would be the creation of a wealth management franchise that could become the only important barrier to American dominance of virtually every aspect of global finance.
UBS already has the world’s leading bank wealth management business; a combination with Credit Suisse would create a unit with close to $4.5 trillion of assets under management that would outrank US competitors such as Bank of America and Morgan Stanley.
Wealth management benefits from economies of scale, and an even bigger global business would help managers such as Iqbal Khan – current divisional co-head at UBS and until last year a Credit Suisse employee – to improve efficiency ratios.
A combination of the two firms’ investment banks should not prove too challenging either and could potentially boost provision of capital market services to wealth management clients.
McKinsey could easily crank up the theoretical synergy generator to make a case for a bid by UBS for Credit Suisse that justifies a modest premium to its current share price and would create a merged bank capitalized at around SFr70 billion ($76 billion).
Redundancies would be inevitable to improve returns and compensate for overlapping revenue pools, but the bulk of cost-cutting could be targeted in London and New York with a pledge to limit job losses in Switzerland.
Even in the close-knit Swiss financial community it is nevertheless difficult to see how any self-respecting regulators could give the go-ahead to a merger that would give one bank such a disproportionate scale relative to its national economy as a merged UBS and Credit Suisse.
The real prize, or prizes, may lie within the European Union, where recent regulatory comments can be interpreted as a call to acquisition arms for the region’s banks.
Well-designed and well-executed consolidation can help address the overcapacity and low-profitability problems that have been damaging the European banking sector
Edouard Fernandez-Bollo, ECB

The key change in technical guidance issued by the European Central Bank at the beginning of July was clarity that accounting “badwill”, or negative goodwill from the purchase of a bank that is trading below its nominal book value, can be used to cover merger costs or non-performing loan provisions.
That is a big incentive for deals in a European banking sector that is currently trading at less than 50% of its nominal asset value in aggregate.
An accompanying blog post by ECB supervisory board member Edouard Fernandez-Bollo made the central bank’s stance on mergers unusually clear by regulatory standards.
He issued some disclaimers about the ECB’s nominal neutrality on deal-making, before stating: “But well-designed and well-executed consolidation can help address the overcapacity and low-profitability problems that have been damaging the European banking sector since the last financial crisis, and thereby contribute to the overall financial soundness of the banking system.”
Fernandez-Bollo is the epitome of a member of the blended French financial and political establishment, so it would be interesting to see how he reacted to any consolidation bid that was designed to target BNP Paribas.
France’s largest bank generates roughly 50% more revenue than UBS and has a broader European footprint, but it is the stark cultural mismatch between the two firms that makes a potential link so implausible.
The presence of BNP Paribas on Weber’s supposed merger wish list may be another diversionary tactic in pursuit of his real strategic goal, however.
Weber, a former president of the Bundesbank, was a candidate to become chief executive of Deutsche when Josef Ackermann was approaching retirement.
Better job
In retrospect Weber would almost certainly have done a better job of managing Deutsche’s serial reputational scandals than the insider duo of Anshu Jain and Jürgen Fitschen who succeeded Ackermann in 2012, before being replaced in 2015.
Now Weber may finally have a merger between UBS and Deutsche in sight, and with it control of his native country’s biggest bank after years of leaked discussions about possible divisional tie-ups between the two firms.
When Bismarck achieved unification of the disparate German states in 1871 it was in the wake of victory in a war that he provoked between Prussia and France.
Weber may not need to go as far as mounting a diversionary bid for BNP Paribas if his real target is a merger of UBS and Deutsche.
There are enough signs that he has allies among both bankers and regulators to make UBS a player in a coming reordering of the European financial landscape.
Other banks could quickly become pulled into dealmaking if cross-border bids become part of a consolidation that has so far been limited to single country deals like CaixaBank’s merger with Bankia in Spain, however.
Even a master strategist like Weber could find that he is overtaken by the course of events once that trend gets under way.



