|
|
Success stories spawn imitators. Such is the case with First Abu Dhabi Bank (FAB), the large Emirati financial institution formed by the merger in April 2017 of National Bank of Abu Dhabi and First Gulf Bank.
Since then, a string of projected mergers and acquisitions have been announced in the Gulf, including, among others: Saudi British Bank and Alawwal Bank in Saudi Arabia; Kuwait Finance House and Bahrain’s Ahli United Bank; and Barwan Bank and International Bank of Qatar.
These proposed mergers reflect an urgent need for banking consolidation in the region. They are also a testament to FAB’s early success; such was its status as a test case for banking mergers in the region.
Only one year into the new bank’s existence, its chief executive Abdulhamid Saeed could say: “In a short period of time, we have successfully completed many of our key integration milestones, reinforced the financial position of the new combined bank and realized cost synergies totalling approximately Dh500 million ($136 million).”
By the end of September 2018, that early positive impression had solidified into positive results, with FAB’s profit before tax rising by an impressive 11%, to Dh9.4 billion year on year. This rise was driven to a large extent by a Dh286 million reduction in operating expenses and a Dh524 million reduction in net impairment charges, as the costs of merging two large and complex banks started to fall and synergies started to bear fruit.
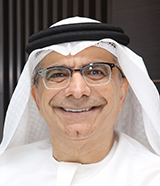 |
| Abdulhamid Saeed |
While costs are declining fast, operating income is not showing such positive momentum, with an increase of just 1% over the year. That explains the good but not quite extraordinary fall in the bank’s cost-to-income ratio, which went from 27.5% to 25.6% between September 2017 and September 2018. Loans and advances rose, up 3% quarter on quarter and 8% year on year, primarily driven, the bank says, by its corporate and investment bank. But growth in net interest income continued to suffer, with growth of just 0.6% over the year to September 2018, in part due to margin compression.
FAB has made a big impression on Gulf banking in record time. FAB boasts the strongest credit ratings across the three main rating agencies of any large bank in the Middle East and north Africa (MENA), ahead of its main rival, Qatar National Bank (QNB).
The bank is now the UAE’s largest and the second largest in MENA, after QNB – a leadership position coveted by the Qatari bank, which has $35 billion more in assets than FAB.
But FAB also appears intent on competing with QNB on size, with asset growth of 9.4% by the end of the third quarter – to $200 billion-equivalent. With QNB’s assets growing by 7.7%, FAB has started to close the gap, if slowly.
FAB does not have QNB’s geographical diversity, however. Although present on five continents, the Emirati bank derives 87% of its revenues from the UAE, with just 10% from Europe, the Americas, Africa and the rest of the Middle East. Asia Pacific, although a market with a great deal of promise for the Middle East, thanks largely to growing commercial ties with China, represents just 3% of revenues.
The bank clearly has grand aspirations. One of these is to act as the Emiratis’ banking champion, a position of prestige long held by Dubai’s Emirates NBD – and one that carries with it the weight of the UAE’s geopolitical ambitions.
It is already working to expand its reach outside the UAE.
In February 2018, FAB obtained an investment banking licence in Saudi Arabia. A commercial banking one followed the next month.
Saeed welcomed that, saying: “These developments give us the platform to tap into the region’s largest economy with the full strength and capabilities of the FAB offering.”
FAB, like QNB, wishes to be seen as one of the world’s great financial institutions. At the start of 2018 it published a presentation – ‘First Abu Dhabi Bank vs peer banks’ – comparing the bank’s ratings, capital adequacy, return on equity and international footprint with some of the best-known institutions globally.
With most of FAB’s key integration targets met in 2017 – harmonization of policies and risk frameworks, pricing harmonization in the corporate and investment bank, and network optimization – the bank has achieved many of its synergy targets early on. By the end of 2018, it was due to have unified its IT systems and in November announced that it was on track to do so.
FAB hopes to have achieved cost synergies of Dh1.5 billion by 2020, with two thirds of that achieved by the end of 2018. Again, it said in November it was on track to hit that target.



