Awards for Excellence 2017
|
|
|
Also shortlisted |
BBVA |
Citi |
Erste Bank |
Economic liberalization drove the success of many emerging markets of the previous decade. Today, those economies are no longer so unexplored. Now, countries that combine a demographic bulge and economic liberalization promise the greatest growth potential. These are economies in which banking markets are far from saturated, but often the risks can be extreme.
Posting high returns as a universal bank in these markets, where interest rates are naturally high, can be easy in the good times. To sustain it during the inevitably volatile economic and political transitions requires nimble risk management and deep local knowledge. Often treated as a proxy for the Egyptian economy, Commercial International Bank (CIB) ticks both those boxes and many more. As Euromoney’s awards now recognize best-in-class performance as well as global spread, domestically focused CIB is a deserving winner of Euromoney’s 2017 award for best bank in the emerging markets.
|
|
|
Hisham Ezz Al Arab, |
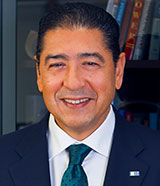
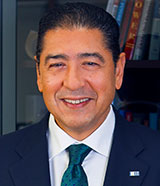
CIB’s chairman and managing director Hisham Ezz Al Arab describes the bank’s approach as firstly: “Staying away from the emotional side of decision-making” and secondly: “Anticipating where a problem could arise and preparing for it beforehand”. Conservative, pre-emptive and nimble are the watchwords (lessons, perhaps, that many banks from more developed markets could learn). “We are not a small bank, we have more than 6,000 employees, but we are able to move very quickly,” says Al Arab.
After the Arab Spring of 2011, some of the transitions CIB has been through recently include the removal of fuel subsidies, high inflation and – most important over the past year – the November 2016 currency flotation and 50% devaluation. Preparing for and managing the aftermath of those events did not just involve provisioning against clients the bank thought would be hardest hit. It also meant staying away from foreign currency-denominated lending as the risks of a devaluation grew. It even meant investing in branch-level facilities to improve energy efficiency in anticipation of changes to fuel subsidies.
CIB was conscious that the biggest cost from lower subsidy payments, given relatively low corporate leverage, would be social. As a result, it renegotiated terms with suppliers and increased wages each month to match the average inflation rate, with a higher rate of increase for lower-paid employees such as messengers and drivers. “We are part of the community,” is how Al Arab sees it.
Such awareness of social costs has not stopped CIB making stellar profits, however. It is extremely efficient, even by regional standards (the cost-to-income ratio was just 21% in 2016). Through revolution and crisis, CIB’s return on equity has not dipped below 20% in a decade and reached 34% in 2016, with the trend continuing into this year. At the same time its balance sheet remains robust, with tier-1 capital around 14%.
Over the last decade-and-a-half, CIB has gone from a relatively small corporate lender to a full-service retail bank – largely because of the opportunities it saw in demographic change and the potential for growth of the middle classes. Its branches and employees have consequently more than doubled, but its $5 billion market capitalization has grown even faster – about 10 times higher today than in 2000. Institutions (mostly North American) make up more than 90% of its 93% free float, with the rest relatively equally spread between global regions.
Now it is investing in the digital opportunities specific to emerging markets, which it sees as a way to extend more banking products to the poorest sections of the society by keeping down transaction costs. A data and SME banking-push, meanwhile, has involved a shift in financial scoring, taking into account around 2,000 factors to assess creditworthiness even where a borrower lacks credit history. This involves everything from mobile-phone and utility bill data, to assessing a customer’s place in society via social media connectivity.
After CIB’s board of directors approved a new African expansion plan in May, Al Arab says the next stage will be to take this kind of expertise and extend it to African countries with economic structures similar to Egypt.
CIB has played a central role in managing the social impact of political upheavals this decade, notably by trying to ensure cash flowed at times of crisis. Al Arab is also chairman of the Federation of Egyptian Banks and was instrumental in setting up a National Payments Council to help unify payments laws, reduce the role of cash in society and help formalize the economy. Nevertheless, Al Arab points to the experience of demonetization in India and what impact such a move could have in Egypt.
“Change is best managed gradually,” he says. “You can’t use shock.”



