|
“This business is still evolving; it’s still young. I think we’ll see another five years of tangible development” Glenn Stevens, Gain Capital |
It is easy to forget just how recently the retail foreign exchange market emerged. A decade ago, it barely existed; now it is an established and important global business. Retail FX was able to emerge for several reasons, including technology. But perhaps the main factor was the drive provided by a small group of entrepreneurs who recognized that it could be a viable product. The precise size of the market is hard to ascertain. Data from the 2008 Euromoney FX Poll suggested that as much as $80 billion a day could be flowing from the retail sector to the bank liquidity providers. More recent estimates suggest average daily turnover might be $125 billion.
Because there was no template, various approaches were taken by the first retail providers. Some viewed it as a technological exercise, while others saw it as akin to running a bookmaker. Very few saw it as an extension of the professional FX market.
One company that did was Gain Capital, founded in late 1999 by Mark Galant, who had been global head of FX option trading at Credit Suisse before joining technology vendor FNX. Galant was soon joined at Gain by Glenn Stevens, who had started his career at Bankers Trust in 1984 before moving on to senior roles at Merrill Lynch and NatWest. Stevens is now chief executive of Gain.
Unfortunate attraction
One of the unfortunate side-effects of the success of retail FX is that the industry attracted some unscrupulous and even completely crooked operators.
“For a long time, particularly in the US, we were staunch supporters of stronger regulation and more oversight because there were quite a few marginal players casting a pall on the industry, says Stevens. “We were the first company to voluntarily register as a futures commission market (FCM) in 2001 – before it was a requirement. Obviously, there were some marketing benefits for us to do so, but it really was about trying to make the industry more professional overall.”
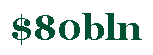 |
retail sector’s daily flows to bank liquidity providers |
As a result of more stringent capital requirements, the number of forex dealer members (FDMs) operating in the US has declined from 34 at the start of 2008 to 17 today. Stevens welcomes this and other changes but is concerned about what he sees as a lack of understanding about the industry. “The FX firms do not have enough of a voice with the regulators to help shape new regulations… The result is that the US regulator is bringing in broad measures which don’t necessarily help the retail investor, and may stifle innovation in our industry,” he says. This might force companies such as Gain to consider moving clients offshore. “We’ve recently gone through the registration process with the FSA, the UK’s regulatory body, and from what we have experienced to date, it seems that many of their rules are more logical from the provider’s perspective and offer the retail investor more protection,” Stevens says.
“This business is still evolving; it’s still young. I think we’ll see another five years of tangible development, such as new players, some consolidation and new products, such as options. I also think that the consistency of regulatory frameworks will not happen as quickly as people think. There are going to remain differences between Asia, the US and Europe.” And if that proves true, the likelihood is that retail providers will be forced to play the game of regulatory arbitrage.
Challenging start
Stevens can now look back on Gain’s early days and admit that things did not go according to plan. “The start was very interesting for two reasons,” he says. “One was not FX-related at all. In 1999, we were still in the internet bubble and it seemed that everyone was scrambling for bandwidth and server hosting and all those things that any web-based business needed… You had five minutes to make a decision with no negotiating power.”
No labels
Gain also possibly made things initially harder for itself by building its own platform. “Some of our peers, which are successful to this day, chose to license or white label an existing platform and throw all their resources into marketing. It remains to be seen still which model will prove more effective in the long run, but I believe our build approach will prove superior,” he says.
Companies such as Gain, Saxo Bank, Oanda and FXCM appear to have benefited from a degree of first-mover advantage. All appear well capitalized and are now in the position, if they choose, to act as consolidators.
Stevens says part of Gain’s approach was to offer streaming prices, which none of its competitors was doing. The only problem was that many of its clients did not seem to recognize the distinction. “What we didn’t realize was how much education the end user needed to understand the difference. That’s when we had to embark on a much more aggressive marketing campaign.”
Things started to pick up when Gain bought the forex.com domain name in 2003. According to its latest monthly filing with the US Commodity Futures and Trading Commission, Gain has $90.8 million of net adjusted capital, making it the second-largest FDM in the US by capitalization.



