 |
Best Bank: HDFC |
Although ICICI, long India’s strongest private-sector bank, managed to look mildly foolish last year, unveiling losses connected to the US sub-prime market, rival HDFC Bank has emerged looking stronger than ever. Driven by chairman Deepak Parekh and chief executive Aditya Puri, a man who enjoys peace and quiet over profits and quarterlies, HDFC posted a 53.1% year-on-year rise in first-quarter 2009 revenues, to Rs53.7 billion ($670 million). It also posted strong gains in net revenues, up 34% year on year in the first three months, to Rs35.1 billion, with net profit also gaining by more than a third over the period, to Rs6.31 billion. The future looks strong, too. Analysts reckon that the State Bank of India’s special concessional rate of 8% on home loans will not provide a threat to the country’s leading mortgage provider. HDFC’s underlying strength is also attracting praise: in a May 5 2009 research note, Macquarie maintained its outperform rating on the bank, noting that HDFC’s “resilient” margins and “robust” loan growth did not hide any concerns about asset quality. Rival ICICI, which was forced to admit to losses during the second half of 2008 as the US housing market unravelled, will certainly look to regain its former market pre-eminence in 2009-10. For now, though, India’s largest provider of home loans is enjoying some well-earned time in the spotlight.
 |
|
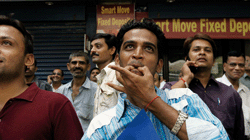
People watched in May as India’s stock market surged 17% on news of the re-election of the Congress Party |
ICICI notwithstanding, India’s lenders escaped on sub-prime but Mumbai’s fast-rising capital markets were still walloped by the global financial crisis. Equity capital market activity slowed to a virtual crawl after spring 2008, only regaining momentum after a resounding victory in this summer’s 2009 parliamentary elections by the pro-business Congress party. What light there was over the past 12 months came from a smattering of ECM and mergers and acquisitions deals, notably follow-on equity sales by aluminium maker Hindalco and real estate firm DLF, which raised $929 million and $781 million in October 2008 and May 2009 respectively. The M&A market was marginally stronger, with Africa’s largest mobile phone company, MTN Group, seeking a 7.66% stake in India’s Bharti Airtel, for $9.5 billion, and the Aditya Birla Group-owned Idea Cellular stumping up $1.7 billion for a 15% stake in Malaysia’s TM International. Both of the latter companies then combined to buy a 40% stake in telecoms firm Spice Communications for $115 million. The common theme running through these deals was Deutsche Bank, an increasingly powerful retail presence on the ground in India. The global investment bank proved tougher than its peers, notably the second-ranked investment house, Bank of America Merrill Lynch, in a year when brains and brawn were paramount, allied to internal stability and a strong balance sheet. In India, Deutsche now has them all.


