Commodities: Investment-flow sense and nonsense
A HUGE RALLY in the prices of agricultural commodities over the past two years and a compelling investment story that weaves in favourable secular trends in both supply and demand have attracted an unprecedented amount of investor interest. A sharp correction in prices at the end of the first quarter of 2008 has, however, put convictions to the test and led to a shaking out of speculators and a re-evaluation of strategies. With investors converging on the consensus that the rally in agricultural commodity prices has moved into a new and slower phase, they are increasingly looking at new ways to play the theme.
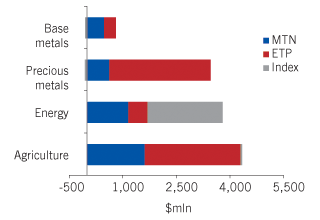
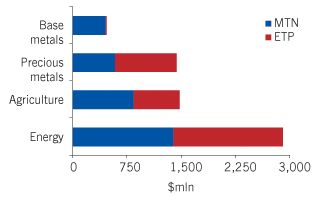
Agriculture was the darling of commodity investors in the first quarter of 2008, attracting close to $4 billion in net investor inflows, more than any other commodity sub-sector including energy, as investors chased stellar increases in the prices of staples such as wheat and corn, which, at their peaks earlier this year, had more than doubled in less than a year and today remain about 37% and 50%, respectively, above what they were 12 months ago.
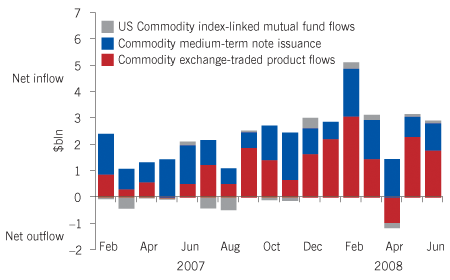
By the end of the second quarter, however, net inflows had halved to less than $2 billion, in line with the 51% fall in inflows into all commodities, and energy had reasserted itself as the favourite sector of commodity investors.
Inflows into agricultural exchange-traded products, which in the first quarter of 2008 attracted more than two-thirds of investor money, fell 76% in the second quarter to just $579 million. Following the correction in March, when agricultural commodity prices were hit hard by a combination of a strong supply response and a broad sell-off across all commodities, net inflows remained at about $300 million in April and May, and in July there were the first outflows as volatility and waning enthusiasm followed months of relative underperformance, leading to caution among retail investors – some of the theme’s biggest fans.
“A large correction due to positions being adjusted after the planting season, such as we saw in March, often happens,” says Stephan Wrobel, chief executive of Diapason Commodities Management, a leading commodities investment house. “To some extent the market is also just digesting its gains of the past 18 months, during which time some agriculture indices have risen as much as 100%. A 20% consolidation in this context is fairly normal, but the secular themes behind the rally in agricultural commodities are still in play because the big picture of supply and demand has not yet been rebalanced. Losses in the credit and equity markets have, however, eroded the patience of investors as well as their ability to tolerate volatility.”
The investment case for agricultural commodities is based on a strong alignment of trends in supply and demand. Population growth and rising incomes in developing countries are leading to a strong increase in demand for all sorts of food, particularly protein, which in the form of meat and dairy products requires vast amounts of cereals. At the same time, the higher price of oil and gas has increased the cost of production, as fertilizers are largely hydrocarbon-based, and led to a dramatic increase in the demand for crops such as corn because of government policies in the US and EU encouraging biofuels as a means to reduce oil consumption.
Supply growth, however, has not kept pace with demand growth – a prolonged period of low prices discouraged investment and led to programmes to reduce production in key food-producing regions such as the EU.
The impact of these trends on prices took time to be felt, as buffer stocks met imbalances. The erosion of these buffer stocks to record lows has led to a tightening of the balance between supply and demand, making prices much more sensitive to supply shocks, which have also been plentiful. Drought in Australia, a major wheat exporter, contributed to the dramatic rise in wheat prices in 2007 and the mere threat of a ban on wheat exports from Kazakhstan earlier this year sent prices up 20%. Flooding in the US Midwest also led to a huge but brief surge in corn prices, which later subsided as fears of its impact on crops receded following better weather.
Agriculture has also attracted the attention of investors because of inflation.
“A key theme that has brought attention to the agriculture sector has been the focus on inflation,” says Tim Owens, global head of commodity solutions at JPMorgan. “Investors have become a lot more sensitive to the rise in inflation throughout the world, particularly in Asia and the US. We see more and more clients looking to commodities as a way to protect themselves.”
 |
Investors are better off with a higher weighting to energy and agricultural and livestock commodities.” |
Investors looking to hedge against inflation are particularly interested in agricultural commodities because of their direct link to inflation as weighty items in the goods baskets used to measure price levels. Research by JPMorgan suggests that the ideal portfolio of commodities for investors looking for an inflation hedge should have a far heavier weighting of agricultural commodities than is found in the most popular commodity index, the S&P GSCI, where the two sub-sectors together have a weighting of just 14.5%.
“A lot of the academic work looks at commodities as a single asset class,” explains Jennie Byun, head of the commodities index research team at JPMorgan. “While indices with a heavy weighting towards energy like the S&P GSCI do provide some protection against inflation, we found that a more balanced allocation between the different major commodity groups along the lines of 30% energy, 26% precious metals, 28% industrial metals and 16% in agriculture and livestock provides the best outperformance. Moreover, for investors concerned not just with inflation but more particularly rising inflation, the weighting for agricultural and livestock commodities should be even higher, at 25%.”
JPMorgan’s research also shows that one of the most popular inflation hedges – gold – might not be as useful as its popularity would suggest in times of rising inflation.
“Our analysis suggests that although precious metals including gold have a place in inflation-beating portfolios, they do not provide as good a hedge in periods of rising inflation,” says Owens. “In fact, when inflation is rising, the cost of holding gold is quite high as it is linked to interest rates. Investors are better off with a higher weighting to energy and agricultural and livestock commodities.”
The huge rise in prices across the main agricultural commodities over the past two years has, however, led many investors to believe that the next phase of the bull market will be more measured, although record low inventories mean that the market is likely to remain jumpy. This growing conviction has turned the attention of investors to the next chapter in the agriculture story, the response of supply to higher prices and the search for ways to benefit from an increase in agricultural production volumes as well as prices. This is leading them increasingly towards the equity market.
|
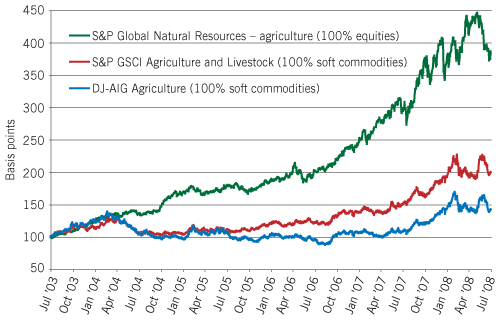
Equities outperform soft commodities |
|
Equity and soft commodity indices over five years |
 |
|
Source: Credit Agricole Asset Management |
“There are three main reasons why investors should turn their attention from commodity derivatives to equity plays,” says Nicolas Fargneau manager of Crédit Agricole Asset Management’s CAAM Funds Global Agriculture fund. “There are just four main liquid contracts for soft commodities: wheat, corn, soya beans and sugar. For many commodities, including rice, milk, fruit and vegetables, there either are no futures contracts available or the markets are too small for investors to access. This severely limits the investment opportunities available through derivatives but there are companies to invest in that are active in all these areas, giving you a much larger investment universe. “The second reason is that when you invest directly in commodities themselves, you get exposed to a lot of speculatively driven short-term price volatility. When you invest in a company, by contrast, what you get is exposure to the price trend because the impact of prices on them comes from one harvest to the next.
“The third reason, which is perhaps the most crucial one today, is that buying a commodity gives you only a capital gain on price increases and we think that although it has been a nice ride, the best part is already over. The first phase has been about rising prices but the second phase will be about increasing production in a more stable price environment, in which case it makes sense to switch to companies that will benefit more from volume growth than from prices.”
The chain
The variety of equity plays cuts across traditional sector lines. Crédit Agricole’s CAAM Funds Global Agriculture fund, launched this July, focuses on companies upstream in the food production chain, on companies for which higher prices are actually a good thing, and is based on three sectors that the firm has defined itself: agriproducts; livestock operations; and support. The first embraces companies involved directly in growing, trading and marketing crops; the second, companies that are involved in the production but not processing of all forms of protein such as livestock, dairy products and fish; and the third, firms that provide things that contribute to the first two. The last sector includes the broadest range of companies from across traditional sector classifications, such as fertilizer manufacturers, seed companies, manufacturers of irrigation systems and farm equipment, as well as banks such as Banco do Brasil, because it has about two-thirds of its loan book with Brazilian farmers. High-tech companies such as one that makes GPS software to track cattle herds and biotech names are also included.
This July HSBC launched its Optimized Global Agriculture Index, which focuses on companies that work in areas that are direct inputs to plant and crop growth, such as seeds, fertilizers, pesticides and genetically modified crops, to try to give investors access to what it believes is a less volatile beneficiary of the agriculture theme.
“The basic premise of our index is that over the next few decades the amount of food the world produces will have to increase significantly in order to feed a global population that is expected to rise from 6 billion to 9 billion by 2050,” says Paul Thind, head of EMEA third-party structured product development at HSBC. “Investing in the inputs that go into plant production should be less volatile than crop prices themselves as they target the volume of food that needs to be produced rather than the price and these inputs need to be repeated with each crop cycle.”
SG, meanwhile, has launched a broader-based agriculture index that includes equipment manufacturers as well as fertilizer, chemicals and livestock companies. It has already developed a number of related investment products.
|
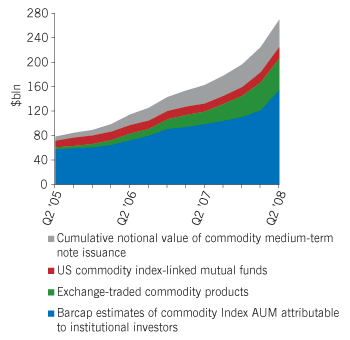
Where the assets are |
|
|
Investments flows |
|
 |
|
|
Changing sector preferences |
|
|
Inflows by different modes of investment, Q1 ’08 |
|
 |
|
|
Inflows, Q2 ’08 |
|
 |
|
|
Inflows and outflows |
|
 |
|
|
Source: Barclays Capital |
The agriculture theme is also finding its way into broader-based funds such as Fidelity’s recently launched Asian Aggressive Fund, in which agriculture-related companies are a significant element, along with infrastructure firms in an essentially regional growth fund. “Investors must look beyond the obvious agriculture plays to find the best ideas in Asia,” says David Urquhart, manager of the fund. “Agriculture is more than just food. Seed, fertilizers, pesticides and equipment are all required by farmers. They also need land, and logistics companies to transport their produce to food and beverage companies, and then on to supermarkets.”
One stock that the fund has invested in for, example, is Incitec Pivot, an Australian company that specializes in the manufacture, distribution and sale of fertilizers that has key raw material costs locked in for the next 17 years.
Another factor that has drawn investor interest in the macro trends that have made agriculture such a prominent investment theme away from the agricultural commodities themselves and towards equities is the high negative roll yields associated with agricultural futures. For example, these have at times been as high as 20% for corn.
This compares with a negative roll yield of just 7.4% for the S&P GSCI and 8% for the Dow Jones AIG.
The reason for the negative roll yield is the contango or upward slope in the forward curves of agricultural commodities, which exists because many of them have just one supply event a year, when the crop is harvested. Farmers need an incentive to store some crop rather than sell it all immediately and so need to be compensated for the cost of storage.
“The high negative roll yield on agricultural futures is a very significant drag on performance, so investors are looking beyond simple index exposure,” says David Hoile, head of asset research at investment consultants Watson Wyatt. “One alternative is more dynamically managed futures, but another possible way to access the theme in a broad way is via the equity market. If it’s your belief that higher demand for agricultural goods and output in the future will be driven by large and ongoing structural economic changes, then that higher demand needs to be met by higher supply and there are companies providing products, services and equipment that will be beneficiaries of that trend. Investing in them will allow you to build exposure not just to grain or soft commodity price rises but to the whole chain of suppliers and beneficiaries,” says Hoile.
“Investors are first trying to work out if there is a logical, understandable structural investment case within agriculture and then how best to exploit that for the long term. There has been a proliferation of products around this theme and the key thing for investors is making sure that these products are robustly aligned with the long-term investment case and are cost-effective,” Hoile says.
Equities from the agriculture and livestock sector have significantly outperformed the soft commodity prices for years. The S&P Global Natural Resources Agriculture sub-index, an equity index, has risen over 250% since July 2003 while the S&P GSCI has “only” doubled (see graph).
Equities, however, do not give nearly as much diversification as the futures themselves and diversification is one of the primary drivers behind investor interest in commodities.
 |
|
“Secular themes behind the rally in agricultural commodities are still in play because the big picture of supply and demand has not yet been rebalanced” |
“Our view is that when you buy equities you buy a completely different animal,” says Wrobel at Diapason. “Commodities react to supply and demand and you know clearly what will happen when things change. When you buy a company, by contrast, there are a lot of other things that will affect performance, such as the management and the balance sheet. You only need to look at the recent performance of the oil sector to know that you can see share prices go down even as commodity prices rise.” Another investment play on the agriculture theme that has emerged as investors start to look beyond the futures market and towards the response of producers is investing in that most basic of agricultural inputs – land. In the past few months in particular there has been a substantial increase in the number of investment vehicles listed on such exchanges as London’s AIM and Stockholm’s First North that plan to invest significant sums in buying up agricultural land in eastern Europe and Latin America.
“Agricultural land prices are going up all over the world, sometimes at incredible rates” says Adam Oliver, director at Brown & Co, an agribusiness consultancy. “In Poland, for example, the price of good agricultural land has shot up from about £3,500 per hectare two years ago to about £5,800 per hectare today. Nine years ago the price was just £300 per hectare.
“That kind of increase is reflected in other markets too but there is particular interest in Ukraine and Russia at the moment because prices there are still close to the bottom of the curve and are considered to be undervalued,” says Oliver. “Land in Russia is currently going for about £500 per hectare.”
Early investors in the great land grab included investment banks such as Renaissance Capital and Goldman Sachs, as well as hedge funds such as Trigon Agriculture. However, private equity players have also been active.
Security
Other groups of investors to have shown interest in acquiring agricultural land are Middle East sovereign wealth funds and governments interested in food security.
While private-sector investment to date has consisted mainly of buying large swathes of land for speculative reasons, governments, particularly in eastern Europe, have shown distaste for investors who do not put the land to work. Food-price inflation has led to government policies aimed at putting land back into production and there is now legislation in place in Ukraine and Russia that enables the state to reclaim any land that is left unused for more than two years.
“Investing in agricultural land has moved into a second phase,” says Oliver at Brown & Co. “The market is dividing into two, with some companies focused purely on land-grabbing and asset appreciation and others looking at putting the land into production, with all the additional investment that that requires and with land acquisition representing just 30% of the overall investment portfolio. The second group of companies are likely to be more successful than the land grabbers because the market will differentiate between investment vehicles in the future. To date, the market has been focused on the asset-appreciation play, but as more companies enter and investors get more choice, ultimately it will be discounted cashflows that generate the value, and the only way to get any cashflow from land is to put it to work.”
Agriculture as a structural investment theme has captured the imagination of a lot of investors but enthusiasm for direct investments has waned as it has for other commodity sectors as the reality that even commodity prices can go down as well as up has hit home. Corrections have been all the more painful because of losses in other asset classes and because, despite talk of motives such as diversification, most investors have also been hoping that gains in commodities could help to at least partly offset greater losses elsewhere.
A shift in investment flows from bets on rising prices to companies supporting supply’s response to higher prices is a logical next step. This second wave of investment is also likely to prove a lot less controversial than the first.



