 |
THE GLOBAL FOREIGN exchange industry’s reputation has been suffering over the past year. At the start of 2003, John Rusnak, a rogue forex trader at the US unit of Allied Irish Banks, was jailed for seven and a half years. It was an unfortunate but thankfully rare example of a breakdown in trading procedures.
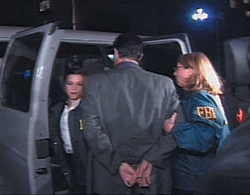
But the industry did not have to wait long for its next big case. Last November in New York, 47 currency traders were arrested after an 18-month undercover investigation by the FBI, dubbed Operation Wooden Nickel. Alleged offences included fraudulent schemes and other criminal offences such as money laundering, extortion and so-called points for cash.
The arrests included employees of some of the financial industry’s best known firms including JPMorgan Chase, UBS and Dresdner Kleinwort Wasserstein. None of these cases has yet gone to trial but legal proceedings continue.
Any hopes of a less turbulent 2004 were soon scuppered when National Australia Bank suspended four traders in January after it uncovered unauthorized currency options trades.
The scandals were unrelated, but a pattern of lax regulation, poor supervision and dubious trading practices appear to be emerging.
With over 19,000 members in 78 countries, the Paris-based Financial Markets Association has the largest membership of any of the international associations in the wholesale financial markets. It went so far as to say that the apparent discovery of a network of small-time miscreants in the New York forex market had “cast a dark cloud over the entire industry”. Regulatory authorities and banks are under pressure to respond.
It is important to get this right – and not just for the forex market. Currency flows underpin international bond and equity markets and have an impact on mergers and acquisitions. So while periodic scandals might promote demands for better regulation, unforeseen consequences might arise if regulation were to become too strict.
A difficult market to regulate Regulation of the forex market is difficult as it is so vast, liquid and international. It lacks any national exchanges. It does not entail issuers raising new capital from investors and so has no equivalent to the requirements for disclosure and prospectuses. Central banks around the world have set up committees to review these issues, and they gather the views of market participants to produce best-practice guidelines, but that raises the question of how these should be coordinated internationally.
Ultimately, it is up to market participants to implement these codes.
That almost sounds too easy. But it does not follow that the forex market is a regulatory black hole. “Regulated banks and broker dealers are already subject to a framework of statutory and regulatory controls,” says Darren Fox, a solicitor at Simmons & Simmons. “Even though wholesale forex trading is not itself a regulated activity, these statutory and regulatory requirements do bite on the forex activities of regulated firms.”
And the good news, for those worried about international application of these guidelines, is that national committees tend to have the same concerns. Mark Snyder, vice-president and global head of foreign exchange and money markets for State Street Corporation and the newly appointed chairman of the foreign exchange committee (FXC) at the Federal Reserve Bank of New York, says that most national forex committees act collectively as there is so much dialogue between them. Furthermore, they include representatives of the world’s top 30 banks: “The FXC has worked with a number of other committees on the issues of non-deliverable forward trading, T+1, and electronic trading. We are in dialogue about other issues such as unnamed forex or undisclosed principal trading. There is an opportunity for more collaboration in the future between the different committees.”
The FXC submitted a statement after last November’s scandal outlining the committee’s concerns about the use of points in forex trading. This involves currency traders rigging trades that are purposely designed to produce losses for their employers’ accounts but corresponding profits for their co-conspirators on the outside. Proposed controls to minimize this potential abuse might include time-stamping of trades and straight-through processing.
Some institutions, including State Street, had already acted to bar this practice before the FXC’s statement. And this kind of self-regulation is often key to new guidelines. “It is in the interest of market participants to implement ethical self-regulation because it is the best way to operate the forex market,” says Robert Loewy, head of foreign exchange at HSBC. “Otherwise an official regulator would have to impose mandatory rules, which could be detrimental to the functioning of the industry.”
Sticking to new non-statutory guidelines certainly helps to maintain a good reputation. “Peer pressure is a very powerful motivator for market practice in foreign exchange, so it is in the participants’ interest to comply with any guidelines,” says Joseph De Feo, president and CEO of CLS Bank International.
Retail confusion The division between retail and wholesale forex has become blurred in the past few years. Following the New York arrests, the FXC is keen to determine whether any revisions are needed in the retail sector. “The FXC has always supported federal regulatory enforcement authority to protect small, individual investors from abuse,” says Snyder at State Street. “The committee will see what, if any, guidelines should be revised so that wholesale forex market participants may become more aware and vigilant regarding the distinction between wholesale and retail services.”
Hotspot FXi, which offers online currency trading to a range of types of clients, already views the institutional and retail sectors differently. “We operate wholly separate retail and institutional marketplaces,” says John Eley, CEO of Hotspot FXi. “We are supporters of strong customer protection regulations in our retail marketplace and in our institutional marketplace. We support best practices, self-regulation and technological initiatives to enhance the functioning of the market with formal regulation as a last resort.”
There is some evidence then that the forex industry has already been adapting through self-discipline.
Last May, the Bank of England’s Foreign Exchange Joint Standing Committee agreed on a new process to stop undisclosed principal trading in order to enable better risk management. Concern surrounds transactions where a fund manager, acting as an agent, trades on behalf of a client – the principal to the transaction – with a counterparty, but does not reveal the client’s identity to that counterparty. The new process would mean that confidential information pertaining to the undisclosed principal – including the full legal name – should be disclosed, but only to credit, legal or compliance areas of the counterparty. A grace period expiring at the end of May 2004 was implemented to allow institutions to change their systems before the new code is enforced.
UK-based trade body the Investment Management Association was instrumental in helping to develop disclosure guidelines. Julie Patterson, director of regulation, operations and tax at IMA, says that the new process should not create a financial burden. “The documentation provides a standard industry basis for disclosed forex trading between managers and banks and will save considerable time and costs,” she says. “The documentation can be used by all banks and fund managers, large or small.”
Implementing the new code has been straightforward, even though it has increased the amount of documentation flowing between fund managers and the banks. “We have always had the procedures in place, so it has not been an onerous task to carry out,” says David Puth, global head of currencies and commodities at JPMorgan. “I would be surprised if anyone has a disinclination to carry it out and so far our clients have responded very favourably.”
Technology has also become a tool of regulation as it installs more transparent transaction methods. “The penetration of technology into every stage of the foreign exchange life cycle has already changed the way people trade and manage risk,” says Mark Warms, chief marketing officer at trading portal FXall. “Technology makes it easier for organizations to ensure best practice by increasing transparency, efficiency and effective risk management.”
As well as providing full audit trails, technology makes it easier to encourage transparency on illiquid instruments. “Electronic trading and reporting makes multiple sources of benchmark data more readily available and provides more accurate information on the timing of trading activity,” says Warms.
The scandals over the past year may have tainted the forex industry but perhaps the cloud hanging over it is not so dark. Given the size of the forex market compared with, say, the equities markets, abuses are rare.
Even without specific rules in place, technology and self-regulation have already gone a long way towards creating rigorous rules. But an in-depth look at abuses in the retail market and the use of points in forex trading is needed.
“It is not a question of developing additional regulation so much as continuously reviewing best-practice standards and using e-FX and other modern means to provide full audit trails, unbiased reference pricing and other tools that provide transparency,” says Eley at Hotspot FXi.



