|
|
| Brunswick Rail | |
| Size | $600 million five-year debut bond issue |
| Bookrunners | Goldman Sachs, Raiffeisen Bank International, UBS, VTB Capital |
| return to the Emerging Europe Deals of the Year index | |
High-grade corporate borrowers also took advantage of strong external conditions to raise substantial chunks of funding at ultra-tight spreads, most notably in the case of Rosneft’s $3 billion dual-tranche market return in late November – but the deal that caught the eye towards the end of the year was October’s more modest $600 million five-year debut from double-B rated issuer Brunswick Rail.
Not only was the transaction one of a relatively small cohort of high-yield Russian bonds to make it to market in 2012, a year in which sub-investment-grade issuance fell to less than a fifth of the total, it was also the first ever from a railcar operating lessor from the country. Still more impressively, for a deal from a new and complex industry, it attracted intense interest from international investors across both the emerging markets and high-yield markets.
In part, the high level of global demand – which enabled Brunswick Rail to tighten pricing by 50 basis points from initial indications to the reoffer yield of 6.5% and increase the deal from the original target of $500 million – was due to the insight of bankers at the four leads that the prevailing strong technicals offered a unique opportunity to look beyond the traditional buyer base for Russian double-B deals.
“Given the significant inflows into dedicated emerging-market and high-yield funds, and the fact that investors were really looking for diversification and for interesting new stories, we felt we could target accounts that perhaps wouldn’t have looked at this name and certainly not in this size a few months earlier,” says Martin Weber, head of debt capital markets for EMEA growth markets and co-head of EMEA investment-grade syndicate at joint bookrunner Goldman Sachs.
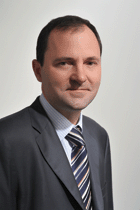 |
| Nicolas Pascault, chief financial officer at Brunswick Rail |
Along with other bankers involved in the process, however, he insists that most of the credit for the deal’s warm reception from global investors belongs to Brunswick Rail’s management team, both for its long-standing commitment to good corporate governance and for its ability to communicate its story. “It’s very rare that you have debut issuers who approach the market with such thorough dedication and preparation,” he says. Andrey Solovyev, global head of DCM at fellow lead VTB Capital, agrees. “The key to the success of this deal, and particularly to bringing in the big US institutional investors, was the quality of the roadshow,” he says. “The team from the issuer side showed excellent commitment and did a very good job of explaining Brunswick Rail’s business model to investors.”
Bankers also cite Brunswick Rail’s realistic approach to pricing – despite attracting a final book in excess of $3 billion – as a factor in the issue’s success in both the primary and secondary markets. According to Nicolas Pascault, chief financial officer at Brunswick Rail, this was an essential part of the company’s overall funding strategy. “The Eurobond market is very attractive for us because it offers long-term, unamortizable, unsecured debt instruments that enable us to optimize our capital structure, maximizing returns for shareholders and freeing up cash for investment while minimizing risks,” he says. “Clearly achieving the right pricing was a focus for us, but as a debut issuer what we wanted above all was to ensure investors were happy with the deal and to build a long-term relationship with them so that we would have market access in the future.”



