 |
 |
The foreign exchange market continues to consolidate, with a growing proportion of customer volume, now 50.43%, conducted by just four banks. That is the headline from the 2013 Euromoney foreign exchange survey results. As recently as 2011, the top-four banks captured just 45.87% of volumes. Last year, they accounted for 48.26% and they continue to capture share even as the size of the market grows.
Total volume reported by the more than 16,000 end-users responding to the latest Euromoney survey, which was conducted between mid January 2013 and mid February 2013 and which asks customers for details of the banks with which they transacted business in 2012, was $225.3 trillion, up by 8% from the $208.5 trillion disclosed in the 2012 survey, which covered business actually done in 2011.
The rise in volumes might come as a surprise. Most FX trading heads were downbeat last year, especially in the second half. Chris Vogelgesang, co-head of foreign exchange at UBS, says: “During the second half of last year FX revenues were impacted by central banks taking action and pumping vast amounts of liquidity into the markets. The aim was to take stress out of the funding markets but by increasing liquidity they reduced volatility in foreign exchange. This had the knock-on effect of tightening spreads and increasing downward pressure on FX volumes and revenues for the banks.”
But maybe it wasn’t such a bad year.
“Volume in the foreign exchange market is driven by end-user demand but also by volume pinging from participant to participant to find liquidity,” says Kevin Rodgers, global head of foreign exchange at Deutsche Bank. “This liquidity-seeking flow, as well as a proportion of end-user flow, is driven by volatility, the higher the volatility the higher the flow. Last year’s lack of volatility damped this secondary flow but primary flow, which the Euromoney survey captures well, was still growing at what we believe is its long-run trend of 5% to 6%.”
What is certain is that, for all of its 450 providers captured in the Euromoney survey, the FX market remains highly concentrated. The executives leading the top banks’ FX businesses duly suggest, as they have almost every year for as long as anyone can remember, that those market forces driving consolidation will continue putting pressure on lower-ranked banks and, they hope, persuade more of them to become more often and in more markets customers of the leading banks rather than competitors.
Low margins on FX business are unlikely to expand any time soon. Indeed both real-money fund managers and leveraged investors, hurting from low returns and low carry in almost every asset class, are increasingly keen to reduce trading costs in all markets including FX. Increasingly banks are delivering the kind of transaction-cost analysis to FX clients, analysing not just bid-offer spreads but movements in price in response to large orders working through the markets, that they did before the financial crisis in the equity markets, when big equity investors realized they had to hone in not just on commissions and bid-offer spreads in their trade costs but also on volume-weighted average price.
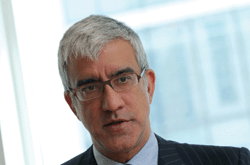 |
| Kevin Rodgers, global head of foreign exchange at Deutsche Bank |
This is all quite cutting edge in FX and it’s costly to deliver. Even low-touch service is expensive to provide at a high level of quality, while returns per ticket are tiny. That leads banks to the search for high volumes, which typically implies a pricing discount, to put across currency-trading platforms that are expensive both to build and maintain.
So while the barriers to entry into the foreign exchange business itself are low, and the high return on equity makes foreign exchange look attractive, given its low RWA-intensity compared with rates, credit or even equity, the barriers to entry to the top end of the business are high indeed and so are the costs of staying there.
For those running the market-leading FX businesses, most of their days are spent not in analysing currency-market risk put on to facilitate customer flow or even in writing sales strategies for new customer acquisition, but rather in the scramble to recruit and deploy the best minds in IT and increasingly to map and negotiate a changing and uncertain regulatory landscape.
The position of the leading flow houses might look enviable, but they are trapped by the IT intensity of the FX business and the urgent need to renew investment just to keep their technology operating, match the pace with competitors designing the latest gee-whiz app or even, they hope, edge ahead with a game-changer of their own.
One says: “Ten years ago, how many banks were genuinely competing to make markets in foreign exchange to a large customer base? At least 40 would have claimed to, perhaps as many as 50. Today, I doubt it’s more than 20 and maybe only 15, if they’re honest. What the apparent fragmentation of the foreign exchange market disguises with its multiplicity of venues, is how much of that apparent liquidity is simply regurgitated from the same few wholesale providers.”
Consumers of league tables, polls and surveys traditionally like to look at top fives and top 10s. The overall league table for FX market share across all markets, types of clients and geographies, no longer lends itself to this kind of analysis. There is no top five. There is a top two, consisting of Deutsche Bank, with 15.18% market share, and Citi, with 14.9%.
Deutsche Bank makes no bones about its intention to lead from the front. Rodgers says: “We’ve said for a decade that our aim is be the number one provider in foreign exchange to every client group, in every product across all geographies. That may sound ambitious because there are certain geographies where others have a natural advantage. But there’s not going to be a market segment in foreign exchange that we’ll write off. We are very strong in derivatives, e-foreign exchange, with leveraged funds and banks. Could we do better with real money? I think we can and we are devoting resources to that. Our corporate business is smaller than Citi’s and HSBC’s but our goal, using our technology and our presence on the ground, for example in Asia, is to compete with them and to catch them up.”
It is Citi though that has done the catching up once again in 2013. It neatly splits leadership of the main customer groups with Deutsche. Citi is the top FX bank for corporates; Deutsche is for banks. Citi wins with real money: Deutsche with hedge funds. But Citi is striding forwards. It has come from fifth with hedge funds in 2012 to second place in 2013 with a $2 trillion increase in its volumes and moved from fourth place for banks up to third.
In the main product categories, Citi has overtaken Deutsche to claim the top spot for market share in spot and forward foreign exchange. In swaps, it has overtaken UBS to finish second only just behind Deutsche and in options Citi is up to third place in 2013 from eighth position in 2012.
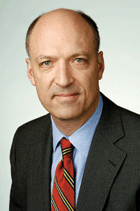 |
| James Bindler, Ceemea forex trading head and global head of FX options at Citi |
“We’ve rebuilt our options business from top to bottom in the past few years,” says James Bindler, Ceemea forex trading head and global head of FX options at Citi, “all the way from the quantitative work behind price production, to price distribution internally and externally through ECNs and other venues. We rebuilt our risk engine, our server farms, so as to be able to process a huge increase in options volume and we rebuilt our customer-facing sales and structuring tool kit. And we’re seeing a big growth in options volume, despite some of the regulatory uncertainty.”
Euromoney’s survey captures an impressive increase in Citi’s options volumes of 23%. Bindler says the bank’s rebuilt options business has helped its sales push in certain key client segments such as to banks. “Our Velocity platform has been highly oriented towards banks as well as investors and especially to large local banks that you might call in-country consolidators, say in Russia, Turkey, South Africa.” It provides a means to disintermediate the provision of credit from the absorption of more FX exposure into Citi’s book. “So if the end client is a corporate, the local banks take the credit risk and the credit spread, while we absorb the pure FX risk.”
Now some way behind Deutsche and Citi in the 2013 foreign exchange survey there is a chasing two in Barclays, with 10.24% overall market share across all client segments, product types and geographies, and UBS, with 10.11%.
Between these four leaders and the next three banks is a big gap. HSBC in fifth place has 6.93% market share, JPMorgan 6.07% and RBS is the last of the top seven, with 5.62%.
 |
| Tim Carrington, global head of currencies and emerging markets at RBS |
“It may be that we are the last bank that can afford the costs of being a full-service foreign exchange service provider on a global basis,” says Tim Carrington, global head of currencies and emerging markets at RBS, who predicts to Euromoney, with unnerving accuracy, precisely the top-two, chasing-two, next-three pattern the 2013 results reveal even before they have been published. “In large part that is because of the cost of regulation, which unfortunately is somewhat fixed and not proportional to your market share or business volume.”
He says that part of RBS’s response has inevitably been to be rigorous on cost. When a colleague points to the frayed elbow of his jacket as perhaps evidence of old-school FX market aggression, Carrington jokes that the suit is government issue. “We are a big corporate bank, powerful in the UK and EMEA and onshore in 20 Asian countries with a significant financial institution footprint. We make our money through genuine product delivery to clients. But we’ve had to be very aggressive on costs. We’re in the top 90th decile in revenues per head.”
Carrington adds: “The top four banks are still capable of tying customers into their single dealer platforms, or attracting those that will check for best execution between four platforms. Those of us in the next chasing three are probably more focused on ECNs, which is the way many more corporates, including SMEs, do their currency business.
“We will provide all the forex services to our corporate customer base and then specialize where we have an edge through trading or sales quality, or geographic footprint. We have a presence in Australia and good research so we’re strong at Aussie dollar for example. We don’t have much of a footprint in Latin America and while we have a capability we won’t mass market that.”
Carrington concludes: “The really interesting question is what happens to those further down the table, especially to those banks increasingly reliant on flows from hedge funds which sometimes have poor years and at other times can be more like competitors than customers.”
“It is not commercially viable to aspire to be all things to all people” agrees Adrian Boehler, global head of institutional FX sales at BNP Paribas, a bank which falls one place in this year’s survey from 11th place to 12th while its volumes climb nearly 4% in a market up by 8% overall.
It is perhaps not surprising that BNP Paribas fallen a place given all the noise around the eurozone last year and eurozone banks, even though BNP Paribas has come through the deleveraging phase in good shape and is now well underway with growth plans in Asia and elsewhere outside the eurozone. But it has had to make choices and segment clients. “We have extensive coverage and relationship management resources dedicated to servicing our target institutional audience, and our challenge is to ensure we are delivering our services in a way that our clients consume them. For us, being wholesale is not about being all things to all people,” says Boehler, “it is about delivering all our expertise to those clients who dovetail well with our strategy and natural advantages. That was behind our decision to rollout our single-dealer platform Cortex last year which was an important missing link in our client proposition.”
 |
| Oliver Jerome, head of FXEM sales in the US and Europe for Morgan Stanley |
At Morgan Stanley, which ranks ninth overall in the survey, the focus is different. “We’ve made a conscious decision in the past three and half years to build a forex business that leads with intellectual content, even in a market place where price remains key,” says Oliver Jerome, head of FXEM sales in the US and Europe for Morgan Stanley.
“There’s a lot to be done both on the execution advisory side for clients seeking to manage trading costs and reduce their foot-print and on the macro advisory side for investors looking for themes and ideas, for example on relative value between the currencies of countries that are trading partners. For investors looking for non-correlated alpha under the umbrella of their overall alternative risk budget, which might be predominantly extended to private equity and real estate, foreign exchange is a very good asset class to consider.”
For all that each bank can articulate its own strategy, there is a clear air of uncertainty around the FX banks. Eric Auld, global head of FX and FX hybrid trading at BNP Paribas, says: “One of the biggest questions we are asking ourselves is how client behaviour evolves as the operating model of the FX business tends more and more towards the equity business model. Whether we get to a fully commission-based business model is open to debate, but the direction of travel towards that state is clear. And as the ‘fees’ that clients pay to their counterparties for conducting their foreign exchange business become more transparent because of that direction of travel, so clients become more rigorous about how they allocate their business to reward the perceived value they receive.”
Clients and regulators might care to ask themselves a different question. How healthy is it for such a large and vitally important global financial market to have 50% of market share concentrated in the hands of just four banks and 30% in the top two?
 |
| Eric Auld, global head of FX and FX hybrid trading at BNP Paribas |
Mike Bagguley, head of foreign exchange and commodities at Barclays, says: “The only question on liquidity in the major currency pairs is how it might be under extreme stress conditions. We looked at this in 2010 when there was a lot of noise around a possible euro break up and asked ourselves what volumes might be in such an event. We basically doubled the capacity of our systems. But it’s a wider question of potential pinch points. Other foreign exchange banks have to be able to perform as well and CLS has to be able to work in step with the banks.”
FX has been a remarkably resilient marketplace, despite being an over-the-counter one with substantial derivatives volumes and trading carried out in many different venues with minimal regulatory reporting. Its key CLS settlement provider withstood the convulsions of 2008 with no problems and so regulators’ gaze has largely been fixed elsewhere, particularly on the structured credit and rates markets.
But remember that of the top-four FX banks, the ones that customers from central banks to hedge funds to corporates together relied on for $113 trillion of FX business last year, Citi and UBS had to be rescued by their home governments in the financial crisis; Deutsche is subject to a number of investigations and Barclays had its chief executive and the leaders of its markets businesses removed by the Bank of England. No wrongdoing has been asserted against any of these banks’ FX operations, but this market has quite a dependency on a small number of bank players. At the very least it’s hard to see how this sits with any regulatory doctrine of too big to fail.
“If you look at the FX options market,” says one banker, “I can tell you that it is so big and it is a market where so many counterparties want to put on big risk transfer trades or at least write bottom-of-the-drawer extreme-event hedges, that no major central bank in the world would want to be a central counterpart to it.”
Now, even at recent low levels of volatility, options in many currency markets still look cheap relative to realized volatility, as it starts to rise. Volume is picking up. “Given how volatility traded in the past 18 months a lot of options volume is restricted to under one-year,” says Todd Sandoz, co-head of global currencies and emerging markets at Credit Suisse. “We are seeing a significant uptick in hedge funds using options strategies to gain leverage on directional views. Yen is a good example of this where we’ve seen a rising interest in structured trades, such as knock-out trades on volatility ranges.”
But interbank liquidity has fallen to a fraction of what it once was, according to many in the FX options business. “You have to ask, says one banker, “if the handful of large bank market makers in FX derivatives could really square this all off between them if volumes spiked in a period of extreme stress?”
And while the issue of the wholesale FX market’s dependence on so few banks casts its shadow, it’s worth noting what the FX banks themselves think of dependency on two dominant suppliers in the market for liquidity venues.
A lot of discussion over the structure of the FX market centres on the proliferation of trading venues, which shows no sign of slowing. It’s a big debate, with banks taking different approaches.
UBS, for example, says it has made a clear decision to invest predominantly in one cross-asset-class single-dealer platform, called Neo. “In a resource-constrained world, the bank chose to build a single, very powerful and efficient platform for internal traders and external clients and to build it once and build it well rather than allow each asset class to continue to develop its own platforms,” says UBS’s global head of FX e-trading, Chris Purves. “Our equities transaction cost analysis algo is on Neo. Did foreign exchange need to build its own from scratch or could it adapt that? Having one domain to deliver all the bank’s research is especially useful for foreign exchange clients who derive macro research from so many other markets. Think of how you search on the internet. Do you use a lot of different search engines or do you just use Google? Bank platforms haven’t adapted like that, yet. But Neo is a big step in that direction.”
Neatly exemplifying the different views in the market, and perhaps the different approaches at different levels of market share in the Euromoney survey, Credit Suisse, which does roughly one-third of UBS’s volumes and has one-third its market share, is taking the opposite approach.
Steve Aldridge, head of global currency and emerging market electronic sales at Credit Suisse, says: “We put a lot of focus on accounts that value our trading insights and views. Clients now put much more thought into not just what trades to put on but how to execute, where and who with. In large part, that is driven by the regulatory environment and the requirements for enhanced transparency, and of course to check for best price. We find clients are increasing their number of execution counterparties, and for those who use prime brokerage services, it’s not uncommon for them to have there or four prime brokers whereas one would have been seen as adequate in the past. Any bank would like to have clients trade solely on their own platform, but we see the market moving to more multi-dealer environments. This is where we are concentrating much of our effort.”
The main bank liquidity providers are hooked up to all of the main trading venues. They have to be. It makes for a highly complex market.
The head of FX sales at another top-10 bank amusingly sums it up like this: “If you were starting from scratch, you would never design a market like the foreign exchange market today. But this is how it has grown up and we have to accept it. And, from a customer point of view, it doesn’t not work.”


