 |
|
|
Best Retail bank for technology innovation: CaixaBank |
|
|
Also shortlisted: NEDBank and Bradesco |
Innovation is crucial for Spain’s banks. The restructuring of the country’s financial system has led to the number of banks falling dramatically. If banks want to compete within a smaller set of larger players, they need to attract customers. “Innovation is the only way to keep growing and improving and being ahead of the competition,” says Benjami Puigdevall, head of electronic channels at CaixaBank. Putting technology at the forefront of growth, CaixaBank launches innovation after innovation. In the past 12 months, the bank has been at the leading edge of technology in retail banking across the world; it wins Euromoney’s inaugural award for best retail bank for technology innovation.
How CaixaBank approaches innovation is telling. The bank relies on innovative ideas coming out of every business group, and from clients and third parties. “We think you have to take into account the knowledge that your internal employees have from dealing with clients,” says Puigdevall. “Then of course listening to the clients themselves and what they need, and finally engaging third parties who don’t come with that inside knowledge, but rather innovation from their views across the industry. That is almost all you need to do and we are convinced that rather than listen to the opinions of just one group, that this way is the way to stay ahead.”
‘Inspiranos’ [inspire us] is one example of how CaixaBank includes its clients in innovation. It is a web-based social platform where clients can post ideas about things they would like CaixaBank to do, and vote and comment on ideas. It’s incredibly simple, but works on two fronts. First, customers feel that their voices and demands are being heard. That alone helps retain clients. Over the 11 months since it launched, 70,000 customers have logged on and submitted more than 800 ideas. Secondly, the forum provides CaixaBank with ideas that keep it ahead in the industry in a very cost-effective manner. The ideas have ranged from the simple to the complex. For example, customers requested smaller-denomination notes in the ATMs and having credit card statements available in Excel to help them with their budgeting. Larger-scale ideas that have emerged from Inspiranos relate to direct debits. The bank is working on a project driven by customer ideas that will monitor bills, highlight any errors and deviations in billing, and provide reporting and storage of direct debits.
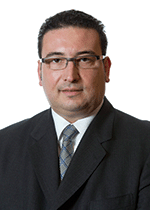 |
| Benjami Puigdevall, head of electronic channels at CaixaBank |
Customers do not just offer ideas; they are invited to work with CaixaBank during the development of an innovation. “With regards to the direct debit project, we invited 25% of the clients that asked for it to join us in meetings and we worked with them to build the screens and functionalities. If you can create something with your clients, you can bet it will be 10 times better than if they weren’t there,” says Puigdevall.
CaixaBank’s engagement of third parties to generate innovative ideas led to the formation of a hackathon – traditionally used by large tech companies and incubators. The bank invited app developers from all over the world to come to the hackathon and brainstorm apps for its clients, offering small monetary awards of €2,000 to five winners. CaixaBank has an online store for retail customers that includes more than 70 apps. “It is a great way of being in contact with people who ordinarily wouldn’t know CaixaBank,” says Puigdevall. “They come from different industries, they are young with fresh ideas, and unlike any ideas we would get from consultants in commercial relationships. If you want to be truly disruptive in this industry, this is the only way,”
The past 12 months have also seen some homegrown developments. Tap is a credit card that is attached to a phone. At the beginning of the year, CaixaBank rolled out the technology for 5,000 customers after piloting the idea two years ago. “We found that clients began to increase the use of their credit cards when it was available on the phone by some 25%,” says Puigdevall. “The convenience of swiping the phone rather than getting out a credit card and waiting to sign off means customers are more likely to use this method now for payments of less than €20, when before they would have chosen to use cash. That is a clear business benefit to CaixaBank as the level of micropayments increases.” More than 40,000 transactions totalling €1 million took place in the four months following the launch.
Finally, for private banking clients, CaixaBank introduced The Wall – a web-based interface that helps them manage their accounts and portfolios, as well as interact directly with their advisers by email or video chat in addition to more traditional means of communication. Last year, the bank also launched its Ready to Buy platform, whereby after meeting with clients, employees can send all documentation via the internet so that customers do not have to keep coming to the branch.



