In the race to profit from the regulatory push for transparency in over-the-counter (OTC) derivatives, electronic trading appears to be in the box seat, offering speed, volume and visibility. However, as European regulators prepare rules for the new trading venues, there is rising concern among banks that their solutions might be disregarded.
In the past year, announcements of new single-dealer platforms (SDPs) include Lloyds’ Arena, RBS’s Marketplace and BNP Paribas’ Cortex, all vying to grab order flow from incumbent operators, such as Deutsche Bank’s Autobahn and Barclays’ BarX.
In a post-financial crisis environment, in which regulators are looking to drag OTC trading into the glare of regulated markets, banks have justifiably bet on a bright future for e-commerce.
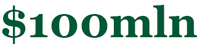
In response to the G20 mandate that all standardized derivatives are traded on exchanges or electronic trading platforms, some 88% of swaps dealers regard technology build-outs as mission critical, according to research firm Tabb Group, with top-tier firms allocating a minimum of $100 million a year to relevant technology budgets.
Mifid catches out banks
 |
|
|
Angela Knight, British Bankers’ Association |
However, when the European Commission in October published its proposals for a review of the Markets in Financial Instruments Directive (Mifid), it appeared the banks had been caught wrong-footed. Rather than mirroring the swap-execution-facility (SEF) blueprint set out in US Dodd-Frank legislation, European regulators proposed a hotchpotch of trading venues, each aimed at different sections of the market. These comprised regulated markets (exchanges), multilateral trading facilities (MTFs – many-to-many electronic trading venues), organized trading facilities (OTFs – offering more discretion on pricing and transparency) and systematic internalizers (restricted to ad hoc large-scale OTC trades).
Before October, most banks assumed they would be able to convert their single-dealer platforms into OTFs, retaining control of the lucrative OTC derivatives business. However, in a serious blow to their aspirations, the October proposals prohibited firms designated as OTFs from using their proprietary capital to fulfil trade orders from clients. The restriction put an end to dealer-platform convertibility, and potentially locked banks out of the new markets in electronic trading of OTC derivatives.
“Top-tier dealers are appalled that regulators have shifted the goalposts and, to all intents and purposes, destroyed a business in which they have invested many tens of millions of dollars,” says Will Rhode, an analyst at Tabb Group.
Given that US regulations prohibit banks from owning SEFs, the OTF model was to some extent the only option for banks to exploit the gold rush for a share of the electronic OTC markets.
Out in the cold
“Dealers view this affair as like watching a bunch of folks having a party through the window of their own house, while they remain locked outside in the cold,” says Rhode.
Of course, nobody in the dealer community is taking the proposals lying down, and since October banks have unleashed a lobbying campaign aimed at persuading the European Commission to change its mind.
“When it comes to single-dealer platforms, it might be that some policymakers have not understood all of the consequences,” says Serge Marston, head of e-commerce sales at Deutsche Bank. “The platforms are a way for banks to differentiate themselves, so, depending on how the regulations play out, we will need to adjust.”
Lobbying efforts involve trying to persuade the EC to amend the definition of proprietary capital, perhaps recognizing capital as facilitatory rather than proprietary, and allowing banks to use a separate entity for trading, which would be capitalized by the bank and would then feed funds into any trade, as if it were a client.
The International Swaps and Derivatives Association (Isda) – in its response earlier this month to a questionnaire sent out by German MEP Markus Ferber, official rapporteur for the Mifid review – made plain its unease with the OTF proposals and their potential impact on single-dealer platforms.
In particular, the proposals, if agreed, would sharply reduce levels of liquidity available to clients on OTFs, it said. For example, there might at any time arise a disconnect between what clients wish to sell and what they wish to buy, which without the availability of dealer capital to bridge the gap could cut clients’ ability to trade large sizes quickly and at low cost.
“The proposed ban will have the impact of restricting the range of available venues for trading in OTC derivatives subject to the trading obligation, notably limiting the role played by single-dealer platforms,” said Isda.
Angela Knight, chief executive of the British Bankers’ Association, also expressed dismay at the proposed OTF restrictions. “Strict separation of capacity between dealers and OTFs would make it much more difficult, slower and more costly for investors to obtain execution, and could therefore ultimately result in harm to end-users,” she says. “No single provider could ever guarantee to provide a complete service on any one platform.”
One area in which single-dealer platforms would still be able to thrive is where Mifid provides an exemption to the requirement that derivatives be traded on SEFs and are centrally cleared. That might be either where a large trade is contemplated, as is common in the sovereign debt markets, or where an instrument is traded on non-standard terms. The market awaits definitions on both.
Incremental effect
In the US, where banks will be restricted in trading on their own accounts by the so-called Volcker rule, policymakers in recent days moved to offset investor fears over the potential impact on liquidity. US Federal Reserve governor Daniel Tarullo told a House financial services committee that the rule “probably” will have “some incremental effect on liquidity in some markets at the margin”.
The Fed’s moves came after a study by consultancy Oliver Wyman for the Securities Industry and Financial Markets Association, saying investors in US corporate bonds could suffer a $315 billion loss as a result of the Volcker rule’s impact on liquidity.
As the European authorities consider their options, dealers are wasting no time in pressing their case. “If the client is getting best execution, then there is no reason why single-dealer platforms should not play a role,” says a senior banker in e-commerce at a bank in London. “Dealers provide tremendous amounts of liquidity and there is a lot of lobbying going on to make sure they do not end up getting cut out.”
 |
|
|
top-tier firms’ minimum allocation to technology budgets |
Another approach might be to connect single-dealer platforms to existing OTFs through a web portal, with the single-dealer platform acting as a conduit to OTF pricing, and charging a broker fee for the service. Alternatively, dealers might set up virtual OTF aggregation services, pooling liquidity from an array of platforms into one location. If that idea gains traction, banks might enrich their offering by bundling in various other services, such as collateral management, portfolio research and counterparty risk analytics. This approach of building screen real estate, prioritizes creating value and generating fees out of pre-trade price discovery and post-trade services.
“The priority for banks is that they enhance their relationship with the customer, and that their single-dealer platforms act as the channel through which clients access liquidity,” says Paul Blank, director of e-trading solutions at platform-provider Caplin Systems. “That might be from the bank directly, or with the bank using aggregation and smart solutions to route the trade in the most appropriate manner.”
As the debate over single-dealer platforms plays out, banks are left in one of two categories – those that have multi-asset-class platforms up and running, such as Morgan Stanley and Deutsche Bank, and those late in the game or just about to launch systems, such as HSBC.
“Incumbents must rethink strategies and look at where revenues are going to come from, but for those that are late, it’s a tough decision,” says Fred Ponzo, founder and managing partner of consultant GreySpark Partners. “Either they build against the former or current paradigm, and potentially get it wrong, or they wait and see how the regulation and new business model play out, and risk missing the boat altogether.”



