Nigeria’s currency is dangerously exposed in the run-up to a presidential election in April that might prompt destabilizing inter-communal violence. With oil prices rising way above those projected in the government’s budget, money should have accrued over the past year into an Excess Crude Account (ECA) – if the fund had been used as intended when it was set up in 2004.
The ECA could have given the nation’s budget a cash buffer to protect against a dip in the price of Nigerian oil, now over $100 a barrel. But from a peak of $20 billion three years ago, the account fell to just over $300 million at the end of last year, according to Standard Chartered. Total foreign currency reserves at the central bank, including the ECA, were barely above $34 billion as Euromoney went to press, down from $42 billion in February 2010.
In the oil industry – the source of almost 80% of government revenue – leaving aside price increases, production was higher than in previous years in 2010 thanks to an amnesty with Niger Delta militants. Nigerian domestic government borrowing also went up 40% in 2010.
At the same time, a monetary policy rate of less than 7% in a year of 14% inflation forced the central bank to sell reserves to support the naira at the preferred rate of 150 to the dollar. In late January this year central bank governor Lamido Sanusi raised the base rate for the second time since assuming office in 2009, to 6.5%. London brokerage Exotix reckons the central bank can sell only between $7 billion and $8 billion more of the reserves before devaluation is necessary.
There is a widespread perception that the government’s use of funds from the ECA was, in the words of Standard Chartered, “symptomatic of the background lobbying” running up to the presidential primaries in January. President Goodluck Jonathan’s successful nomination by the dominant People’s Democratic Party was widely predicted, as was his victory in the election itself, partly thanks to a political system particularly known for the patrimonial advantages wielded by incumbents.
According to the IMF, actual consolidated government spending in Nigeria increased 37% last year, after a 10% rise in 2009. A supplementary budget with a public-sector wage settlement meant a 50% backdated increase in civil servants’ pay. But the biggest area of increase was in overheads and other recurring expenditure, where outflows from ministries and other government departments and agencies is relatively difficult to trace, until the auditor general reports later this year.
 |
|
|
“Insufficient infrastructure is Nigeria’s biggest barrier to increased productivity and GDP growth” Olusegun Aganga |
In an interview in the capital, Abuja, finance minister Olusegun Aganga tells Euromoney the government can account for everything that went in and out of the ECA. He concedes that the actual oil price in 2010 was $21 higher than the budgeted price. Nevertheless, he says, this does not mean that the ECA should have received an increase of $21 times the 750 million barrels sold (so $16 billion). He says this is partly because the Nigerian National Petroleum Corporation (NNPC) has production costs, although one international financier familiar with the situation says these cash calls were not exceptionally high in 2010.
The global economic crisis meant reduced remittances and foreign direct investment to Nigeria, says Aganga. Investment in the economy was hit too by a crisis in the local banking sector and stock market. “Go ask Obama why he had an expansionary budget […]. This country decided to have an economic stimulus, and there was a rational reason for that,” he says.
On the basis of a $65 a barrel oil price, the 2011 budget, which the government hopes to implement in the spring, targets a 22% reduction in spending compared with last year. This is partly to reduce borrowing and partly because some states in the federation have not been able to spend the 2010 money.
The government’s fiscal deficit will drop to below 4% in 2011. But as Aganga himself recognizes, the 2010 deficit of just over 6% of GDP has been funded primarily from savings, from the Excess Crude Account.
New fund, new Nigeria?
Little wonder, then, that Aganga describes a new, more robust savings mechanism as “a major initiative of the government”. Unlike the ECA, this new fund is to be for profit, and protected from government interference, in line with the 2008 Santiago Principles on transparency, independence and accountability by sovereign wealth funds.
Aganga says it is his ministry’s “aspiration and plan” to have final legislative approval for the scheme before the end of this administration. In July, he set aside $1 billion from the ECA to be used as seed capital for the new institution. “The former Chilean finance minister [Andres Velasco], who was responsible for setting up the Chilean sovereign wealth fund, is one of our advisers,” says Aganga. JPMorgan and US law firm Latham and Watkins are advising too. The fund is to be split into three parts. One will be set aside for future generations. The next will invest in cash or near cash, augmenting the budget only “when there is a sustained fall in the oil price,” as Aganga says. The third part will invest in Nigerian infrastructure projects.
In the bill before legislators, each of the fund’s three parts will have a minimum 20% allocation from the overall inflow. A fund manager “will then have the discretion to allocate the remaining 40%,” says Aganga.
Once the fund is up and running, Aganga’s intention is that everything that used to go to the ECA – any government oil revenue accrued as a result of higher than budgeted oil prices – will go into the new fund. The minister says he has already spoken to people outside government who might run the fund. Although he says external fund managers would also be used, in-house staff would include a chief executive or chief investment officer, a risk officer, and an operations head.
What has been called the Nigerian Sovereign Investment Authority will improve on the deficiencies of the ECA, according to Aganga. This means a legal foundation, and much clearer guidelines for accessing the fund. In addition, the money will, he says, be “put to work”, in local infrastructure projects and for long-term returns.
Aganga says the lack of legal backing was at the root of many of the ECA’s problems. In its original form, the ECA was supposed to be accessed only if actual oil receipts fell below the budgeted amounts. But unlike the new fund, which will be inscribed in law, the ECA was based on a memorandum of understanding between the federal, state, and local governments.
After the ECA was established, some of the state governments – referring to constitutional rules guaranteeing shared oil revenue between the three tiers of government – filed suits to claim their right to manage the 27% of the ECA set aside for the states (another 21% is set aside for local government). “Some of the state governments actually saw the ECA as their money, that there’s no justification for holding that account,” says Aganga.
As a result, in 2007, another memorandum of understanding was signed, formalizing extraordinary allocations, and permitting 80% of oil savings accrued to the ECA in one year to be available to spend the following year, regardless of the oil price.
In the bill for the new sovereign wealth fund, the argument has been put forward to the various levels of government that the money will still be shared, but at a later date – and that the constitution allows the National Assembly to provide for saving and investment. An official pamphlet on the fund points out that the constitution enjoins central government to harness national resources for national prosperity, and to create bodies to plan and foster economic development.
“We wanted something that has constitutional backing,” says Aganga. He even indicates that if the National Assembly were to reject the bill on constitutional grounds, the constitution could be changed, although he doubts that this will be necessary.
Late last year, the fund was approved by the Federal Executive Council (the cabinet), as well as by the National Economic Council, which includes all 36 state governors. The state governors will furthermore be part of the fund’s governing council, alongside the president, federal ministers and representatives of private businesses.
The governing council will provide oversight to a management board, which will consist of four executive and five nonexecutive directors. The governors’ presence in the council will, it is hoped, make more obvious the states’ stake in the fund’s success.
Under lock and key
In addition to the ECA’s constitutional difficulties, Aganga says the mechanism for access to it is too ad hoc. “Today it is just subject to the [state] governors, the National Economic Council, making a case for it. We look at the balance, we look at the case and all that, and a decision is made,” he says.
In the new fund, says Aganga, “there will be no access at all to the savings box”. He expects this part (for Nigerians not yet born) “will have a longer-term horizon, and will be able to invest in fixed-income securities and equities”.
The official pamphlet states that the budget stabilization part of the fund will be only a “last-resort source of financing” for the government. “The only part that will be available [to the government budget] will be the stabilization part, and the prudential guidelines […] will make it very clear when it can be accessed, and how much can be accessed,” says Aganga. He says that in the discussions access to a defined amount of funds would be conditional, precisely, on a sustained fall in oil price over three or four months.
Asked whether there would be circumstances when governments could tap the new fund without a sustained fall in the oil price, Aganga reiterates that is not what is proposed. But he admits that “anything can change” at this stage of the legislative process. The National Assembly committee must still go through the plan, and invite input from interested parties, he says. So there is still the possibility of adding amendments, and exceptions for extraordinary circumstances.
He says: “[The representatives] know why we are doing this. […] People should have the right to express their view on what they think should be there. But at the end of the day I think we will get something close to what we are looking for.”
As to the possibility of increasing the oil price taken account of in the budget, Euromoney asks whether his ministry could also set a limit to federal government spending funded by revenues from exports of natural resources, as in Chile and elsewhere. Aganga says an Expenditure Review Committee was formed in September. This, he says, is looking at “recurrent expenditure, at how we restructure it and how we fund it.” He says “we’re looking at ways to strengthen” the method of calculating the budgeted oil price.
Over the longer term, Aganga indicates that further scope for savings, and for investment in infrastructure, might result from the Petroleum Industry Bill, now also under debate in the National Assembly. Among this bill’s many elements are measures to encourage more private investment in domestic refining and fuel distribution.
There are proposals to open access to petroleum transport facilities, and for reductions in, and eventually the elimination of, subsidies and price controls on fuel. As locally refined oil provides only 15% of national fuel at present, this is vital for government savings. One of the main destinations of ECA funding has been the roughly $4 billion spent annually on subsidized imports of petroleum products.
The petroleum bill also aims to create a new, profit-driven national oil company, more in line with Brazil’s Petrobras than the existing NNPC (a state dinosaur, as one banker describes it). The new company would finance itself through cashflow and borrowing, eliminating the cash calls to the government that Aganga refers to.
Candle of hope
Whatever the National Assembly decides, it is hoped that the plan for a sovereign wealth fund is another example of progress in Nigeria. Alongside reforms in banking, and now reforms in electricity and oil production, it adds to changes made in the past decade such as the clearing of London Club debt or, indeed, the establishment of the ECA (for all its deficiencies).
 |
|
|
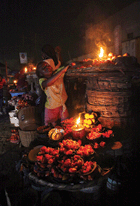
Lagos market traders selling by kerosene lantern light: low electricity-generation capacity is hampering Nigeria’s economic development |
To whatever extent the new fund follows the spirit as well as the letter of the proposed law, it certainly appears likely to lead to more government saving. At the very least it might ensure more capital expenditure rather than recurrent expenditure, and, via the profit motive, it might make this capital expenditure more efficient too.
Insufficient infrastructure, says Aganga, is Nigeria’s “biggest barrier to increased productivity and GDP growth”. Above all, low electricity-generation capacity is often cited as the main factor blocking faster industrialization. Nigeria as a whole is said to enjoy as much grid power as the area around Tokyo’s Narita airport, a situation blamed for Nigeria’s tiny manufacturing sector, just 4% of GDP.
The government is working with the World Bank and others to draw $3.5 billion annually into electricity developments, partly by providing off-take guarantees. The state power utility Power Holding Company of Nigeria (PHCN – mockingly dubbed by Nigerians “Please Have Candle Nearby”) is privatizing its generation and distribution assets. This has already attracted interest from Goldman Sachs and General Electric in the US, as well as investors from China, India and elsewhere.
“In the past, as a government, we have tried to address [the infrastructure deficit] through budgetary allocation. But no country anywhere in the world has enough resources to address its developmental needs by relying on the budget,” says Aganga.
The minimum 20% infrastructure allocation in the new fund is therefore crucial in resolving what Aganga sees as the other shortcoming of the ECA: that the money was not “put to use”.
Aganga says the government and a recently formed Infrastructure Concession Regulatory Commission are focusing on 50 infrastructure projects, above all in power and transport. Of these 50 there will be projects funded directly through the budget, where, as he says, “in some cases we will have to provide counterparty funding”. In addition, “for those projects which are not commercially viable on a standalone basis” he says there is a provision in this year’s budget for N50 billion ($326.7 million) for “viability-gap funding” to ensure that the projects can go ahead on a for-profit basis, in a public-private partnership led by the private sector.
Finally, there will be those projects “led and funded” by the private sector, but without any direct state budget involvement. In these projects, explains Aganga, the new sovereign wealth fund will co-invest on a for-profit basis with local and international investors, and with other sovereign wealth funds.
“Although the projects will be run by the private sector, apart from the fact the sovereign wealth fund provides capital, it will provide a lot of comfort for international investors to co-invest with the government,” he says. There have already been expressions of interest and discussions with other sovereign wealth funds keen to co-invest with the Nigerian fund in such projects, says Aganga.
He says part of the management of the fund’s infrastructure portion could also be outsourced, perhaps to local or international managers already managing infrastructure funds in the region.
Nigeria’s decade?
Electricity generation reforms will have to contend with lobbyists, for example, from the multi-billion-dollar home-generator industry. Unpopular tariff rises for consumers of fuel and electricity are necessary to make power and refining projects commercially viable, and they are a potential spark for civil unrest. Trade unions will equally vehemently resist lay-offs as a result of privatization.
The sovereign wealth fund will have to negotiate with other vested interests, too, and it might be co-opted. A subsequent administration might be less committed to the scheme, particularly before an election. But as more Nigerian entities tap international capital markets, both inside and outside government there appears to be greater appreciation (if sometimes grudging) that Nigeria’s economic prosperity depends on perceptions of its sovereign risk, on the country’s ability to attract more investment, both at home and from abroad.
“This is desirable and good for the country. Regardless of the political party, I think everyone accepts that,” says Aganga of the fund.
The minister is a man with little previous experience of government. Just a year ago, he was a managing director at Goldman Sachs in London, doing client coverage for Nigeria, and European prime brokerage. President Jonathan recruited him in April, after former president Umaru Yar’Adua passed away. With the federation’s $500 million inaugural international sovereign bond issued in January, if Aganga succeeds in establishing the sovereign investment authority as planned it could be an impressive year for the former banker – despite the continued depletion of the ECA.
Indeed, especially because of what has happened with the ECA, and perhaps partly because of the extra monitoring associated with the international bond, the establishment of the Nigerian Sovereign Investment Authority might be a good, maybe even critical start to what US development economist Jeffrey Sachs recently told Aganga would be “Nigeria’s decade”. Nigeria, Africa and the world will be watching the fund’s fortunes, and hoping the economist is right.



