US insurer AIG has agreed to sell its Taiwan unit, Nan Shan, to Ruen Chen Investment Holding, part of the Ruentex Group, for $2.16 billion. If it is successful, the deal, which is still awaiting final regulatory approval, will signal the end of AIG’s sale of its Asian assets and the conclusion of the long-running attempt to dispose of Nan Shan.
It will also come as a blow to ex-Citi banker Bob Morse, whose new financial services group, Primus Financial Holdings, was rebuffed by regulators after apparently securing Nan Shan in an earlier bid for the business in August. Primus was again a bidder on this most recent auction, this time with a new consortium after the previous bid together with China Strategic Holdings failed when regulators cited concerns about the group’s ability to fund the acquisition and long-term commitment to the business. Sources close to the deal also say that regulators were concerned about the possibility of mainland Chinese money being involved in the bid, something that is politically controversial in Taiwan.
Victor
The victorious Ruentex Group is perhaps not generally as well known outside Taiwan as rival bidders for Nan Shan, such as Cathay Financial and Fubon Financial, but it is one of the largest business empires in the country, with more than 150,000 employees and interests, including medical services, food, construction and real estate, and finance. The group has little prior business in the life insurance sector but chairman Samuel Yin – whose family founded Ruentex – was a co-founder of Antai Life Insurance, a business eventually sold to ING, which in turn sold to Fubon.
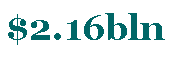 |
|
|
price Ruentex is paying for Nan Shan, a price to book ratio of under 40% |
The deal looks like a real coup for Yin in purely financial terms. The price of $2.16 billion is barely more than the $2.15 billion that the Primus-led consortium agreed to pay for Nan Shan back in October 2009, following months of persistent lobbying and negotiation from Morse. Since then global markets and the Taiwanese economy have recovered, so Ruentex Group will be pleased to be paying the late 2009 price for Nan Shan – especially since a letter filed with the SEC reveals that AIG received a bid as high as $3 billion for the asset. The deal represents a price to book ratio of just below 40%, making it – according to Bloomberg data – the second cheapest among all life insurance companies valued at more than $2 billion. The low price, says a source close to the deal who did not wish to be identified, might reflect the urgency with which AIG wished to conclude a deal. The US insurer is under pressure to repay its $180 billion-plus bailout from the US government, and the source says that following the year-long saga and ultimate failure of the initial Primus bid it was looking “with this auction for certainty of execution, speed of transaction and price – in that order.”
Ruentex’s lack of involvement in the life insurance sector before the acquisition might have helped its bid in as much as it would have eased concerns over antitrust rulings in comparison with bids from Fubon and Cathay, both of which have a substantial presence in the sector already. All bidders, however, were most concerned with satisfying the five principles set out by the regulator as necessary qualities for a bidder to be approved. These were: ability to fund the deal; long-term commitment to the business and the sector; management’s ability to run a life insurance company; willingness to look after the interests of Nan Shan employees and policy holders; and the source of the funds for the deal. The last of these might refer to uneasiness over the possibility of mainland Chinese funds being involved in any acquisition of a big asset in Taiwan.
 |
|
|
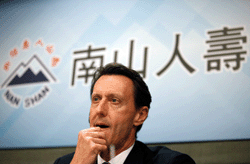
Robert Morse, Primus: lost out on Nan Shan after a long but fruitless pursuit |
For Morse’s Primus Group, the future is less certain now that the Nan Shan bid has failed. Morse told Euromoney shortly after the launch of his new group in 2009 that he planned a “string of pearls” approach to acquisitions in Asia across wholesale banking, insurance and asset management (see Primus Financial Holdings: Morse signals grand plans for post-Citi bank, Euromoney, June 2009).
Buying Nan Shan would have provided the platform for the insurance business to develop, and without it Morse and colleagues will have to return to the drawing board. It is a disappointment after he had invested so much time and energy in cultivating the Taiwanese regulators, securing partners for the bid and battling against accusations that China Strategic was a front for mainland money. A former colleague, however, says that this is by no means fatal for Primus. “Bob is a fighter with more than 20 years’ experience in the region, and an impressive array of contacts,” he says. “He’ll be disappointed, but he’ll dust himself off and carry on.”
When called by Euromoney Morse said that he did not wish to comment.
see also:
Beijing fears threaten Taiwan insurance takeover, Euromoney, April 2010



