Brazil’s private equity industry is attracting growing interest from international and local funds, with infrastructure heading the list of investment opportunities.
“I have had several fund managers tell me that even though fund-raising is very hard in the US and other emerging markets, investors want to get into Latin America. They particularly want exposure to Brazil,” says Cate Ambrose, president of the Latin America Venture Capital and Private Equity Association.
In a sign of the level of interest from foreign investors to the region, Advent, one of the world’s biggest private equity firms, is likely to announce that it has raised a $1.5 billion Latin America fund. The fund comes on the back of news that another global firm, Carlyle Group, plans to invest $1.2 billion in Brazil in the next five years.
In another move, the Brazilian Venture Capital and Private Equity Association (ABVCAP), and Apex, the Brazilian export bank, signed a joint venture agreement a few months ago that aims to increase the number of foreign investors coming into Brazilian private equity funds.
Low rates
Local investors are also showing greater enthusiasm for the asset class. With Brazil’s benchmark Selic rate at a record low of 8.75%, locals are eyeing opportunities beyond the bond market and are increasing their allocations to alternative investments.
“We are actually finding local investors are more receptive to private equity than international investors. International investors like Brazil and have it as a priority when they come back to the market but many are still licking their wounds after the crisis,” says Sidney Chameh, founder of DGInvestimentos and president of ABVCAP. “I think institutional investors will come in strong by the end of 2010, but the local investors are already making big commitments this year.”
Brazil has abundant investment opportunities. Renewable and alternative energy continue to feature highly in some investment portfolios, as do retail and education.
Another two sectors that are appearing on investors’ radar screens are energy and infrastructure. Since Petrobras announced in 2008 that it had found a new oil deposit that could contain more than 33 million barrels of oil, several more finds have emerged. Oil exploration potential offshore Brazil is a huge opportunity. Axxon Group, based in Rio de Janeiro, is one fund considering investments in firms that supply oil.
The push into infrastructure stems from two main sources. First, in 2007 the government launched its growth acceleration programme (PAC), which has a focus on developing Brazil’s infrastructure backbone. This plan has already funded several infrastructure projects worth hundreds of million of reais.
In recent months Brazil’s infrastructure spending needs have stepped up to another level thanks to successful bids to host the 2014 World Cup and the 2016 Olympics. Brazil’s need for hotels, stadiums, airports and supportive transport routes just scratch the surface of coming infrastructure demand. Grupo Santander Brasil and San Francisco-based Paul Capital Partners have made public their intention to invest in companies that will benefit from Brazil hosting these sporting events.
Opportunities
“There’s a lot of talk about the World Cup and the Olympics but talk hasn’t yet converted into real investable opportunities. There will be opportunities soon though. There are a lot of entrepreneurs wanting to line up and be involved in providing infrastructure for these events,” says Fernando Gentil, head of Brazil for Darby Overseas Investments.
|
|
|
|
estimated investment in Brazil’s infrastructure over the next three years |
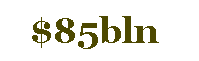
Some estimate that up to $85 billion will need to be spent on Brazilian infrastructure in the next three years. Economists predict that the economy will grow by 5.5% to 6.5% for the next two years as a result.
Some macroeconomic concerns are emerging, however. The Ipca consumer price index rose 4.83% in the 12 months to February, above the government’s official year-end target of 4.5%.
There are also operational issues that private equity firms must contend with. Brazil is notorious for red tape. “The bankruptcy law improved a couple of years ago, meaning you can recover assets more quickly but there are still big issues with red tape in this country, says Chameh. “Legislators are trying to improve this situation but it is time consuming and expensive to open a company here still.” Obtaining environmental or operational licences is reckoned to be a notoriously slow process.
|
|
“There has never been any tradition of project financing here. Brazil’s past inflationary issues mean that long-term financing is only developing now” Fernando Gentil, Darby Overseas Investments |
The tax environment is also a deterrent for some private equity fund managers. High taxes within a complex system make opening a company in Brazil relatively expensive. Ambrose notes, however, that changes to specific legislation give foreign investors a tax opening where capital gains tax is removed for investors that will have to pay the tax in their home market.
Infrastructure projects have financing issues to overcome as well.
No tradition
“There is still a lack of classic project finance where lenders take on a portion of the project’s risk rather than taking on corporate risk. Banks would probably grow in this area if there were more performance guarantees and more insurance for construction risk and performance risk – you have them internationally but not here. This also makes infrastructure financing a little more cumbersome than it could be or should be,” says Gentil. “There has never been any tradition of project financing here. Brazil’s past inflationary issues mean that long-term financing is only developing now. Private banks still tend to request all sorts of guarantees and collateral from the sponsors, which limits the flexibility and the amount of financing that projects can get.”
Exit strategies are also a point of discussion for private equity investors. “Brazil has a lot of enterprises and small companies and so we are facing a consolidation movement that will push M&A activity this year,” says Chameh. “Private equity companies [that are trying to rapidly grow their investments] are driving some of this consolidation but higher M&A activity also provides funds with a good exit route.”
Equity listings are another exit option although after 67 IPOs in 2007, the equity market has been much quieter in the past 18 months.




