 |
|
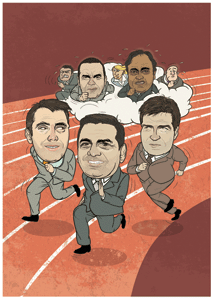
Front (l–r): Fabian Shey (UBS), Zar Amrolia (Deutsche) and Ivan Ritossa (Barclays). Back (l–r): Martin Wiedmann (Credit Suisse) and Anil Prasad (Citi) |
THE MOVE TOWARDS foreign exchange markets becoming fully electronic is set to accelerate as global banks strive to create huge liquidity pools to boost revenue growth. It is a popular strategy in an asset class that offers banks, in capital terms at least, the biggest bang for their buck, but in the short term the ensuing price war could stunt future earnings. Yet it needn’t be that way – for those banks that can gather the biggest pools and then use the information flows effectively, the currency business could become the jewel in their global markets crown. In 2009, banks were always going to struggle to repeat the record revenues of the previous year when market dislocation, reduced liquidity and wider spreads proved to be a boon for the major players. In FX, as in most markets, 2009 was about normalization of conditions. Although liquidity was back, deal volume across almost all main market makers fell, as this year’s survey shows. For the top 10 banks, volumes fell 7.5%, to $129.2 trillion, while total volumes fell 4.5%, to $167.4 trillion. According to a confidential FX study conducted by a prominent management consultant, seen by Euromoney, revenues were down 35% across the industry in G10 currency markets, while emerging market currencies helped cushion some of that drop, with revenues gaining 5%. The overall drop has been viewed as a blip, given the traumatic events of 2008.
Instead, the focus in foreign exchange markets today is on a new wave of business development, as banks go about building and enhancing robust electronic trading and risk platforms to attract an ever-increasing customer base, while also in most cases connecting to a one-stop-shop electronic platform across all asset classes. Multi-dealer trading venues, commonly referred to as electronic communication networks (ECNs), formed the second phase of the electronic revolution, after Reuters and EBS kicked it off as electronic interdealer brokers in the mid-1990s. But a third phase is now opening up where banks look to lure larger concentrations of liquidity based on tight pricing and then seek to monetize these flows using sophisticated risk management technology.
As Ian O’Flaherty, Deutsche Bank’s head of e-commerce, points out: “Clients have access to more electronic venues than they ever have before, they don’t have to deal with just the banks. Yet most of those external marketplaces price to four decimal places, while most banks are now pricing to five decimal places.” O’Flaherty believes that, by providing dedicated liquidity to clients, the better pricing of a single-dealer platform now has real value. He adds that it is still the case that only banks provide dedicated liquidity full time.
Thus, banks are throwing their resources into developing their own platforms designed to suck up ever-larger pools of liquidity. The bigger the pool, the greater the information flow, the greater the ability to take more informed bets and, most importantly, to match customer spread business 24 hours a day. This is the new paradigm in foreign exchange and almost everyone wants a piece of the action. It is set to unleash fierce competition, raising the question of who will win and whether anyone can make money from it.
Share and share alike
One of the most interesting results from this year’s survey is the wider dispersion of market share among participants. The top three banks’ market share fell to 54.6% from 61.5%, while the share for the top 10 fell much less, from 79% to 77.19%. It is an indicator that liquidity has returned for some of the next-tier franchises but, as anecdotal evidence also suggests, a sign that more and more of them are buying market share. Of the top-five banks, only Barclays Capital and Citi increased their market share, albeit by less than one percentage point. However, Barclays further consolidated its third position by gaining its highest-ever share of the market with 11%, pulling away from the fourth spot, now held by Citi, which has leapfrogged Royal Bank of Scotland.
The common denominator here is a well-established presence in e-commerce trading, where Deutsche Bank with its Autobahn platform and Barclays with Barx have stolen a march on their rivals, numerous investors tell Euromoney. Deutsche’s prominence in the FX survey in recent years is reflective of its development efforts over more than a decade, while Barclays appears to be catching up. UBS, once considered to have the most state-of-the-art platform, has experienced the largest erosion of market share, while still holding on to its second-place ranking. Views on its electronic platform are mixed among buy-side FX professionals.
“One of the things that is making a few banks stand out at the moment is the real commitment to technology,” says the head of a large London-based FX hedge fund. “Barx and Autobahn are the top platforms out there because they have simple functional pricing and sound risk management platforms.” According to technology research firm Celent, at the end of 2009 electronic trading made up 55% of total flows, and that is forecast to grow to around 75% by the end of 2012. It is difficult to say what an optimal overall market share will be as adoption continues, although Deutsche Bank’s slippage from almost 21% to 18% suggests that further gains will be harder to earn.
“If we dial the clock back five years, in any capital markets business 8% to 10% market share was pretty good – whether it was league tables, whether it was primary dealership in the US, people aspired to that,” says Nick Howard, Barclays Capital’s global head of FX and emerging markets distribution. “Now we’ve redrawn the rule book. The ideal market share probably isn’t 40% but it’s certainly north of 15%, and we’re definitely not at the point where we think our market share is costing us money. We’re drawing the line at a minimum 15%.”
The inside story
The buzzword in the world of single-dealer platforms is internalization. This means the bank assumes the risk of the trade and then uses its client liquidity pool on the platform to match the position. On a dominant platform, market makers begin to resemble mini-exchanges, where buyers and sellers are automatically matched off. But there is a distinct difference – unlike exchanges, FX market makers also warehouse risk because not all trades can be matched off at the same time, and importantly they guarantee liquidity at all times.
“We have no goals to achieve 100% internalization because it’s highly unlikely that you’ll make any money from that,” says Deutsche’s global head of foreign exchange, Zar Amrolia. “We’re looking for the optimal point, whereby we internalize flow that we feel confident can be offset by our clients, internal traders, or where we benefit from favourable market moves, or we externalize flow into the general marketplace with low offset value, or be subject to adverse market moves.”
Both Barclays and Deutsche Bank have continued to enhance their e-commerce platforms with added functionality, such as smart electronic order books that integrate order flows from clients with those of their internal risk-takers. This month Deutsche launched a new order service called “inside fill”, which gives clients access to prices inside the market bid-offer spread. For example, if a customer places an order to sell euro-dollar at 1.3435 when the market is quoted at 1.3432/37, a Deutsche trader looking to buy at 1.3437 has an interest to buy at 1.3435 from the customer. Barclays claims to have beaten Deutsche to the punch, however, launching Powerfill Plus last August. It allows clients to match orders with other clients, or trade within the market spread as well. It is a compelling proposition – the whole idea of a liquidity pool becomes self-fulfilling because incentives are aligned, so customers are compelled to keep trading within the internal pool rather than externally. Deutsche’s O’Flaherty admits that it doesn’t suit all execution styles, but Barclays estimates that 25% of its turnover is now generated by its order book.
UBS’s retention of second place this year suggests resilience in its FX franchise, especially given that it is in the process of rolling out a new version of its FX Traderplus platform, once considered the prototype for FX e-commerce. New features will include increased functionality such as client-based algorithm trading and live streaming option prices, says Fabian Shey, global head of FICC distribution. UBS plans to bring all its e-commerce platforms together as a more integrated solution, which Shey believes will increase volumes because a percentage of UBS’s fixed-income clients do not at present use the bank for FX.
One FX hedge fund manager says the process has been muddled. He recalls having lunch with UBS and being told the new version’s release was imminent, only to receive a phone call a few weeks later to say it was not ready. A few days later, while attending an FX investor conference, he found UBS offering demos of the platform, using a slave screen, because it was still not ready.
 |
|
|
“If you can consolidate all that FX flow information, provided you have the right market share and access to liquidity, you will be even more profitable” Anil Prasad, Citi |
“You have to ask yourself, why are you doing that when it’s not ready? People were giggling about it,” says the hedge fund manager. Another buy-side professional says that of the FX investors he knows or speaks to, more have pulled their lines because of poor pricing than haven’t. He cites an example where UBS quoted sterling with a 30-pip bid-offer spread over the recent announcement from the Monetary Policy Committee, which one would normally expect to be wider around the time of such a key announcement. However since a general election had been announced the MPC had made it clear that policy would remain unchanged for that month. Still, UBS decided there were risks to the tune of a 30-pip spread for 10 minutes, which is effectively saying they have no interest in this market, remarks the investor. He adds: “In this market you can’t be 30 pips wide for 10 minutes, because people will switch off the machine and go elsewhere.” If the price is right
For the majority of the market though, the race to gain critical mass has led to an obsession with pricing to lure clients on to their platforms. But some investors say that a market maker’s willingness to price to five decimal places is almost irrelevant. “They all brag that they have the best price but it’s a misnomer,” says another London-based hedge fund manager. “Frankly, if I sell at 1.12232 instead of 1.1223, it’s going to make little difference to my returns at the end of the year.”
Of the FX investors who spoke to Euromoney, almost all said consistency of pricing and execution was what mattered most, but the availability of capital, either by capital introductions or by capital allocation from banks themselves, remains an important driver in directing flows. A large global agricultural trading house says that funding relationships will always be the main determinant of where deal flow is directed. Price was not considered a key differentiator except by set-arbitrage players, who transact in large volumes according to the instructions of their algorithms.
“How banks expect to make money from e-commerce I do not know,” says one large London-based arbitrage player. The squeeze on revenue is already evident, he says, as banks give away algorithmic trading tools to clients and they can also be replicated elsewhere. Euromoney understands algo solutions can be sold to clients for as much as $70 to $80 per million. The investor says the market has become so competitive that by shopping around FX traders can often find banks that will give them away, while the more sophisticated algo funds manufacture their own. It also raises the issue of why buy-side participants would pay brokerage on third-party platforms when they can execute at better prices and for nothing on single-dealer platforms.
Knowledge is power
It would be wrong to say that market makers fail to understand this. Most realize that the marginal cost of transacting increasing volumes at decreasing spreads is not a key driver for revenue growth; rather, what counts is the intelligent use of the information flows that result from the volume. The question then becomes, who has the best information network?
It is this question that particularly excites HSBC and Citi, the two big “global footprint” banks. HSBC revealed to Euromoney last month that revenues from FX were $3 billion last year, not including its private banking and retail units (see Investment banking: HSBC builds a force to be reckoned with Euromoney, April 2010). This puts it in the top three in terms of revenues, according to Fred Boillereau, HSBC’s global head of FX and metals. When Euromoney visits Citi’s global head of foreign exchange, Anil Prasad, he maintains that by revenue Citi has by far the most profitable franchise. Although Citi, like most of the industry, does not break out its FX earnings, some banking analysts who spoke to Euromoney said its total revenues could be in the region of $5 billion. Deutsche, Barclays and UBS also declined to give a breakdown on their FX revenue numbers.
Citi by its own admission is late to the e-commerce game, as a quick glance at the FX survey over the past decade demonstrates. Before e-commerce Citi was ranked No 1 but with the onset of e-trading it has slipped, bottoming out at fifth in 2009. Prasad tells Euromoney of a presentation he gave at an offsite held by chief executive Vikram Pandit last October in Princeton called: ‘It’s never too late to innovate’: “I held up the iPhone to the audience and said: ‘Look guys, Nokia was in the mobile business for God knows how long before Apple showed up with its apps and yet Apple overtook everyone’.”
Velocity, Citi’s electronic FX platform, was launched in July 2008, and the bank has continued to add new functionality to it since. He lists key features such as stack pricing, which links prices with deal size, its algorithmic tool Silent Partner, and other intelligent order systems as key differentiators, although it is not obvious how they differ from similar offerings on Autobahn and Barx. Velocity is now recognized to be rapidly catching up and even overtaking the electronic platforms of rivals, Prasad maintains. One high-frequency FX fund manager Euromoney spoke to says that he expects Velocity will be up with the very top platforms in terms of liquidity by the end of the year. As at the end of March, year-on-year volumes traded on Velocity increased more than 380%, Citi says. Prasad refers back to his Apple analogy and adds that Citi will soon be rolling out pricing on its iPhone app.
 |
|
|
“This is the real challenge, to have live streaming quotes at any time day or night while keeping volatility curves, forwards and spot prices updated, it is really an art and a piece of technology I don’t think many banks have” Martin Wiedmann, Credit Suisse |
Again, it is something other banks have already started doing. Credit Suisse, which rose one place to eighth in this year’s survey, is already providing live streaming option prices via its Merlin FX platform, says Martin Wiedmann, global head of FX sales and distribution: “This is the real challenge, to have live streaming quotes at any time day or night while keeping volatility curves, forwards and spot prices updated, it is really an art and a piece of technology I don’t think many banks have.” Its pricing server prices about 15,000 different options, he adds. JPMorgan rolled out functionality on the iPhone via its MorganDirect platform in March. Deutsche Bank, however, says that until it is convinced its technology is secure in the app space, it will not be rolling out an offering. No client base, no comment
For all the excitement about new technology, Prasad says not enough is made of client networks in driving revenue growth in a low-margin business. Prasad believes Citi can unlock the value of currency flows by organizing and analysing all the information across its network in real time, whether the trade is done over the phone or electronically. Pulling together all the information sources from Citi’s traders, salespeople and clients, he says, will give his 300 FX traders worldwide the ability to take more intelligent risk and encourage clients to deal more as they receive the value of the added analysis. Prasad calls it Citi’s very own information highway.
“This industrialization of FX that we see before us has the potential for you to lose your profitability as spreads compress going forward,” he says. “But on the other hand, if you can consolidate all that flow information, provided you have the right market share and access to liquidity, you will be even more profitable.”
Flow analysis is hardly a revolutionary idea. It is something that Citi has been doing for more than a decade, but as margins tighten banks will be forced to extract more value from the information to take risk themselves. Prasad adds the internalization model alone won’t cut it.
For HSBC’s Boillereau, the challenge is to redevelop its e-commerce offering to leverage the bank’s global footprint. HSBC is currently developing a client-user interface for its execution platform, as well as full connectivity with other services such as transactional banking and other asset classes. “In technology things are converging, so the big difference will be the client base you have,” he says. “There are some very good platforms out there, but do they have enough clients? If our platform can connect with our clients, then we will win. The trick for us now is to get our new platform live.”
HSBC’s commitment to FX has also been questioned in the past because it didn’t provide an FX prime brokerage service. It now plans to go live with FX prime brokerage by the end of June, with one or two clients introduced in the first few months and more on board by the end of the year.
As the dominance of Deutsche Bank and Barclays in the electronic dogfight suggests, success is built on many years of development in front-end execution, risk management and post-trade services, which have been tried and tested. The risk for the chasing pack is that bringing rushed solutions to market might do more harm than good to their franchises. It is a tough balance to strike, when the impatience for hard results from management demands return on the investment in infrastructure. The 2010 Euromoney survey suggests that the leading banks are facing erosion of market share as others attempt to replicate their success. The 2011 survey will surely indicate whether this is sustainable.


