 Awards for Excellence 2010 |
|
| Best Global equity derivatives house: BNP Paribas | |
| Also nominated: Société Générale and JPMorgan |
As equity markets reeled at the height of the European sovereign crisis in May, volatility spiked through the roof. Ten-day volatility on the Dow Jones Eurostoxx 50 index rocketed from a March low of 10.47 to a peak of 71.71 on May 14. Several media reports suggested that large losses had been incurred at banks and hedge funds, which had been short variance and correlation products in the run-up to those huge market moves. It had shades of 2008. Had no one learnt anything?
“After the crisis many clients realized that they’d been buying things that were a bit too leveraged, a bit too exotic and not that transparent,” says Bertrand Delarue, global head of flow product engineering at BNP Paribas. Clearly, that message hasn’t quite got through – markets find leveraged bets a hard drug to kick. As Delarue explains, shorting variance swaps on single stocks in the current market is a bet on the markets calming down. “That’s a big bet to make; variance is a bull-market product, on single stocks, it’s a sucker’s game.”
In 2009 BNP stopped actively making markets on single-stock variance swaps and began offering volatility swaps because they presented less risk to investors and themselves. Similar to variance, but less sensitive to choppy markets, they are a play on the price volatility of stocks. This makes the volatility swap a less risky product to sell to investors as well as investment banks. Indeed, following extreme market moves, the residual volatility exposure of a volatility swap might even decrease, rather than rise as it does on variance. It began pricing volatility swaps in Asia, where single-stock liquidity had all but disappeared, before deciding to gather market support for the product in Europe and the US.
“We met fierce resistance from all the banks,” says Delarue. Most market makers didn’t believe that volatility swaps were replicable in the same way as variance. So BNP decided to go it alone. They have now priced more than €20 million of vega; according to what their clients tell them anecdotally, volatility swaps volumes are more than double the size of the variance market.
 |
|
|
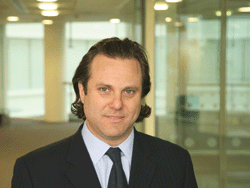
“If you want to differentiate yourself, then volatility swaps is it. We really went against the current. But we now have some of the major equity derivatives banks offering them”
Shaun Wainstein, BNP Paribas |
“If you want to differentiate yourself, then this is it. We really went against the current here,” says Shaun Wainstein, head of equities and derivatives London. “But we now have some of the major equity derivatives banks offering volatility swaps.”
BNP also introduced a product for dispersion trading; a common trade that is structured using variance or volatility swaps. In 2009, almost all of the vol swaps it traded were in the dispersion format. Wainstein says that developments in May were the first real test of strength for the product. And the product has stood the test.
During May, BNP says its own volatility swap dispersion books didn’t lose money, and that it had a very firm handle on risk, while its clients who were long volatility swaps suffered losses much lower than would have been the case with variance. In fact, Delarue says the same clients that had bought volatility-based dispersion were putting on more size – the best sign of confidence in the product. The evidence that the strategy is already working is borne out in BNP’s first-quarter earnings. Its equity and advisory business made record revenues of €845 million; on that run rate lifting it into the top-three banks in equity derivatives by revenue. It is building momentum.
In structured retail, BNP continues to build market share. It now has a 35% share of the Italian non-captive retail market and it has gained more customers in Belgium following its acquisition of Fortis. Again the same conservative theme applies: an emphasis on capital-guaranteed products targeting long-term investors. BNP has also developed a volatility mechanism that can be embedded into its structured products that adapt to market conditions, a first for the retail market. In the event that volatility falls, the product invests more, and when volatility rises the product reduces the investment.
As the derivatives markets face more scrutiny by regulators, BNP feels it has a good case to make that it has adapted best to the new paradigm of the derivatives market: transparency, suitability and risk control.
“We have a pretty good structure for approving products, where we ask: ‘Is that correct for the client?’ If the client has too much to lose, we won’t do it,” says Wainstein. “We’ve walked away from things, even when the client said they were big enough to look after themselves. But we had to take a view. The reputation risk angle and the angle of clients wanting to trade with you after five years, after 10 years, will be a key distinguishing factor in the future.”




