|
| THE TRAILBLAZERS |
In June, some of the world’s largest financial institutions pumped almost £50 million into Fnality International for the delivery of the Utility Settlement Coin (USC) project.
USC is a digital cash settlement asset, used to settle tokenized value transactions backed by fiat currency held at a central bank.
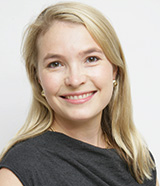
Andrea Melville, managing director of commercialisation and propositions for global transaction banking at Lloyds Banking Group, is also a board member of Fnality. She successfully acquired investment for Series-A funding in the consortium, the first investment in a blockchain consortium that the bank has made.
“USC is pre-funded and pegged directly to existing currency, so it’s not going to fluctuate in value like cryptocurrency,” says Melville. “The development of USC is being undertaken with a strong understanding and respect for how payments and settlements work, which – as a low-risk bank – is a concept that we can get on board with and one that has value in the real cross-border environment as we move towards instant payments.”
Fnality will explore issuing the USC in five different currencies – euros, sterling, US dollars, Canadian dollars and yen.
“Right now, we are not sure which currency the USC will launch in first,” says Melville. “We are working with the central banks to see which will be the most viable.
“At the moment, if you are making cross-border payments utilizing the correspondent banking network, by its very nature, with multiple parties and time zones, it can take time. But if you can bypass this, using USC, your business will be able to run much more smoothly.
“One of our ambitions at Fnality is to grow the number of bank partners we have on board because we will see benefits in the network effect. There is power in numbers,” she says.
As banks continue to de-risk and close correspondent banking relationships, this may be one of the few viable ways forward for international trade.
API development
Melville’s 10 years at Lloyds have centred on innovation and technological development. As well as looking into blockchain and tokenization, she has been closely involved in application program interface (API) development at the bank.
|
|
|
Andrea Melville |
“Faster payments are a reality, and this impacts the interactions we have with our clients and the products we offer them,” says Melville.
“APIs are central to this. Our corporate clients want to move their money easily and instantly – just like we do in our everyday lives using a whole host of apps on our mobile phones. Why shouldn’t banking be just as simple as booking a hotel or ordering a taxi? This is where our philosophy comes from.”
In Lloyds’ API labs, the bank collaborates with clients to deliver a list of priorities for customers. Something that Melville is particularly proud of is an API the bank has developed with one of its corporate clients, online car financing startup Blue Motor Finance. The API uses the Faster Payment rails to deliver instant loans to Blue Motor clients, which means that money can clear their accounts within two minutes.
“An API is a way in which we can share standardized data sets for the direct and instant benefit of customers,” says Melville, “This has applicability across the board in banking, because it can help form and create a variety of useful APIs that help our customers’ bank.”
Open banking
Sharing data via open banking, as part of the second EU Payments Services Directive (PSD2), is an exciting prospect for Melville, who was open banking director at Lloyds before taking up her current position. But how does this sit with the EU’s General Data Protection Regulation (GDPR), which is about safeguarding individuals’ data?
“There has been some discussion around how open banking and PSD2, which is about data sharing, will work alongside GDPR, which in essence is about data protection,” says Melville. “But at their core, both are ultimately about giving customers control.
“Think of it this way: if I allow a third-party access to my data then there is a shift here to ensure that the user is central to how data is used. Previously, there was this idea that banks owned the data, but through GDPR and PSD2, the user is in complete control of this.
“This will lead to competition, which will allow customers to pick and choose services that align closely with their goals.
“In the long run, this can only be a good thing,” says Melville. “And banks innovating with their customers from the start will find that their customers are much more likely to stick by them.”