Ostensibly, there appeared little excitement to whet the appetites of yen traders throughout May. The yen was locked in tight ranges against various other currencies, and, not surprisingly, implied volatility started to trend lower. One-month vol, which was being quoted at around 19% at the end of March, had eased off to below 14% near the end of May. Other currencies were clearly moving around to a greater extent. But even if the yen was becalmed there was enough news flow to suggest that activity could pick up.
At the time of writing, the yen had easily shrugged off a series of negative pieces of news. On May 18, the currency came under initial pressure after Moody’s downgraded Japan’s foreign-currency debt from Aaa to Aa2. However, in this era of relative devalue trading, the yen soon regained its poise. The fact that Moody’s also saw fit to upgrade Japan’s long-term local-currency debt to Aa2 from Aa3 left, in the words of Bank of Tokyo Mitsubishi UFJ, “many Japan watchers nonplussed… For JGB holders as a whole, this should be a positive development, given that net external debt only totals 12% of GDP.” Perhaps importantly, Bank of Tokyo Mitsubishi UFJ highlighted the fact that Moody’s had made the “connection between Japan’s considerable savings surpluses, which have allowed the government to ensure smooth domestic absorption of new issues”.
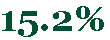 |
Annualized fall in Japanese GDP based on Q1 data |
Similarly, the release of what appeared to be a disastrous GDP figure was also shrugged off. “The GDP data for the first quarter… was nearly as bad as the markets expected,” says Bank of Tokyo Mitsubishi UFJ’s European head of global currency research, Derek Halpenny. “The 15.2% plunge on a quarter-on-quarter annualized basis was the largest on record, surpassing what had been the worst quarter on record (–3.4% in Q1 1974) but for the downward revision to the fourth quarter of last year – from –3.2% to –3.8%.” Halpenny’s colleague, Naomi Fink, the bank’s Japan strategist, says that, for the moment, there does not appear to be the normal appetite to buy yen from exporters. “Having spent the months of February and March relatively over-hedged, exporters are not terribly keen to step in to sell dollars, especially at current levels (the 95 handle),” she says. “Many Japanese exporters are finished with their yen hedges for the quarter, and have taken to hedging their exposure over the July-September quarter when opportunities present themselves.”
This suggests that the lid many might expect to be on dollar/yen, euro/yen and sterling/yen in particular might not be there should the yen start to weaken. However, Fink believes exporters have become more opportunistic. “Many exporters have successfully picked the point of saturation of foreign-led speculative longs to place euro/yen and sterling/yen selling hedges,” she says.
No doubt Japanese exporters will be fully aware that an old story is doing the rounds again, which will only further encourage them to maintain a wait-and-see policy. “Trust in US treasuries has eroded with the introduction of quantitative easing,” says BNP Paribas. The bank argues that the point might be near when the US suffers large portfolio outflows. “The reputation of the US seems to have fallen to levels not seen since the years of President Carter. At that time confidence in the US dollar was low, forcing the US to issue non-dollar-denominated bonds in yen and Deutschmarks.




