|
|
A year ago there was a sense that Standard Chartered had turned the corner after a series of difficult years. Numbers were moving in the right direction, the right staff had been hired and the culture had shifted. But, 12 months on, you couldn’t say the progress has been consistently upward.
It has been in some respects. Third-quarter net profit, announced in October, was dramatically up over the year, to $752 million from $557 million a year earlier. Pre-tax profit, at $1.1 billion, was up 37% over the previous year and has outpaced analysts’ expectations. Common equity tier-1 was up, to 14.5% of risk-weighted assets, well above the bank’s stated target range of 12% to 13%; non-performing loans were down, reflecting progress in digesting distressed debt.
“We set out the plan three years ago to get the bank repositioned and back up and running,” says Andy Halford, group chief financial officer at Standard Chartered, who has been instrumental in the bank’s transformation alongside chief executive Bill Winters. “This is year three of that process, and I think on a number of fronts we are moving forwards pretty significantly.”
In his view, those areas of positive momentum include the top line, balance-sheet strength and culture – “getting 85,000 people across the world pointing in the right direction.”
And on the negative side?
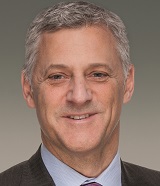 |
| Bill Winters |
“If I was reflecting on the ‘not yet’, we have yet to get to the 8% return on equity we targeted,” he says, much less the 10% Winters has pledged to reach in the medium term. The last stated number was 6.1%, obstinately low, and it is clear that frustrations have bubbled internally. In October, an email Halford sent to staff was leaked, saying that the bank faced a big challenge to meet its 2018 cost reduction targets and had made “virtually no progress” in doing so since adjusting budgets in May.
And clearly a US-China trade war will not help a bank that has most of its business in emerging markets.
“There is a lot of rhetoric on trade wars,” says Halford. “We’ve got an interesting period ahead of us to work through. We hope it will not be too consequential, but time will tell.”
One challenge in evaluating where Standard Chartered is going is that a new strategy is expected to be announced in February. One rumour talks about a greatly simplified business to reduce costs and free up liquidity, another about share buybacks and dividends.
The bank could no doubt make itself more popular with beleaguered investors by conducting a buyback – the share price is down 40% since Winters took over and trades at less than half book value. That makes it good value to buy back and it would help with that irksome return on equity number. It also represents a potentially better use of surplus funds than what Standard Chartered has tended to do with cash in the not-too-distant past – namely, put it in the wrong places.
But no returns to shareholders are likely to take place until the bank has resolution on any fines it may have to pay for allegedly breaching international sanctions on Iran.
It would be helpful to get those fines announced and digested, although the timing is beyond the bank’s control. They are expected to exceed $1 billion, a frustration for management since every alleged issue predates both Halford and Winters’ arrival at the bank.
While Halford cannot go into great detail about what the February update will entail, he does say that it “will not be a revolution but an evolution in strategy: clearly over a three-year period there are changes in the external environment.”
Within that, “looking at productivity and efficiency wouldn’t be a surprise,” he says.
StanChart divides itself into four geographic regions and four client groups. Strength can be found in Greater China and north Asia, the corporate and institutional bank (in terms of trajectory) and retail (in terms of outright return relative to risk-weighted assets).
Weakness appears in the Middle East and Africa, and perhaps private banking, which Halford says is “going through a significant amount of system investment.” Indeed, this business in particular is thought likely to be the subject of some redirection in February.
The mighty profit growth from the third quarter should not be seen as reflecting shining performance in the underlying businesses. In fact, the improvement was chiefly because of lower impairment costs on loans.
Still, Halford says the bank can “make sure we take our share of the growth there is in the banking sector revenue pools in which we operate. The markets we are operating in, on average, have banking system revenues going up about 5% to 6% a year.”
Sustained top-line growth at that level, coupled with operating cost growth kept at or below inflation, gives a workable model and even, dare we say it, a path to that elusive ROE target.
Roll on February for the details.



