|
|
A year ago Euromoney reported that Qatar National Bank was weathering the storm that had descended on Qatar in large part thanks to its bold geographical expansion during the previous decade.
As Qatar’s neighbours blockaded the emirate, its largest bank was able to survive thanks to its dominance at home and its large presence outside the Gulf.
Since then, the environment in which QNB operates has become no less difficult. What might have been a brief geopolitical tiff has turned into a permanent state of affairs. Qatar’s emir did not join his former allies at the latest Gulf Cooperation Council meeting in December, confirming that no thaw in tensions is on the horizon.
For the time being, QNB has to do largely without Qatar’s main economic partners of the past. Outside the Gulf, the bank has also had to contend with a fresh plunge of the lira in Turkey, another of its key markets.
Still, its numbers are holding up, if less impressively than they once did.
“Today, Qatar has successfully overcome the blockade and it has served as a catalyst and platform for future long-term growth where the challenges imposed were transformed into opportunities,” QNB’s acting chief executive, Abdulla Mubarak Al-Khalifa, tells Euromoney.
As it adapted to this new environment, QNB did not thrive but nor did it sink. As of the end of September 2018, its net interest income was down slightly year on year, but its profit before income tax was up by 5.3%, to QR3.6 billion ($990 million). That was certainly a slowdown – in the previous year that metric had risen 13% – but its basic health was not in question.
Since then, QNB’s growth has slowed further. By the end of the third quarter of 2018, profit before income tax had grown by only 3.2%, to just under QR4 billion – the sort of growth you would expect from a European bank, not a bank active in what are typically some of the world’s most vibrant emerging markets.
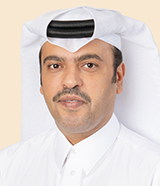 |
| Abdulla Mubarak Al-Khalifa |
That has not dented the bank’s position as the largest one by assets in the Middle East and north Africa. In fact, QNB’s total assets increased substantially during last year, rising 7.7% to QR853 billion.
“From QNB’s perspective, the blockade has done little to substantially diminish our position as the largest bank in Middle East and Africa,” says Al-Khalifa. “Domestically, it has reinvigorated the market, fostering more innovation and self-sufficiency. It has fuelled a number of sizeable food security, tourism and infrastructure projects that QNB is instrumental in supporting.”
Although economic conditions in Turkey, where the bank bought Finansbank from National Bank of Greece in 2016, have been hard, QNB has maintained impressive momentum.
“The devaluation of the Turkish lira and the consequent economic slowdown came as a surprise,” says Al-Khalifa.
Still, Finansbank increased its net profits by 13% in US dollar terms year-on-year by the end of the third quarter.
“This was driven by the momentum of the balance sheet, continued cost and risk discipline,” Al-Khalifa explains.
Perhaps QNB should not have entered Turkey when it did. That market has long been highly competitive and volatile, and it only got worse after the attempted military coup against president Recep Erdogan, which took place just weeks after the finalization of QNB’s acquisition of Finansbank.
Still, QNB’s ability to keep growing in Turkey, as well as in its two other core markets of Egypt and Qatar, is to its credit.
If anything, QNB is now more important than ever to Qatar, which needs stable institutions through this challenging period.
At the start of November, Qatar appointed the bank’s then chief executive Ali Ahmed Al-Kuwari as its trade and industry minister – a key post at a time when the Gulf state is having to compensate the loss of some trade relationships with the establishment of new ones, and when the preparation for the 2022 FIFA World Cup requires a lot of construction work.
Al-Kuwari’s replacement, at least for now, is Al-Khalifa, who was already on the boards of the group’s investment arm and Egyptian bank, as well as Ecobank, the pan-African institution of which QNB is a large shareholder. On paper, he should therefore have the breadth of experience needed to head such a large and varied operation.
In coming months, the bank will need all of his and his colleagues’ expertise to restore its prospects. There is not much room for QNB’s business to contract any further without damaging profits.



