 |
Best Bank: Westpac |
Westpac has generally been viewed as the most conservative of Australia’s big four banks, and that’s never been a more welcome accolade than over the past 12 months. It hasn’t come through the market upheaval unscathed but its modest decline in profit is dreamland compared with what has happened to many US and European banks. Westpac today has the highest tier 1 capital ratio in Australia, the best asset quality and the cleanest balance sheet.
 |
|
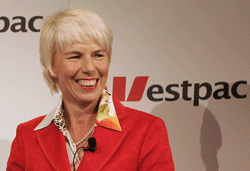
Gail Kelly: keeping the St George brand within Westpac |
The jury is necessarily still out on how the merger with St George pans out but there is no significant customer leakage yet. St George did bring some bad residential property loans into the business and it will take time to see if Gail Kelly’s vision of maintaining the St George brand rather than blending it into Westpac will work. Westpac is using the downturn to pursue mortgage market share aggressively, and this too will look either foolish or a masterstroke depending on what happens next in the Australian economy. But there is a clear strategy at Westpac, and the handful of analysts prepared to put any buy recommendations the way of Australian banking are tending to opt for Westpac when they do. UBS continues to lead the field in Australian equities no matter how you measure it. Overall volume, number of deals, secondary market, research: it has competitors in every area but none stacks up so completely across the board.
On the primary side, UBS demonstrated its capacity in February when it was at least a joint lead on six deals in six days, raising A$5.5 billion ($4.37 billion) between them, for Tabcorp, Henderson, Newcrest, Qantas, Westfield and Suncorp-Metway. It has been on big IPOs, such as the Ivanhoe Australia listing; heavyweight secondaries, such as the A$4.6 billion Wesfarmers accelerated entitlement offer and the A$3 billion follow-on for National Australia Bank; innovative deals, such as the one used by Crown and Axa to enable related-party participation in capital raisings through a placement structure; and hybrids, such as the two raisings of tier 1 stapled preference securities for Westpac.
On top of that it is has been the dominant secondary market trader in Australia for the past eight years and has one of the best research teams in the country, with 50 analysts covering 270 stocks. Goldman Sachs JB Were in particular gave it a good run this year but UBS still leads the field.
There were banks that excelled in domestic bonds in Australia in our review period, and banks that were impressive in taking Australians overseas, but JPMorgan stood out best for achieving in both fields.
The big story in 2008-09 was about getting bank capital from the international markets. Of seven government-guaranteed transactions by Australian banks, JPMorgan was bookrunner on five, taking Suncorp, Macquarie, Commonwealth Bank, Westpac and ANZ into dollars. On top of that, it also took five different banks into euros; brought the first post-Lehman 144A issue by an Australian corporate for Woodside; was a bookrunner on Rio Tinto’s eye-popping $5 billion deal; and was active in sterling and US private placements.
On the domestic side, JPMorgan has grown strongly too, with a A$735 million convertible preference issue for Suncorp a standout. It has also brought foreigners into Australia, notably RBS, the first bond to be issued with a guarantee from a foreign sovereign. Considering JPMorgan’s domestic platform was only set up in 2007, the pace of success has been remarkable. In fact, it had a good year in all areas of investment banking and is the foreign name to watch.
Big splits
There was no clear winner in M&A in Australia this year, with the big deals split between half a dozen houses. In that environment it’s the house with the consistent track record that takes the prize, and UBS has remained among the leaders for a decade now.
Its landmark transaction was advising St George on its takeover by Westpac. Competitors find this a simple deal notable only for its A$18.6 billion size; in fact, from St George’s perspective, with the deal taking place through the depths of the financial crisis, it was a vital deal and secured a good outcome for shareholders.
Elsewhere, UBS advised Zinifex on its A$6.2 billion merger with Oxiana, and helped Cadbury and Vodafone on Australian asset deals. It was also part of the trend of bringing China into Australian assets – although it ran into regulatory barriers, it appeared at the time of writing that the restructured takeover of most OZ Minerals assets by China Minmetals was likely to go through successfully.


