 |
|
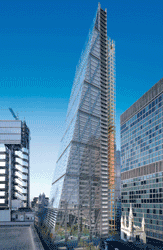
British Land is still looking for tenants for its Leadenhall development |
These are difficult times for UK real estate funds. Some of the collective panic that hit Northern Rock’s customers last year spread into the real estate sector. In the last quarter of 2007, more than £1.6 billion ($3.11 billion) flooded out of commercial property funds as nervous investors, mainly retail, decided to cut their losses. Figures from the Association of Real Estate Funds (AREF), which surveys £37 billion of property funds, showed outflows up by 76% in the third quarter of 2007.
This was after at least six UK property funds slapped restrictions on withdrawals. The rush for the exits prompted by the UK property slump forced the hand of Scottish Widows, Scottish Equitable, Friends Provident, Morley, UBS, Schroders and Deutsche to stop redemptions.
Rachel McIsaac, chief executive of AREF, said retail investors had led the stampede. But institutional money was being pulled out too.
Peter Hobbs, head of research at Deutsche Bank’s RREEF, which manages £100 billion, said in January that the UK commercial property market was “falling apart”. He estimated that the UK’s £700 billion commercial property market would underperform the rest of Europe, Asia and the US. Banks tightening lending would add to the pressure.
William Hill, head of Schroder Property Investment Management, which has property of £10 billion, said there was market hysteria and funds were struggling to find buyers for their properties to meet investor redemptions.
The storm abates
But now fund managers are starting to put their heads back above ground and tentatively suggest that the storm has passed.
Gerry Ferguson, head of UK property fund management at Scottish Widows Investment Partnership (SWIP), says there are grounds for optimism and he believes the worst is over.
“We’ve all stabilized in terms of redemptions. We’ve all got satisfactory liquidity levels and we’re working things through the current market conditions,” he says. “We all reacted pretty quickly to the change in investor sentiment that happened very quickly at the end of July. Hopefully it has been a testament to property fund management that we have dealt with that and funds have remained in operation.”
The fund management community has had to work overtime to reassure its remaining investors that the asset class is worth persevering with. The collective loss in confidence will take some restoring. However, fund managers such as Ferguson believe the reasons for investing in property remain as compelling as ever.
“People continue to recognize the value of property within a diverse investment portfolio and they are prepared to come back into property. It’s a matter of timing,” he says. “There is a correction in the property market but the fundamentals are still there. There is positive GDP growth, rental growth, there’s no massive oversupply as there was in 1992.”
SWIP was among those warning customers last year that high property values were unsustainable and it was forecasting a big drop in returns. Ferguson argues that valuations are now at a more sensible level.
Money has already started to come back into the market. Raymond Mould, a veteran real estate investor, raised £250 million in November in an IPO to take advantage of lower prices. Robert Houston, chief executive of ING REIM, says its new Global Opportunities Fund will consider the UK now, whereas last year prices were too high.
Painful correction
But the slump has left its mark. Falling values for commercial property meant UK real estate funds incurred losses of 9.1% in the fourth quarter, the worst performance since Investment Property Databank began compiling data in 1990.
Specialist property funds suffered their first losses in more than 14 years in the third quarter and in October the situation worsened as £160 million of net outflows hit the sector. A month later, redemptions increased to a net £495 million.
Scottish Widows Property Pension Fund and the Scottish Widows Property Life Fund, with combined assets of £2.15 billion, slapped restrictions of 180 days on the two funds’ 200,000 investors. Aegon put a 12-month freeze on its £2 billion Scottish Equitable property funds.
New Star Asset Management switched from monthly appraisals of its fund values to at least twice a month. It said the value of properties in its flagship £1.7 billion Property Unit Trust mutual fund fell 18% from July to the end of the year.
|
“It has been a testament to property fund management that funds have remained in operation” |
 |
Scottish Widows said cash in its funds had fallen to less than 2% of combined assets. “The delay means that we can implement an orderly programme of sales over a longer period,” it said. “Our fund managers will have the opportunity to obtain fair values for properties we sell.” Investors were taking their money out of the funds faster than their managers could sell properties, following a 10% slump in the commercial property market.
By giving themselves more breathing space, the funds hoped to avoid a fire sale of assets and to protect performance for investors staying put. Scottish Widows has not applied the restriction to its other real estate funds, such as the Ferguson’s SWIP Property Trust, which still has more than 8% of its assets in cash.
Now AREF believes that, following the sharp correction, the downturn will not be prolonged, that outflows have reduced substantially and that there are the first signs of inflows gaining momentum.
Although retail investors are always more likely to have shorter-term investment horizons and will look to get funds out in a falling market, the sector is set to remain buoyed up by pension funds that want to maintain a real estate allocation in their portfolios.
1989 and all that
The industry is also keen to draw a distinction between today’s market and that of the crash of 1989-93 when property values fell by 27%. Then the problems stemmed from an economic recession, rising interest rates and oversupply left by a construction boom.
The most high profile victim of all this was Olympia & York, which was bankrupted after beginning the development of Canary Wharf.
Cliff Hawkins, who runs the £2.4 billion Triton Property Fund at UBS Asset Management, says the situation today is healthier than in 1989-93. The rate of unemployment is still low and the Bank of England has reduced interest rates to 5.25%.
CB Richard Ellis says commercial rents continue to rise in London, thanks to a supply shortage, making it the world’s most expensive location.
But some figures are still damning. Jones Lang LaSalle, a commercial real estate broker, said final-quarter 2007 transactions in the UK fell by 60% to about £5 billion.
Mike Prew, analyst at Lehman Brothers, says the latest slip in commercial property values has been shorter, sharper and more shocking than previous falls.
This has taken its toll. Westfield Group, which owns shopping centres around the UK, cancelled plans to sell the remaining 33% of its £530 million UK shopping centre fund.
Shares in investment trusts and developers have also been hit hard. Capital & Regional fell 75% last year. It was the UK’s worst-performing property stock and its 27% stake in the £1.3 billion Junction Fund fell 24% in the first 11 months of 2007.
British Land marked down the value of its property portfolio by 8.9% in the fourth quarter of 2007, cutting its net asset value per share by 16%. Stephen Hester, chief executive, said that markets had “taken a hatchet” to price levels, and there was still scope for further falls.
British Land is still looking for tenants for its Ropemaker and Leadenhall Building developments in the City of London, which are both scheduled for completion by 2011. Its search will not be helped by financial institutions tightening belts in the wake of the credit crunch. British Land’s shares fell 45% in 2007, an even harder fall than the sector’s average 39% slump.
Real estate shares were the worst performers of 39 industry groups on the London Stock Exchange last year.
Martin Allen, analyst at Morgan Stanley, expects UK property companies to suffer further falls in 2008.
Allen has predicted that 2008 will see a short, sharp rally for UK property shares. However, he remains bearish for the outlook over two years. His report, UK property shares – it’s so bad, it’s good, predicted a 20% bounce in the first half of the year but that over the next 18 months a recession would force down rents.
Morgan Stanley’s pessimism has been echoed by HSBC, which predicts a 25% to 35% correction in the UK commercial property market. It has downgraded Reits. It believes rental values and yield will fall thanks to lack of demand and oversupply.
Analysts John Fraser-Andrews and Nicholas Lyle say the property sell-offs in retail investment funds will suppress returns into next year. “Sustained forced liquidations by property funds and debt-squeezed investors could outweigh opportunity fund investments,” they say.
Nevertheless there are silver linings. The UK still makes up 25% of Europe’s real estate investment market and, according to AREF, property funds still raised a net £425 million in the last quarter of 2007, despite all the outflows.
SWIP’s Ferguson says tougher market conditions will enable talented fund managers to show their worth.
“Over the last couple of years a rising tide saw everyone through, so quality of management wasn’t valued. In the next couple of years management is going to be able to show the qualities they have,” he says.
Ferguson adds that strong-willed investors who have ridden out the correction should look for the opportunities it will provide. Having taken the pain, he argues, why miss the gains?



