Equiduct: evolutionary leapfrog
Euro Millennium: exporting US expertise
Turquoise: the banks slowly muscle in
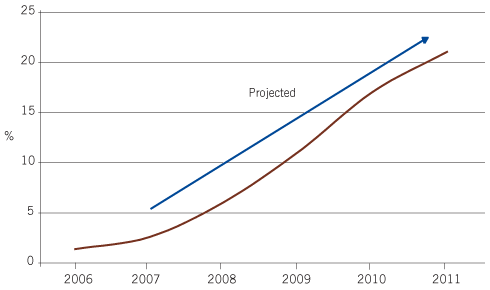
MULTILATERAL TRADING FACILITIES have so far not enjoyed the same kind of success in Europe as their cousins the alternative trading systems (ATSs) have in the US. Estimates for the total market share of European equity trading held by MTFs range from 1% to 3%. Advances in smart order routing technology, a more favourable regulatory environment and familiarity with fragmented markets in the US, however, mean that the barriers to success have been substantially lowered and MTFs are expected to become much more influential in the near future. Consultancy Aite Group estimates that MTFs could capture as much as 20% of the market by 2011.
“It used to be that if alternative venues didn’t enjoy a big-bang start that people would rapidly lose interest and they would soon fall into obscurity and die,” says Richard Balarkas, head of AES sales at Credit Suisse in London. “But traders no longer have to study two screens and agonize over what may or may not happen on a new venue. Smart order routing makes it much easier to give new venues a chance. There is nothing to lose by connecting to a new venue, there is little cost involved and you don’t use up desk space as you don’t even need a screen. Liquidity could appear one day and dry up altogether the next, but it doesn’t matter because whether or not you trade on them is entirely down to the smart order routing logic. If there’s nothing going on at one venue then the machine ignores it and moves on, but if attractive liquidity re-appears, it instantly moves in and gets it.”
The spread of unbundling and of commission-sharing arrangements is also freeing those on the buy side to make more choices about where they want to send their trades.
“The amount of crossing a buy-side firm could do used to be limited by the amount of execution-only trading they could afford,” explains John Barker, chief executive of Liquinet Europe, a buy-side-only MTF that has been in Europe for five years. “They couldn’t trade more than about 10% of their volumes themselves on alternative trading venues because they needed to trade with the brokers to pay for other things, such as research. Unbundling, however, means that the shackles are off.”
Sensing that the confluence of regulatory factors and technological development has made the European market ripe for change, numerous groups are working on setting up MTFs in Europe. At least four (Equiduct, Euro Millennium, SmartPool and Turquoise), will be ready for launch in 2008. However, according to market sources, there are dozens of early-stage start-ups looking for cash to fund their ideas.
For established US ATSs, European expansion is high on the agenda.
“I think most ATSs will look at opportunities in Europe and Asia as a way to expand,” says Sang Lee, managing partner of Aite Group. “Just because they’ve been successful at home, however, doesn’t mean that they will automatically be successful abroad. They will need to really study the local market conditions and figure out how they can adapt their models. They will also find that European exchanges are in a much better position to fight off competition than their US peers were. When competition began in the US, most of the exchanges were not even electronic, so the new competitors were really able to meet previously unfulfilled requirements.”
|
“An exchange can be more than just an order book. By building a dark pool crossing platform we are adapting to the market” |
 |
Nyfix, which in the US operates a dark pool – an anonymous trading system where orders are not displayed – called Millennium, is the latest US ATS to set its sights on the European market. It plans to launch its Euro Millennium dark pool by the second quarter of 2008 and this December announced a joint venture with SWX, the Swiss Exchange, to create a dark pool, integrated with the exchange’s order book, for Swiss blue chips. Meanwhile, Bats, an ultra-fast order-book-style ATS based in Kansas that has made waves by winning 9% of the US market in just 18 months, and Pipeline, a liquidity pool so dark that its matching engine is described as blind, are both actively studying the European market with a view towards either setting up in Europe or at least signing up European traders to use its systems when trading US stocks.
Competition threat
The threat of competition has jarred European exchanges out of their complacency. Some, such as the London Stock Exchange, have improved the speed and capacity of their systems to better compete against MTFs offering higher speeds and capacity, such as Chi-X; others, including NYSE Euronext and the Börse Berlin, plan to launch innovative MTFs of their own.
NYSE Euronext has teamed up with BNP Paribas and HSBC to develop a dark pool MTF aimed at the block market, an area in which exchanges have traditionally been weak. The MTF, known as Project SmartPool, is scheduled to launch in the second quarter of 2008. Unlike the SWX/Nyfix joint venture and unlike Turquoise, SmartPool does not plan to integrate the dark pool with the order book, at least initially, and will focus exclusively on catering to the sell side.
“An exchange can be more than just an order book,” says Roland Bellegarde, deputy CEO of global cash markets at NYSE Euronext in Paris. “Many large market participants, such as pension funds, do not typically do small trades but what you see on an exchange is exactly that – small trades. There is clearly a discrepancy there and by building a dark pool crossing platform we are adapting to the market.”
Börse Berlin’s plans are more ambitious. The German regional exchange is set to launch a pan-European trading system that will offer best execution in the form of a European volume-weighted best bid-offer price that it will calculate from the prices of all displayed order books at exchanges and other MTFs (see Equiduct: evolutionary leapfrog).
|
Benefits of choice |
|
Projected adoption of multilateral trading facilities |
 |
|
Source: Aite Group |
The varied market models being proposed can be roughly broken down into three types: high-speed, high-capacity open order books that offer price discovery, similar to exchange systems, targeting high-volume users such as investment banks, hedge funds and algorithmic traders; anonymous, non-displayed dark pools, some of which are tailored for larger trade sizes; and market-maker-based systems designed to cater to smaller brokers with mainly retail order flow. However, the distinction between the groupings is blurred by new systems that propose to tightly integrate their dark pools with their order books and by hidden order types, such as icebergs, on exchange and MTF order books that represent a huge amount of undisplayed, dark, liquidity. Consultancy Celent estimates that iceberg orders – orders that display only a fraction of the true amount available at the quoted price – account for more than 50% of the liquidity at the best five quotes and 30% of the liquidity at the inside quote on Euronext markets. On Nasdaq, Celent estimates that hidden orders, which sit undisplayed on the order book, account for 15% to 20% of the total volume.
Not everyone, however, is convinced that this blurring of displayed and undisplayed liquidity, of lit, that is, open order books, and dark pools is a good thing.
“The value of a dark pool is directly related to how dark it is,” says Alasdair Haynes, CEO of ITG International. “The point of a dark pool is that it offers you the chance to trade anonymously and undetected, so the moment you do anything to compromise those virtues, the moment you let any light into the dark, you undermine its value. It becomes neither one nor the other, just a mess.”
 |
“The value of a dark pool is directly related to how dark it is. The point of a dark pool is that it offers you the chance to trade anonymously and undetected” |
Haynes believes that smart order routing technology will encourage the development of highly specialized trading venues. “In the 1990s everyone was looking for the one-stop shop, but the one-stop shopping era is over because we now have the smart order routing technology to easily take advantage of specialist, best of breed venues,” he says. “An MTF needs to be clear about what it wants to offer because it needs to be the best at what it does in order to succeed.”
Challenge and opportunity
While the expansion of MTFs creates challenges for some, it also creates opportunities for others. BNP Paribas Securities Services, for one, believes that the growth of MTFs in Europe could create an interesting niche business for post-trade service providers.
“The growth that we have seen from our activity as a general clearing member [GCM] on Chi-X has been very encouraging,” says Patrick Colle, head of product – clearing, settlement and custody – at BNP Paribas Securities Services. “We expect MTFs to win close to 20% of the cash equities market so are positioning ourselves to be a leader in the post-trade services space for MTFs, providing GCM services to those with central counterparties and global settlement services to those without a central counterparty.”
Participants from all segments of the market feel that 2008 is going to be a watershed year in the European trading landscape. The confluence of regulatory incentives and technological progress mean that alternatives to stock exchanges have a better chance of succeeding than ever before. Although it is just the beginning, 2008 could well turn out to be the year of the MTF.