Merrill Lynch
|
Also shortlisted in this category: |
It is hard to ignore Merrill Lynch in the CDO market – it is just so big. Its global issuance grew from $26.5 billion to $55 billion last year – a jump of 110%. But sheer size can bring its own problems and it is often hard to keep at the cutting edge of innovation while managing flows of this magnitude. However, Merrill has again spearheaded innovation in CDO structuring while maintaining its position at the top of the pile. A recent industry ranking had the firm as the number one synthetic CDO counterparty by notional volume for 2006, with a 23% market share (this reflects its strength in the senior part of the capital structure – by risk-weighted volume it falls to number five with a 9% share). It also maintained its traditional dominance of the global CDO rankings, claiming a 12.2% market share for 2006, which rises to 17.9% for the first quarter of 2007.
The CDO market has been less than rosy in the first half of 2007, and Merrill, with its 25% market share of the ABS CDO market, has found itself squarely in the centre of the action, not only as a structurer but as a warehouse lender. Rumours persist that the bank has taken one of the biggest hits in its CDO warehouse lending business but it seems to have managed the exposure without damaging the CDO business.
 |
|
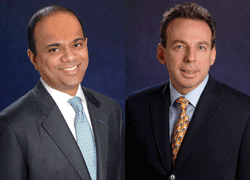
Harin De Silva (l) and Ken Margolis, co-heads of Merrill’s CDO business |
“This has been a tough market but we have weathered the storm,” says Kenneth Margolis, co-head of Merrill’s CDO business. “We are now working on several new ABS CDO deals and are building new warehouses which are not legacy deals. Our ability to do this is testament to our strong franchise – what managers want is certainty of execution.”
Like everyone else in this market Merrill has spent recent months managing the impact of the US sub-prime market but it has also racked up an impressive series of firsts. “We have continued to innovate through turbulent markets,” says Margolis. “But we are doing firsts that we think are scaleable and repeatable.”
Unlike many of its close competitors, Merrill has led the way in developing entirely new asset classes as well as structures. Most notable in this regard was the first tax-exempt CDO, the Non-Profit Preferred Funding deal last October, which was backed by middle market non-profit corporations. “There are a lot of underserved tax-exempt institutions out there,” says Harin De Silva, co-head of the business with Margolis. “This deal is a huge opportunity going forward.” The deal is managed by Cohen Municipal Capital Management and includes exposure to cultural, educational, healthcare, philanthropic, research and service/advocacy institutions. Another deal involving unusual CDO collateral was the second synthetic Essential Public Infrastructure Capital (Epic) deal in July, which was backed by global project finance loans.
As well as introducing new types of collateral, Merrill has pushed the boundaries on the structuring side. In July it brought Jazz 3 for Axa Investment Managers. The deal built on the earlier two Jazz deals but extended the franchise from corporate names and ABS to investment-grade bonds and loans. It is the first hybrid cash and synthetic CDO where the collateral manager can actively manage cash or synthetic assets at any time during the deal. “It really doesn’t matter any more whether a security is cash or synthetic,” muses Margolis. Earlier in 2006 it transferred this technology to the CMBS market with the first 100% synthetic high-grade CMBS CDO, Calculus.
CLO issuance has dominated the cash market over the past 12 months and the groundwork that Merrill did last year to build its presence in the sector has paid off. So far in 2007 it has underwritten 23 CLOs in the US and 10 in Europe and claims to be the largest mid-market underwriter of CLOs in the market. “We hired Tom Majewski from Bear Stearns in November last year to build a broadly syndicated CLO business,” explains De Silva, co-head of the business with Margolis. “Merrill is not a big loan shop but with the emergence of private equity other banks have lost their competitive advantage,” Margolis says. Structural innovation in this sector during 2006 included the first CLO vehicle with investments in distressed assets – the $500 million Global Leveraged Capital Credit Opportunity Fund and Golden Tree Capital Opportunities, the first arbitrage CLO to allow internal origination of middle-market loans. Merrill also closed the first rated CLO of Asian distressed debt for Clearwater Capital Partners.


