 |
Euromoney’s borrower awards 2007 |
| Overall awards | |
| Best sovereign/supranational/agency borrower | Best bank borrower |
| Best insurance borrower | Best ABS |
| Best CDO borrower | Best covered bond issuer |
| Best corporate borrower | Best high-yield/leveraged finance borrower |
| Latin America regional awards | |
| Best sovereign borrower | Best corporate borrower |
| Best financial borrower | |
| Central & Eastern Europe regional awards | |
| Best sovereign borrower | Best corporate borrower |
| Best financial borrower | |
| Asia regional awards | |
| Best sovereign borrower | Best corporate borrower |
| Best financial borrower | |
| Middle East and northern Africa regional awards | |
| Best borrower | |
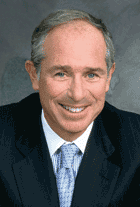 |
Wall Street bankers say that Stephen Schwarzmann’s Blackstone has made a unique investment in staff with debt markets expertise |
From June 2006 to May 2007 there was unprecedented activity in the North American high-yield and leveraged loan market. Borrowers with sub-investment grade ratings raised more than $146 trillion in 257 deals, and 2,219 leveraged loan deals worth almost $950 billion were executed. The significant number of transactions in these markets has been attributed to the increase in debt-raising by private equity firms. Private equity companies have been raising money in the debt markets to fund buyouts, consequently returning to restructure their financing.
Blackstone Group has been among the private equity companies to regularly visit the US high-yield and leveraged loan markets. Between 75% and 80% of the deals Blackstone has been involved in have been financed through debt. In 2006, it raised $35 billion in the debt market. For the role the firm has played in these markets either through raising debt for its own acquisitions, being involved in deals for companies it owns, and being a lender, Blackstone is heralded by many in the industry as one of the smartest high-yield and leveraged finance borrowers in the US. A head of leveraged loans at a co-arranger says: “The debt platform they have is an enormous asset to their private equity business in terms of being on the other side of the table, having an eye on the markets and really knowing what works and what doesn’t. On some level, they have the organizational capabilities in there too to do direct lending, which puts them in the seat of an underwriter, and further lends itself to being a good borrower.”
Blackstone’s investments in building out staff and expanding expertise in debt have enabled the firm to put together complex financing packages with the aid of the investment banks. The head of leveraged finance for a Wall Street investment bank says: “Blackstone is very well staffed and has a very experienced group of key partners arranged by verticals [sectors]. What they do greater than their competitors, however, is that they have really made an investment in staff with industry and financing expertise. They have a layer of junior partners who are organized by sector, for example. It means that they have the wherewithal to dig deep when doing transactions and figure out the most flexible and cost-efficient capital structures to match the investment needs of the businesses they are buying. It has paid off in their ability to handle complex transactions.”
One such complex deal is Travelport. The firm was travel service company Cendant’s travel distribution business, which was bought out by Blackstone for $4.5 billion last August. Blackstone put up $1 billion of its equity to make the transaction in addition to borrowing in the leveraged loan market. In March this year, Blackstone, through Travelport, issued the largest ever PIK loan, at $1.1 billion, in order to refinance the acquisition, enabling the firm to take out all of its initial equity. At the end of last year, Travelport merged Worldspan into a subsidiary. At the same time, Worldspan completed a recapitalization plan. As part of this recapitalization plan, Travelport loaned $125 million to Worldspan in exchange for a PIK note which Travelport funded through cash on hand. In addition, Blackstone also loaned Worldspan $125 million in exchange for a PIK note. Blackstone has announced that it will be taking public Travelport’s subsidiary, online travel agent Orbitz. It’s likely that a debt financing will come out of that as well.
The leveraged buyout of US retailer Michael’s Stores also resulted in a high-yield deal acclaimed by Wall Street observers. The $6 billion deal by Bain and Blackstone was the largest LBO last year. To fund the acquisition, the two private equity firms raised more than $500 million in the high-yield market. A banker says: “Michael’s Stores is a retailer. It sells arts and crafts goods such as glue and glitter and is not a sector that debt investors like. But Blackstone and Bain have background in understanding the durability of a company, and that company acts as a real differentiator. The fact that they managed to attract investors is a testimony to their insight into the credit markets.”
Such insight will be crucial if critics of the private equity market are correct in thinking that the levels of debt that private equity firms are taking on is too high, and that there is a lack of risk premium in the selling of the debt to investors. One fear is that liquidity will dry up. Many LBOs are pushed through quickly on unfavourable terms, with the financing restructured at a later date through loans. If liquidity dries up quickly, some banks might refuse to arrange deals, and private equity firms will be forced to put their underlying portfolios up for auction. One investment banker says he is less fearful about Blackstone’s position than that of smaller private equity houses. “Blackstone eats, sleeps and breathes debt, and is expanding its debt business,” he says. “They know what they are doing and should be prepared for any changes in the market environment.”



