INVESTOR INTEREST IN currencies shows no signs of abating so far this year. With projected returns in other asset classes showing few indications of improvement, currency funds have emerged as an attractive investment alternative. Although active currency management is not a new concept, the proliferation of currency-only funds over the past year has fostered many different investment styles. “The most aggressive growth we’ve seen is clients seeking total return,” says Matthew Cobon, director of currency fund management at Deutsche Asset Management. “Hedge fund strategies and traditional overlay strategies are now providing clients with cash and returns they want. And it isn’t just big institutional investors buying into this investment style. We are seeing interest from smaller entities as well.”
A wealth of hedge fund styles are now to hand as currency managers increasingly realize that their skills can be applied in a hedge funds context. “We have consequently seen more currency funds being set up in the hope of capturing a share of the demand for hedge funds,” says Bill Muysken, global head of research at Mercer Investment Consulting. “Most of them have been managing currency exposures for many years but the difference now is that we are seeing them offer this service through currency funds.”
In this quarter alone, a range of more sophisticated currency-only investment vehicles have been launched in response to rising investor demand. Saxo Bank, one of Europe’s largest currency trading platforms, expanded its existing asset management business through the launch of an offshore hedge fund, the Saxo Global Currency Fund. After four years of generating consistent, low-volatility returns through its managed accounts, Saxo launched this fund to provide international access to its investment strategy.
“Over the years, Saxo only offered its currency programme through its managed accounts. Since many investors prefer a fund structure, we wanted to offer a more traditional vehicle to the investment community,” says Matthew Brown, managing principle of Brownstone Advisors in New York. Brownstone is the lead investor in the new Saxo fund and serves as Saxo’s global business development partner. The Saxo Global Currency Fund, based in the Cayman Islands, employs a systematic approach to trading currencies. The proprietary model, created by Saxo’s CIO Steen Jakobsen, generates the programme’s entry and exit signals. These signals can be elected or not elected, so the fund carries a discretionary overlay. “We believe the the programme benefits from the combination of a systematic approach and discretionary overlay,” adds Brown. “The discretionary input is a defensive rather than offensive portfolio management tool.”

The IFX Zenith Currency Fund plans to launch before the end of this quarter; the investment manager will be IFX Capital Management, a division of IFX Markets Ltd. Like Saxo Bank, it wants to tap into a more diverse investor base. “We have always wanted to create a fund that captures smaller investors rather than the larger investor types in managed accounts,” says Philip Jones, head of business development at IFX Capital Management. “In addition, France and Switzerland, for example, have many investors involved in funds of funds rather than managed accounts, so this fund will enable us to expand our services to such clients, as well as responding to interest shown by potential fund of funds clients who want to invest in currencies.” Its investment strategy will be based on IFX Capital Management’s Zenith Programme, which focuses on intra-day trading in five major currency pairs.
Despite the wealth of systematically operated currency funds, discretionary funds are proving just as popular. Specialist management company ECU Group launched its Managed Currency Fund in January. The fund trades a wider range of major currency pairs and uses more sophisticated risk management tools than ECU’s existing Multi-Currency Debt Management Programme. The fund’s investment strategy is entirely discretionary, employing fundamental and technical inputs, with low leverage. It mainly engages in currency forwards, with the occasional use of currency options. It is domiciled in the Caymans, with a minimum investment of $1 million.
Black boxes underperform
Last year was difficult for any manager taking investment decisions on the dollar, forcing some investors to question the risks underpinning model-driven funds. “Black-box or model-driven currency funds haven’t fared as well as discretionary funds over the past 12 months,” says Neil MacKinnon, chief currency strategist at ECU Group. “Functions such as range trading dominated 2004, resulting in some model-driven funds posting double-digit negative returns. Discretionary funds have shown more sustainable results and, year to date, our Managed Currency Fund is up 3.7%, suggesting that discretionary funds can nimbly perform during turbulent market positions.”
|
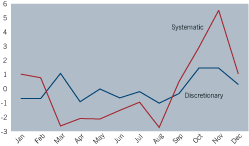
Parker indices Monthly returns in 2004 (%) |
 |
| Source: Parker |
The Parker FX Index tracks the performance that managers have generated from positioning long or short foreign currencies. In 2004, the Parker Systematic Index was down 0.58% whereas the Parker Discretionary Index was down just 0.24% (see graph). From inception, the compounded annual return for the Parker Systematic Index and the Parker Discretionary Index is 15.58% and 11.90% respectively. But on a risk-adjusted basis, the indices returned 3.39% and 4.29%, respectively.
“There has been a debate about model versus discretionary currency funds,” says Pierre Le Queux, head of currency management at ABN Amro. “Model-driven funds tend to be trend following so if you put them on a peer benchmark it looks as though they are carrying a higher amount of risk. Discretionary funds operate on more varied time frames and investment style, and so have a lower level of correlation though you could argue about their capacity of implementation in terms of size. You will have risk reduction out of purely discretionary style but over the long term, if you take each individual fund, they are not so dissimilar in their risk-adjusted returns than model-driven ones.”
ABN Amro launched its currency fund in April 2004 when currencies were trading in a tight range, making it extremely difficult to extract alpha over this period. “At the time, a lot of model-driven currency funds had losses well into double digits,” says Le Queux. “We were very displeased with the lack of opportunity but our investment process, which does not solely rely on trends, did fare relatively well in this adverse environment.” ABN Amro managed to recoup its losses and has made a return of just over 4% net of fees since the fund’s inception. “If you launch a fund at the wrong time, sure, you’re not going to look good,” he adds. “Does this make the product less attractive? No, you need to add see the value of your investment over a period of time, say one or two years.”
So investors looking to make quick bets on currencies may have to take a more long-term view to reap the benefits. ABN Amro’s currency fund has daily liquidity whereas several other funds have monthly liquidity. This means investors can’t enter or exit quickly. Whatever side you take, the growth of currency funds has made it a lot easier now for investors to have a better understanding of how different approaches have fared. “As a product set, currency is gaining more maturity and showing decent track records now,” says DeAM’s Cobon. “Clients don’t have to rush into currency funds as they now have historical relevance. If clients approach us we can now offer them publishable track records, which wasn’t so before.”
Too many players?
Many market participants expect this rise of currency funds to continue so should investors be concerned that the market could get swamped, reducing returns? A key attraction for currency funds is that they cater for enormous capacity and liquidity. ECU’s
MacKinnon notes that in other asset classes such as fixed income or equities, there has been a tendency for returns to compress, taking arbitrage away from performance. “In currencies, alpha is scaleable so performance is unaffected by size,” he says. “Our view on dollar/yen for example, would be no different if it was for one million or 100 million as the performance would be the same. Given the size of the FX market now, investors may find that currency funds are more attractive in their performance. The scale and liquidity of the currency market can absorb more players compared to asset classes such as fixed income or equities.”
ABN Amro’s Le Queux concurs: “There is a wealth of styles at hand and currency funds can offer good capacity because of the great liquidity in the currency markets. Although it is the one market that can accommodate a wide number of funds, it does need a very specific skill set.”
Currencies remain a good investment candidate as they provide uncorrelated returns. Their growth over the past year has certainly been powerful but investors should not be alarmed by this proliferation. “It definitely hasn’t reached saturation point,” says DeAm’s Cobon. “The amount of active currency assets under management compared to the volumes of FX traded in the market is very small. Suppressed returns in other assets have definitely helped our case and I would argue that investors are actually buying currency out of choice rather than being forced to do it.”