Inside IT | Boom time for IT vendors | Definitions:Software gets space-age | Survey results | Trading Screen: Pulling IT all together
 |
|
Buhannic: technology is redefining traditional roles |
AT A RECENT meeting with a large European buy-side firm, I asked the key question defining the financial industry today. “In your opinion what will be the broker of the future?” The head of trading at the firm, one of the most highly regarded in the community, looked at me smiling, taking his time before saying: “You”. I looked a bit confused and said: “But I am not a broker and never will be!” He replied: “This is exactly my point”. Silence. Could it be true? Could it be that the future of the brokerage industry is not brokers as we know them today but a loose network of connection points to a community with value-added services – such as market making, data providing, clearing or investing – embedded in the network itself? Could the burst of technology innovation in the financial arena fundamentally redefine the role of all its players?
That might be a bit of a stretch, but if you consider the underlying evolutions of technology at the disposal of the financial markets this is now possible and maybe even probable. However, as always, technology merely creates a multitude of possible paths to the future. Technology does not make the choices: users of it do. The only ambition of the vision expressed below is to state where technology stands today in the light of some of the key issues facing the industry. Darwinian evolution theory, which applies so well to the financial industry, will in due time establish which of the following ideas we can identify in the market today will frame our future as a community and determine the role of each type of player.
A growing need for the creation of a meta financial network There has been an explosion of trading and information volumes (market data, algorithmic trading, etc) and if what we have seen so far in the electronic distribution of financial products is just the beginning, we should look carefully at the infrastructure needed to ensure speed, accuracy, redundancy, security and good delivery of all these transactions. The networking layer at the bottom, based on the TCP/IP protocol, has demonstrated its quality over the past decade. And the layer on top, the application layer, has already had its revolution and has seen multiple quality offerings flourishing and improving rapidly. On the other hand a growing gap is appearing today between the quality of these two layers and the intermediate communications layer, which is barely adequate. This area should be of great concern and needs a serious review.
So why not create, leveraging on the huge success and acceptance of the FIX electronic trading protocol, a finance-specific communication layer that would be built to add functionality in the area of speed, accuracy and security as well as going further for the coming need for a single plug and immediate implementation? Why don’t we call it Financial TCP to characterize it as the tool of the financial industry, wider-reaching than FIX technically, but still leveraging off the existing networking framework?
By optimizing trading and data delivery based on speed, accuracy and security, the Financial TCP would close the gap developing between the great capacity of the communications infrastructure on one side and a highly sophisticated world of applications on the other.
This new approach would build on four major trends in the financial industry.
The first of these is the progressive establishment of a lingua franca in the markets, which is overcoming a situation in which the financial markets have been historically characterized by an extraordinary split in the basic methods of communication between various actors. Regulations, country-specific infrastructure, cultural differences in the use of financial products and so on were creating a highly complex world where every cross-border activity in its broadest sense, including across asset classes as well as cross-country, was costly and had to be handled on an exception basis, increasing processing costs and reducing the potential volume of transactions to be executed.
Several factors are combining progressively to close this gap of communication: the progresssive benchmark introduction of trading protocols such as FIX, FPML, and the like; the start of a globalization of the product, entity and accounts referential through the advent of new standards such as ISO 15022, ISIN, BIC; and the creation of gated communities of users, organized on an industry basis. This makes end-to-end process integration feasible and the recent creation of ASP utilities providing this service will reduce systems implementation time as well as improve significantly the accuracy of transactions.
A second trend in financial markets is a greater standardization of trading roles. The number of intermediaries involved in a financial transaction between a buyer and a seller has consistently reduced over the past 20 years. With the final and late transformation of US exchanges into electronic exchanges and the growing use of electronic trading and processing in OTC markets, such as government bond trading and FX, most transactions involve either three players – client-broker/bank-client – or five players – client-broker-exchange-broker-client. A global trend is for the buy-side client to step more and more into traditional functions of brokerage firms by becoming non-clearing members on exchanges, or even clearers, as demonstrated recently by some hedge funds.
This evolution has been made possible by fundamental changes in the economics of technology. With the advent of standardization through the FIX protocol in the exchange links, or FIXML for back-end clearing communications, or the development of ASP model for most financial functions – risk management, trading platforms, back-office functions – as well as the huge decrease in computing power costs, the barriers to entry have been lowered. These cost reductions are enabling the buy side to integrate new pieces of the processing puzzle to its traditional research and accounting framework.
There is little difference today between the equipment, access to information or operational processes of a buy-side firm and a sell-side firm. There is convergence. One example is the buy-side trader who claims that he finds more liquidity in the large positions of securities holdings of other buy-side entities than in the trading books of the large sell side. Another is the buy sider who arranges a block anonymously on a crossing network and the sell side that finds liquidity through an interdealer broker. Then there are the buy and sell siders who both publish IOI or reverse IOI. The differences between counterparties are more concentrated on credit quality, appetite for risk taking, regulatory regime and capacity to leverage than on the traditional understanding of what the buy side, interdealer broker or sell side does.
A third fundamental trend affecting financial markets is theneed to cut a path through the jungle of data to get to what is relevant.
Market data is a clear challenge. The explosion in data production and the development of new forms of it is straining the existing infrastructures and exposing their dysfunctional features. Latency, multiplicity of delivery systems, bandwidth constraints, the lack of a common identification system, are all factors making this equation one of the most difficult to solve. At the same time it has become more and more important to gather the relevant information as liquidity gets split into more pools and the speed of transactions increases to a point where manual trading is not optimal. The development of internal matching, upstairs block trading and grey markets in general impose on firms the need to have a global strategy to gather this high value data and store it while being able to distribute it and present it to internal as well as external users in the most relevant way, avoiding the creation of pure information noise. This is an area of substantial development as traditional market data groups, which traditionally were more concerned with data provider’s contract management, will evolve towards becoming strategic gatherers of data.
The future there should belong to a publish-and-subscribe approach, consuming less bandwidth and working very much like the internet itself, with market data packets being shipped around the world only on an as-needed basis and avoiding the high costs and latency of the hub-and-spoke central approach used by providers serving everyone the same information package. The market will abandon the broadcast, one size fits all, approach that has dominated for 20 years. Ticker plants will be located close to the price sources, and aggregation of data will happen in multiple different fashions at the end customer desktop with a standardized authorization process.
The fourth trend in financial markets is the growing importance of outsourcing as the key to quality global offerings.
As in many industries, and especially in the PC industry with the example of Dell, the future will belong not to the entirely integrated process firms of the 1920s but to the firm that will build the best composite offering, the best marketing and the best servicing. No PC is built by Dell yet they are number one in their segment. The concept of the virtual firm, while still young, will encroach progressively in the financial industry. Already a number of examples demonstrate the power of linking best-of-breed services across providers under a single brand name and servicing umbrella.
Outsourcing is here to stay. Good firms will learn how to leverage it positively to enhance their brand and reduce their cost base. This makes such cooperative network approaches possible.
All of the four trends discussed above make the likelihood of a network concept very likely. Logic always prevails over time.
The market looks set for massive efficiencies and cost improvements Finance processing has been undergoing a quiet revolution that only technology-based industries have historically faced. It has met the challenge of matching every commission reduction by a greater cost reduction over more than 20 years.
The creation of a new concept of a specific financial communication layer going further than the efforts in FIX would foster just another step in the evolution of the economics of the financial industry, especially in the product distribution and core processing areas. It would continue the existing positive trends but would also provide the right approach to go to the next step and exploit the next frontier in finance computing – grid computing.
A first feature of financial markets that is already becoming apparent is that the cost of brokerage is becoming less relevant in the transaction cost analysis framework. When you compare today’s brokerage costs for equity trades – even for full-service commissions, which are often less than 10 basis points – to the possible cost of the market impact of trades, which can exceed 25bp, you discover that they have become close to irrelevant in the decision-making process.
This is certainly true for DMA (direct market access) type trades and it is also increasingly true in all asset classes. In the futures business execution commissions have largely vanished through a combination of some firms practising yearly charges irrespective of volume and some buy-side firms becoming non-clearing members. In FX the spread is already non-existent for some currencies, yet some banks are pushing the prices one decimal further. The other key factor behind reduction of brokerage charges is the unbundling of research. The market is slowly moving from a combined approach of execution services and research to a DMA or algo execution with an explicit payment for research services.
In the meantime, liquidity has not changed dramatically and the interest of not being read by the market is higher than ever. This explains the high demand for such strategies as Icebergs and algorithmic VWAP trading. These strategies are not just another fad. They represent the natural evolution of the market, concentrating its attention where its transaction costs are. These developments will become an intrinsic part of all firms’ development strategies and will prompt large investments in this area, if only as a defensive measure. This approach is gradually being applied on other asset classes other than equity.
The declining relevance of brokerage costs is being matched by a similar trend in technology costs. Effectively, the cost of technology in transactions processing is following a pattern that makes it largely immaterial over time.
This statement will sound surprising and iconoclastic given the size of the technology budgets of the large financial conglomerates. However, in doing such a cost analysis you must first split technology expenses into two: the efficient spending that achieves a real function and the large amount wasted on systems that are never really operational or achieve little purpose. These wasted expenses reached a peak in the technology bubble years, with firms trying, sometimes without any real plans, to outdo their rivals in capturing the internet space.
Secondly, for efficient spend you need to benchmark it. It is easy today to benchmark firms’ real expenses by process by comparing them with best-of-breed ASPs, which can offer the same quality of service but outsourced. It is then easy to calculate what amount of money could be redirected to other uses in the firms. This can be called the efficiency gap.
Firms can decide to build rather than buy the technology infrastructure they need, often for good reason, such as the need to keep clients captive, to master their risk management independently or to integrate their offering. However this has a cost as it cuts out any sharing of infrastructure with other firms. It would be foolish not to keep track accurately of the cost of this efficiency gap. It is on this best-of-breed approach, whether outsourced or internally built, whatever is cheaper, that the firms should calculate the cost per transaction or cost of efficient operation.
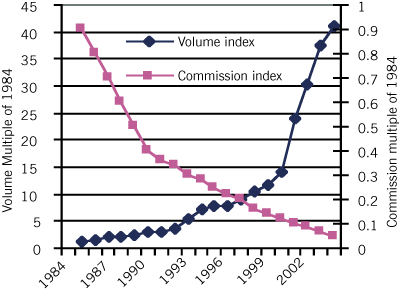
The explosion of volume going through existing IT infrastructures gives rise to amazing efficiency gains if harnessed properly, very much as in the microprocessor industry. For instance, in the futures industry a reduction of execution commission by an estimated factor of 25 over the past 20 years was accompanied by an increase in volume processed (and charged) of roughly 50 times. This means that the market overall has become twice as profitable, and this with a much higher level of operational efficiency, and that the cost per trade went down dramatically.
In most firms, however, while the cost of operation (real cost not optimized) for many processes has fallen, it has not fallen as fast as in the efficient ones. Firms that have not leveraged these opportunities offered by the combination of the new technologies and the new players, in areas as diverse as telecom connectivity, FIX deployment, trading screens deployed at the client shop, risk management, clearing and settlement and back office, could be in a dangerous cost structure situation when competition increases the pressure on revenues.
A third area where major cost savings and efficiency gains could be made is through a much greater use of network grid computing.
Finance has an infinite appetite for computing power to crunch ever more data, to handle for instance the options pricing explosion or evaluation of complex algorithmic trading strategy or market impact. Market data, as we have seen, is another area of stress for the market infrastructure. But if you put together the industry’s immense array of mainframes, workstations, computers and networks, you have millions of processors on line at any time. At best a small percentage of their computing power and storage is used. This makes the system a great candidate for grid computing.
If you could leverage the unused portion of all the available machines, through the relevant operating system functioning on a cooperative basis, some of the most intricate calculations in finance, such as complex forecasting, could be achieved a lot faster. In the same vein the market data equation will be resolved in the long term by smart use of this grid computing approach. This development would be a quantum leap for the economics of the industry and the build-up of this new network would be a great plus for this breakthrough approach.
What could stand in the way of this logic? Put together like this – it all looks easy enough, right? It seems like an attractive future where most in the financial industry will benefit. What then are the dangers facing the development and implementation of these new technologies? The main issue can be encapsulated in a single word: patent.
The financial industry, which is mainly after all concerned with manipulating information, had developed over the past 25 years one very special innovation model: a practically free-flowing innovation environment. Firms leveraged each other’s creation by acquiring know-how through recruitments of teams of specialists and outdoing their competitors with incremental development. This environment, contrary to the traditional theory that only innovation protection can justify creation of new ideas by giving the inventor an advantage, worked miracles for all parties. Financial firms created previously unheard of levels of wealth for shareholders and employees, clients’ costs of intermediation and borrowing dropped dramatically and the availability of capital increased for everyone. The share of financial services firms in the overall economy, as measured by GDP, is at an all-time high in countries that have offered a favourable environment to this industry. The employment level is high and offers many quality jobs. So why kill the goose that lays the golden egg?
If we want the innovations mentioned above, which are all pretty firmly established to flourish, we need to keep a free environment for them to shape the future for the maximum benefit of the community. If any single player were to get its hands on one of these key pieces of the technological puzzle, through patenting, it would effectively recreate the lacklustre monopolies of the past. Before calling on the regulators, it should be the industry mission to keep our paths to the future freely open.
Philippe Buhannic is CEO and co-founder of Trading Screen
| Futures and options |
|



