Calling the end to the decade-long commodity run was a popular thing to do in 2012. At one point in June, the average commodity had cratered – by 27% from June 2011 – prompting a chorus of comparisons to the peak and crash of 2008.
The main claim was that 2008 was the true secular peak and what we have witnessed since has been a false rally. The same pundits who proffered this opinion alleged that the 2012 price swoon was a last gasp, an aftershock of sorts, the final mark that the commodity move, which had started in 1999, was now dead. Since egg becomes nobody’s face, and Wall Street strategists are sensitive to such mishaps, the race was on to call the peak in commodities.
Unconvinced that we were looking at a commodity corpse, we spent oodles of energy in the back half of 2012 pleading with clients to maintain an appropriate perspective. In June, we drafted a list of seven markers that had been useful indicators of the ends of past commodity bull runs – some dating as far back as the early 1800s.
The markers are highly relevant for 2013, as the commodity bull run will be 14 years old and that much closer to its ultimate finish.
Most of the evidence today remains bullish on commodities, and it is likely that a few more up years are left. But to be clear, we are not perma-bulls. With certainty, we can say that commodities will meet their maker. It is just a matter of time. And time is marker number one.
Let’s begin with some context on secular commodity bull runs. When we say secular, we mean long-term trends that take years to complete.
One familiar example would be the secular bull market in US equities from 1982 to 2000. In commodity land, we’ve counted six such events since 1800. The average move lasted 16 years and gained 208%. Today’s bull market is 13 years and 212% old. Based on time and gains, this cycle has almost run its course… almost.
A few interesting stats on commodity bull markets: the shortest was eight years from 1972 to 1980; the longest was the 24 years from 1896 to 1920; the strongest was 330% from 1933 to 1951. Today the current cycle might be only 11 years old, not 13.
While our commodity composite bottomed in 1999, 2001 was the start of the surge for many commodities. Pinning down the age of today’s bull market is like knowing the exact age of Dominican Little-Leaguers.
What is common to all is that each secular bull market has ended as a burst bubble.
Marker number two is bubble action. Common to all commodity bull markets is that they burst in the end. This involves excessive end gains, followed by quick and deep losses. Markets notorious for this type of action in the past include: 1929 (Dow), 1980 (gold), 1990 (Nikkei), 2000 (Nasdaq) and, most recently, US housing. Watch for frothy conditions in commodities near the end.
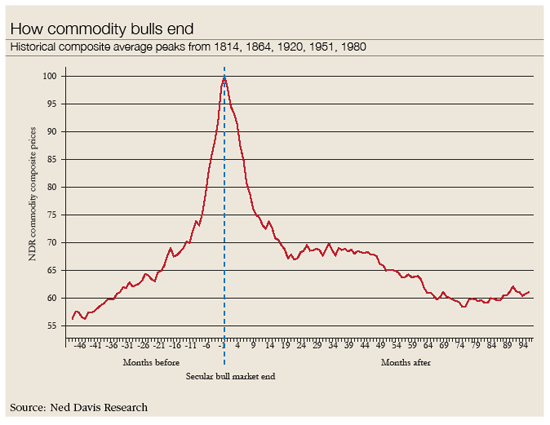 |
Be careful, though, that you see genuine froth. This includes not only price spikes travelling into the peak but also sustained deflated prices afterwards. The commodity peak this cycle is regularly labelled as 2008, but we believe this is incorrect. Action moving into July 2008 was bubble-like, but the response since has not been. Of the 17 commodities in our commodity composite, 13 have since surpassed their 2008 peaks. These are not bubble-bursting-like stats. Do you remember any Nasdaq stocks hitting new highs just a few years after the peak in 2000? I don’t, let alone 75% of the index. To call the final commodity peak, bubble-like action needs to be seen going in and coming out. THE THIRD MARKER THAT MIGHT signal that the end of a bull market is near is stretched valuation. Tracking the value of commodities is a little harder than with equities or bonds. We say this because equities have earnings and bonds have yields, and commodities have neither. But commodities do have history, and there are other ways to measure extremes. Seeing our commodity composite today versus its 10-year moving average, commodities do look historically expensive.
Another angle, and arguably the best way to value commodities is versus other assets, such as equities, bonds and housing. The picture here is a bit mixed, as the average commodity looks expensive versus all three assets, but only 1970s-super-expensive versus housing.
If you prefer a more personal example, let’s look at how many one-ounce gold coins you would have to cash in to buy a new home in the US. Today, you would need only 165 one-ounce coins to buy the average US new home. At the housing peak in 2007, this trade exhausted almost 500 ounces of gold. On the bright side, it took 88 ounces to buy the average new home in January 1980, the last time gold peaked. This suggests that gold is expensive today, but could become still more expensive before it reaches the end of the line.
Number four on our list of markers is money. Commodity bubbles, like other asset bubbles, feed on excessive credit. The years 1929 and 1999 were famous for excessive equity market margin bets, and the recent housing bust was seeded by Alt-A, sub-prime loans, etc. Commodities have historically been sensitive to money-supply growth rates in the US, averaging 8.6% during commodity bull markets – twice that of bear markets.
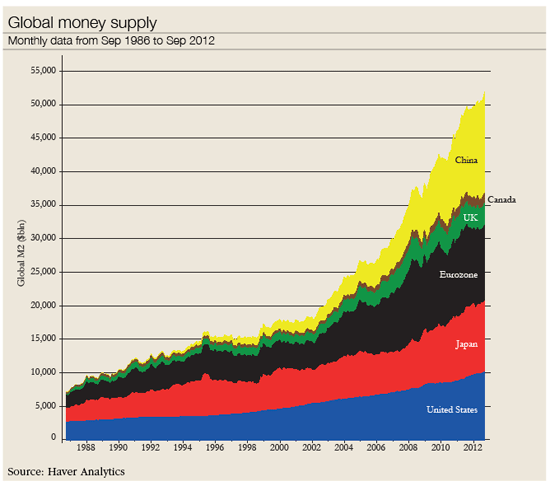 |
Looking at only the US, however, leaves the mind wanting a more global perspective. There was an explosion in total money supply (M2) by the principal players, starting around 2002. Consistently low money-supply growth rates could be the fourth sign that the end is near. Gold, in particular, could get hit hard if worldwide paper-money-printing campaigns are reined in. The fifth marker, real interest rates, is tied closely to the looseness of money. We care about real interest rates because commodity speculators require a low cost of carry. Real rates are, on average, negative during secular commodity bull markets, while nearly a positive 4% during secular bear markets. Global real rates are low across the board today, which is one of the strongest pieces of evidence to suggest that the commodity bull market will continue. However, a sharp reversal in real rates, combined with a new trend higher, would be a sign that the end is nigh.
Sign number six that the commodity bull is about to end is that equities are ready for a new secular bull market.
Not widely reported, but an interesting fact, is that commodity secular bull markets often run opposite to secular bear markets in equities. The commodity composite and the Dow Jones Industrials rarely overlap, and one bull market is often beginning while the other is ending. The 1940s, of course, was a glaring exception. We suspect that if equities enter a new bull market, global financial conditions are such that they will allow for an overlap with the commodity bull for a few years.
However, don’t expect a complete repeat of the 1940s. A new equity bull market is a signal that the commodity bull market is probably on borrowed time.
The last indicator is the need to watch China. The earlier markers were all related to history, but history has its limitations, as each cycle is different. In the 1940s, to take one example, lifting price controls after the Second World War had a massive effect on how the commodity bull market ended. The difference-maker this cycle has been the emergence of China. China’s impact on the commodity complex is plain. In 1980, China consumed 2% to 5% of the world’s copper, aluminium, zinc and nickel. Today, these consumption numbers are all more than 40%.
To quickly recapitulate, the current commodity secular bull market is 13 years and 212% old. The average historical bull market has lasted 16 years and gained 208%. Past commodity bull runs have all ended abruptly. Two of our seven markers, time and valuation, say that the end for commodities might be near. A third, the beginning of a new equity bull market, might be close as well. Watch for changes in Chinese commodity consumption and global monetary conditions, as they have close ties to today’s commodity bull.
Good luck, and let’s drink to a few more years of Chinese growth and a friendly Fed.
John LaForge is commodity strategist at Ned Davis Research



