 |
|
|
Best Infrastructure and project finance house: Société Générale CIB |
|
|
Also shortlisted: Bank of Tokyo Mitsubishi UFJ and HSBC |
Some $57 trillion of infrastructure investment is needed across the world between now and 2030 simply to keep pace with GDP growth, according to McKinsey Global Institute, the business and economics research unit of the consultancy.
That is nearly 60% more than the $36 trillion spent globally on infrastructure over the past 18 years when – except in the past five years – long-term debt financing from the global banking sector was cheap and plentiful.
In the post-crisis era, this type of financing is both expensive and fundamentally constrained, creating a financial challenge for world governments.
Increasingly, the capital markets and institutional investors such as insurance companies and big-beast asset managers are directly filling the void, but for now dollar-denominated bank lending remains the primary source of financing globally.
Given this, it might seem surprising that a French bank that has a natural funding base in euros and is today more selective in how it deploys its balance sheet to infrastructure projects worldwide can be recognized for this global award.
But then Société Générale CIB has advised on, engineered and executed landmark and in some cases transformational deals in North America, Central America, Europe and the Middle East, Africa and Asia Pacific in the past year, largely because of the financial advisory expertise the bank brings.
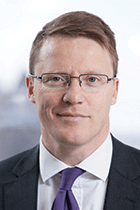 |
| Matthew Vickerstaff, global head of infrastructure and asset-based finance at SG CIB |
Balance-sheet commitment is obviously critical in this market, and SG CIB has ultimately been there when called upon. Just as vital, though, to the success of infrastructure and project financings is the quality of the advice from the very beginning to the very end. After all, a bad asset cannot be made good through structuring, but a good asset can be made bad.
Other banks of course have skilful advisory teams, and some can combine that with balance-sheet strength and an ability to commit themselves to sizeable deals, but there are few banks whose advisory, structuring and technical expertise is sought irrespective of their ability to lend, or indeed their willingness to do so. That in itself makes a powerful franchise, but the fact is that a bank still needs to put money where its mouth is.
“Ask the clients,” says Federico Turegano, global head, natural resources and energy finance at SG CIB. “Do they want an adviser that is not going to play?”
Two transactions that SG CIB was at the heart of and encapsulate its advisory expertise and financial commitment to landmark and transformational deals are the $3.6 billion financing for the Sabine Pass Liquefaction project – the first bi-directional liquefied natural gas terminal in the US – and the $4 billion acquisition financing for Open Grid Europe, Germany’s largest gas transmission network.
“The Sabine Pass transaction is a perfect example of our capabilities as lead adviser and lead financier,” says Matthew Vickerstaff, global head of infrastructure and asset-based finance at SG CIB. “It was a transformational deal for the US and the global LNG market and we were at the core of it.”
SG CIB was the sole financial adviser, and structured and joint-lead managed the non-recourse, senior debt financing backing the development, construction and placement into service of the first two liquefaction trains of the Sabine Pass Liquefaction facility, owned by Cheniere Energy Partners.
It is a project that will change the international dynamics of the LNG market, and as it is the first bi-directional LNG facility in the world capable of gasifying imported LNG and liquefying domestic gas supplies. The US stands to become a big gas exporter too.
“The Sabine Pass transaction is to us the poster child for what is happening in US shale gas today,” says Turegano.
The Macquarie Infrastructure and Real Assets-led consortium’s acquisition of Open Grid Europe was another coup for SG CIB on what was the largest infrastructure financing in 2012.
The bank was a bookrunning mandated lead arranger and hedge provider on the financing, but the real additional value came on the structuring and ratings advisory side.
“That’s where our differentiation from the market started to show itself,” says Vickerstaff.
In short, through SG CIB’s ratings advisory work, Open Grid Europe received an A minus rating from Standard & Poor’s earlier this year – above the triple-B-plus rating those involved in the financing had expected and paving the way for the acquisition refinancing completed on the capital markets in June.
“That deal is a good example of where we have played a leadership role,” adds Vickerstaff. “Across the board, the acquisition teams, the structuring teams, the syndication teams and the ratings advisory, we also did the swap and capital markets refinancing – it was the full team working together, bringing their expertise to a landmark transaction.”
The deal was recognized as one of Euromoney’s deals of the year for 2012.



