 |
|
|
Best Equity house: Morgan Stanley |
|
|
Also shortlisted: Goldman Sachs and Citi |
As central banks eased credit and liquidity concerns from mid-2012 and the equity capital markets revived, the large universal banks with hefty balance sheets to underwrite primary-market risk slipped a little in the ECM rankings. In less-stressed market conditions, leadership reverted to the traditional ECM franchise firms with strong equity distribution and smart ideas. And although Goldman led the league table for the period under review, Morgan Stanley pips it for the award this year in recognition of a string of important deals for its corporate clients spanning developed and emerging markets, sometimes executed in tough market conditions when other firms hunkered down.
“It was a year when many large corporations used the equity capital markets for strategic transactions, seeing it as preferable to the M&A market partly for tax reasons, but mainly for certainty of outcome. These are deals that simply cannot be allowed to go wrong,” says Raj Dhanda, Morgan Stanley’s co-head of global capital markets. Some examples are the £906 million ($1.39 billion) IPO of insurance company Direct Line from RBS, the largest European IPO in 2012, which Morgan Stanley priced as joint sponsor, joint global coordinator and joint bookrunner last October; the $1.27 billion IPO on the US market of ING US as part of ING Group’s continuing EC mandated restructuring, on which Morgan Stanley worked with the two other firms on this year’s shortlist, Goldman Sachs and Citi; and the $2.6 billion IPO of Zoetis, the animal-health division of Pfizer, which it floated in January. Morgan Stanley is the only adviser to have worked on all three of Pfizer’s recent separation transactions.
“We have a global institutional equity sales and trading capability that only one other firm comes close to matching,” says Dhanda, “and we now have the largest US retail brokerage, with $2 trillion of client wealth under management. We spend a lot of time talking to those brokers to understand the conditions when their clients will turn positive on markets and stocks.”
The strength of Morgan Stanley’s primary equity capability is illustrated by its work for luxury goods company Michael Kors. Morgan Stanley first paved the company’s way to public ownership in 2011 with a pre-IPO placement, then led its IPO in 2011 and a first follow-on offering in early 2012. In the period under review, it led two more follow-ons, raising $1.4 billion in September 2012 and $1.5 billion this February at tighter than average file-to-offer discounts. “Back in 2011 we were not a house bank for Michael Kors when they asked a few firms in to discuss their very ambitious goals to sell large volumes of stock,” says Dhanda. “We did a private placement with some leading institutional investors and marketed to a select group of high-net-worth clients. That established the company for every subsequent offer. The stock is now a natural for our retail brokers and we’ve led each follow-on at higher prices.”
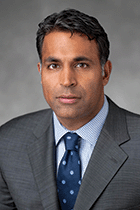 |
| Raj Dhanda, Morgan Stanley’s co-head of global capital markets |
Morgan Stanley was busy outside the US. It was lead global coordinator on the $1.8 billion IPO in London of Megafon, the second-largest mobile operator in Russia, last November, sticking with the transaction for the company owned by oligarch Alisher Usmanov even after Goldman Sachs withdrew with less than a week to launch.
Henrik Gobel, co-head of global capital markets for EMEA, says: “That would have worried a lot of people, but we had strong conviction on the IPO, and our sales people kept their heads cool and focused investors’ attention on the underlying strengths of the company and its excellent management team. And although they faced questions about corporate governance, they answered these. And investors did detailed homework on the company, management and owners before investing, as is common not just for emerging markets. Ultimately, the success of the deal shows the experience the buy side have in assessing each situation on its own merits.”
In Asia, Morgan Stanley’s performance in the 12 months under review was flattered by a reduced number of large equity offerings from China and by a revival of interest instead in Japan, where the efforts of monetary authorities to reflate the economy attracted flows back into Japanese stocks. Morgan Stanley is strong in Japan through its partnership with MUFG. Last September, it was a lead bookrunner on both the domestic and international tranches of the ¥633 billion ($6.48 billion) IPO of Japan Airlines, catching the first wave of renewed interest in Japanese stocks among overseas investors.
This was a very big deal, done in markets that were still volatile for 100% of a company coming out of restructuring, a Japanese equivalent to GM in the US. “We had maintained relationships in Japan going back more than 20 years and we have a top sector team covering the airline industry,” says Dhanda. “And we had history through GM of helping a government out of a restructured company. So we were an adviser from a very early stage in preparing for this. Being able to tap into Japanese retail through MUFG Securities and Japanese institutional and international demand, we were able to develop some price tension. We arranged more than 183 one-on-one meetings for the company with institutional investors, and eventually placed more than half the deal outside Japan.”



