|
|
| ICBC (Asia) | |
| Value | Rmb1.5 billion 6% tier-2 sub-debt bonds, 10-year non-call five |
| Bookrunners | HSBC, ICBC International, Bank of China HK, Credit Suisse, DBS, Goldman Sachs |
| return to the Asian Deals of the Year index | |
In 2011, the CNH market achieved a hectic graduation from nascent wild-west-style market to something approaching maturity and depth. The clearest illustration of this came with a Rmb1.5 billion [$240 million] subordinated bond from ICBC (Asia), owned by mainland banking heavyweight ICBC.
It was full of firsts. For a start, it was the first subordinated bond in the CNH market, and is expected to be followed by more. It was the first subordinated bond from Asia in any market to be Basle III compliant. And it brought 10-year tenor (this was a 10-year non-call five deal) to the CNH market, increasing its maturity.
“We had two hurdles to overcome,” says Peter Leung, chief financial officer of ICBC (Asia). “First was the marketing and selling, but even before we started that, we had to do a lot of persuading of the regulators. The HKMA [Hong Kong Monetary Authority] was not very keen to approve this sort of structure.”
The structure in question had to fit within Basle III requirements and involved something called the non-viability loss-absorption clause. If the bank is declared unviable – which would be done by the HKMA – then the value of the bonds is written down to zero. Since the HKMA has not yet clarified the precise parameters within which this might happen, it was naturally reticent to approve a structure, yet it did so, suggesting that the ICBC format will be the one for others to follow.
 |
|
|
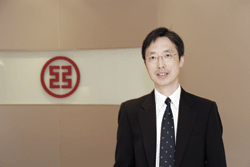
Peter Leung, ICBC (Asia) |
“Once the HKMA approved, we were able to convince investors this is the sort of structure regulators will be approving from now on,” says Leung. “There’s no possibility they will return to [old rules on] tier-2 deals; people have to live with it. Our explanation to potential investors was that they could keep waiting on the sidelines or look at this new structure.” The pitch worked: the book was more than Rmb5 billion from 83 accounts, allowing the deal to be priced at 6%, the tight end of guidance, that was more than agreeable for an issuer in a market that had no experience of 10-year paper or of sub debt, and that was being knocked about by problems in Europe. Better still, it then traded up in the days after launch, just as dollar bonds were widening.
Investors were reassured that the issuer is backed by, on some measurements, the world’s largest bank, and were unlikely to find themselves cut off. “ICBC (Asia) would be closing down in Hong Kong from the moment the loss absorption came into place,” says Leung. “It would mean all the investment, including the money that has been spent to privatize our bank, would go down the drain. It’s not even worth talking about this sort of risk coming into effect.” It’s likely to be the other big banks and their subsidiaries that take this route in the near term.
While the timing in early November looked hideous, Leung says it worked out well. “We found quite a sweet spot on it,” he says. “It was a time when some investors from China were keen to move their wealth overseas, but initially wanted to buy into some quality issuers in CNH. They were also getting fed up of the dim sum market because of questions on issuer quality.” Bringing a high-quality issue with a good yield was just what investors wanted to see.
|
Asia |
| Sun Art Retail Group |
| Kingdom of Thailand |
| ICBC (Asia) |
| BP/Reliance |
| Vedanta Resources |
| Republic of Indonesia |
| Return to the Deals of the Year main index |



