The European Commission has come up with measures to stiffen the Growth and Stability Pact. Originally designed to ensure that member states in the single currency zone would not allow fiscal and monetary imbalances that could lead to crises, GSP1 failed. Many member states never kept to the EC’s fiscal targets and GSP1 was unable to discipline the delinquents. Then the Greek debt crisis exploded, threatening to break up the euro area itself.
As the price of bailing out Greece and preparing funding for other possible sovereign debt defaulters in the EU, Germany and other more fiscally stable states have demanded a much stiffer fiscal pact. It looks to prevent fiscal delinquency in advance, impose automatic sanctions against those states that transgress and monitor possible excessive imbalances that develop in the single currency union.
The problem is that there are economic and political obstacles to making it work effectively. And even if it is eventually agreed by member states, it won’t be implemented before 2013 and so cannot help deal with the present eurozone debt crisis.
What seems to be shaping up are three big changes. First, there will be an attempt to prevent fiscal indiscipline in advance. Member states will be asked to specify medium-term budget objectives under rules that keep maximum public spending growth in line with the growth of medium-term real GDP; provide transparency in statistics (Greeks beware!); and introduce independent monitoring institutes in each country.
Second, there will be measures to force member states back on target if they stray. The EC wants to include penal action against states that exceed the debt limit of 60% of GDP as well as the budget limit of 3%. All countries that exceed the debt limit (which at present is everybody that matters) will be required to reduce their debt ratio by one-20th of the excess debt a year until the target of 60% is reached.
|
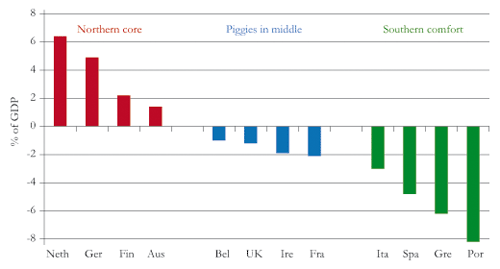
North and south |
|
Current account balances, 2010 |
 |
|
Source: OECD, Eurostat |
Infringement
If a member state failed to keep to this condition, the EC could launch an infringement procedure that would automatically lead to a fine of 0.2% of a country’s GDP. A country could only overturn the EC’s decision by getting a qualified majority of member states to back it.
And third, the EC wants to monitor the vulnerability of a member state to crisis by following the competitiveness, external balances, credit growth and productivity of each economy. A country with excessive imbalances, such as a large current account deficit that it does nothing about, could find itself facing a fine of 0.1% of GDP.
Taken at face value, this sounds pretty tough. But there are serious flaws in the changes. First, there is the continuing issue of the lack of a proper fiscal union. Federally organized countries such as the US, Canada, Germany or Australia do not have to impose fines and disciplinary action against local entity states within their structures because there are common federal taxes and expenditures with automatic balancers. Such fiscal harmonization does not apply to the EU or the eurozone. It depends on the willingness of the nations involved.
The EC wants member states to avoid serious economic imbalances. But can such countries as Greece really reduce the current account deficit with the rest of Europe when everybody else wants to do the same? And what are the correct policy options for Greece to follow in reducing its imbalances when the surplus countries do not help by reducing theirs?
No stomach
Most important, it is unclear if the EC proposals can be implemented without amending the existing Lisbon Treaty. For example, the semi-automatic fine system might require an amendment. If so, it will never happen because the UK, for example, will never agree to it and there is no stomach among many members to go back to try to change a treaty that took so much pain to get approval in the first place.
Even if agreement is reached, the new measures won’t kick in until January 2013. So they will not be in place to deal with the present fiscal and debt crisis of the eurozone. The euro’s strength is going to depend more on what happens with Federal Reserve and European Central Bank monetary policy than with the new fiscal measures.
David Roche is president of Independent Strategy Ltd, a London-based research firm. www.instrategy.com



