| Film finance was often a high-risk/high-return investment proposition with a reputation for burning investors. Now, though, hedge fund managers are finding ways to mitigate risk and penetrate opaque film industry accounting practices. |
 |
“You can run into a large, well-known studio that has a bad run of films, but generally speaking they will produce enough films to make returns” Frank Yablans, Promenade Pictures |
FRANK YABLANS IS the Warren Buffett of Hollywood. Former president of Paramount Pictures and former chairman of MGM, the 71-year-old has more than 300 films under his belt, including blockbusters such as The Godfather, Serpico, Paper Moon and Murder on the Orient Express. Back in the early 1970s when Paramount made the original version of The Longest Yard, Yablans remembers, third-party financing came from tax-shelter deals. Now Yablans is running his own film production and distribution company, Promenade Pictures. With investment advisory firm Bluebay Capital, Promenade is seeking finance from the most recent investor base to hit Tinseltown – hedge funds. This sophisticated investor base has poured an estimated $4 billion into Hollywood in the past three years in investment vehicles that, like Yablans’s operation, are attempting to create a high-returning asset class with less risk than traditional, rather speculative investment in the film industry. In the past it has been a commonplace expectation that if you put money into Hollywood, you might not get it back, let alone a return on it. With an endless supply of investors keen for a brief spell in the sexy film industry, Hollywood can perhaps be forgiven for taking advantage of the naïve and star-struck. “Everyone wants a piece of Hollywood – whether financing a film with the hope of rubbing shoulders with stars, or because of advantageous tax breaks. So Hollywood has taken their money and moved on, leaving a lot of people burnt,” says Robert de Laszlo, a director at Bluebay Capital (not to be confused with Bluebay Asset Management), who has headed the structuring of the financing package for Promenade. “Returns were almost secondary to them,” he adds. That’s not so for hedge fund managers. The possibility of making an annual 30% on investments (in the case of equity slate financing) is not the only appeal. Film financing offers uncorrelated returns. During economic downturns, people still go the cinema or rent movie DVDs.
Some losses suffered by individuals can be blamed on poor or unfortunate investments in a single film that tanked. Although some hedge funds are prepared to search for the one big hit, the preferred option – to mitigate risk and achieve high returns – is slate financing. Merrill Lynch, Credit Suisse, Deutsche Bank, Goldman Sachs and JPMorgan have all arranged co-financing deals with studios investing in slates of films, raising money from hedge funds and private equity firms among other investors. Hedge funds themselves, such as Dune Capital and Stark Investments, have also created co-financing vehicles (Dune Entertainment, and Virtual Studios).
A spread of risk by investing in a portfolio of films is common sense. According to an article produced for the UK Film Council by Paul Kent, senior vice-president, structured corporate finance, at Citibank: “Across a slate of 20 films, just two or three hits will all but ensure a positive return for investors, based on over 30 years of historical performance data from the film industry.”
Spreading the risk
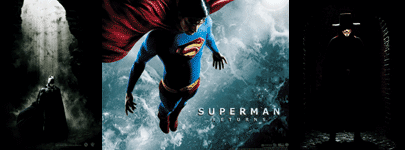
The importance of diversification is already evident. Backed by hedge funds/private equity companies including ABRY Partners, Columbia Capital, and Falcon Investment Advisers, Legendary Pictures has invested $500 million in a slate of 25 Warner Brothers movies. The first two off the slate – Batman Begins and Superman Returns – have proved successful; subsequent films – Lady in the Water and The Ant Bully – have been disappointing. Warner Brothers also struck a deal with Stark Investments’ Virtual Studios at the end of last year that has fared less well. Virtual invested $528 million in six films, the first of which were the weak V for Vendetta and the $50 million loss-making remake Poseidon.
 |
|
Slated: Legendary’s finance helped Batman Begins and Superman Returns get off the ground, while Virtual Studios might seek its own form of revenge after the weak performance of V for Vendetta |
“You can run into a large, well-known studio that has a bad run of films, but generally speaking they will produce enough good films to make returns,” says Yablans. That’s true enough, but hedge fund managers are still finding ways to deal with Hollywood studios’ strategies for cutting deals to their own advantage. Stark’s slate of films, for example, is not only on the small side; it is also high budget, and it is questionable whether there is a box office hit among its portfolio. Still to be released is The Assassination of Jesse James by the Coward Robert Ford, starring Brad Pitt; 300, with Gerard Butler; Blood Diamond, with Leonardo DiCaprio; and The Good German, with George Clooney and Cate Blanchett. Although Legendary’s tie-up with Warner Brothers might seem a better deal, sources familiar with the investment say end investors have yet to see any returns. The vehicle has also been criticized in the market for kowtowing to Warner Brothers. The studio reportedly has the final say on the 25 films on the slate and, unsurprisingly, the money-spinning Harry Potter franchise is not in the line-up.
Legendary Pictures is by no means the only co-financier to have been subject to the studios’ selective processes. Sony withheld upcoming Spiderman, James Bond film Casino Royale and May-released The Da Vinci Code from its co-financing agreement with Deutsche Bank’s Gun Hill Road. And CSFB’s Kingdom Films failed to get the Pirates of the Caribbean sequels and The Chronicles of Narnia on its equity slate deal.
“It’s in the studio’s interest to maintain flexibility on what pictures go through these deals. If the slate deal is for only eight pictures, the studio will be more selective on what they are willing to offer than if the deal covers 20 or 25 pictures,” says Bob Darwell, partner and head of the transactions entertainment practice at law firm Sheppard Mullin Richter and Hampton. “They may seek to exclude sequels to movies that pre-date the deal, or will exclude movies where they have an existing relationship with a director or producer.” An investment banker that has structured several film financing deals advises: “If you’re going to do a deal with a studio, you should make sure there is no adverse selection. You need all the movies.”
One reason why studios are seeking third-party capital has been the rise in production costs. Darwell says: “Over the years top actors have gone from making $1 million to $2 million for a picture to $20 million to $25 million.” But investors should not be focused on the big budget blockbusters to make money. Smaller-budget movies with greater audience appeal can offer good rates of return. Promenade gives investors a slate of six films produced by Yablans’s firm – all in the $5 milllion to $30 million budget range, and all family movies. Upcoming movies include an animated version of The Ten Commandments, featuring the voices of Ben Kingsley and Christian Slater; and Soul Surfer, the life story of surfer Bethany Hamilton, who lost an arm in a shark attack. A stark contrast from heavies like The Godfather and Serpico, yes, but Yablans says laughing: “I produced Willy Wonka & the Chocolate Factory, Charlotte’s Web and The Little Prince too. We had 15 to 20 films on the go at once and they were all very different.” And family films do better at the box office, he points out: “Over the last 10 years family films have had the highest rate of return and have been the least costly to make.”
Intrepid Pictures similarly has a financing vehicle investing in lower-budget films, (under $25 million) aimed at 15- to 25-year-olds. The seven-bank syndication of the deal was arranged by JPMorgan, with hedge funds and other investors providing equity or mezzanine financing. Intrepid is producing and investing in three to five films a year for five years with Universal Studios and Rogue Pictures. “For smaller-budget pictures, you can afford to have a smaller slate of films,” says Trevor Macy, co-founder of Intrepid. “For expensive films it stands to reason that you need a larger portfolio to mitigate the risk.”
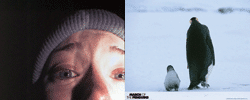 |
| Independents’ day: both The Blair Witch Project and March of the Penguins have provided high returns on low budgets |
Independent film production companies can offer investors phenomenal returns on low-budget films. For example, The Blair Witch Project and Napoleon Dynamite were produced by independent companies, and in the low-budget genre of documentaries, independents have also had success. The Oscar-winning March of the Penguins had out-grossed all five best picture nominees at the time of the 2006 Academy Awards. However, investors should exercise caution in the lower-budget area, says Yablans. Yablans’s vast experience in the business mitigates risk for investors in his production company, but he advises managers wanting to invest in films with independent makers to do their due diligence. “People may boast that they appeared in film credits, but they might not have had much to do with the film,” he says. “And, they might not have a bona fide distribution deal. Some of these guys are sadly little more than con artists. Fortunately hedge fund managers are selective and do tend to do their due diligence.” Essentially it is important to view the producer selecting the films as an asset manager, says Demetri Makoulis, who runs August Five Entertainment, an adviser to hedge funds and other financial institutions on investments in the film industry.
The quest for transparency
The due diligence that the hedge fund managers are conducting in Hollywood is helping clean up what has notoriously been a smoke-and-mirrors environment.
Bluebay Capital’s De Laszlo points to the opaque accounting structures that have plagued Hollywood. “Having come from the world of private equity and hedge funds, I believe that, as an asset class, films can offer significant returns; unfortunately the investor never gets to see them,” he says. “With this is mind we have tried to create a structure previously unseen in Hollywood that offers the investor complete transparency and a piece of ‘the holy grail’ – the distribution fee.
“There are often five or six sets of accounts. If you are the head of the studio, you’ll see that the movie made money. But investors see a different set that show the debt finance, where payments were high and investments made a loss. Investors rarely get to see the money made,” he says. De Lazlo cites one tentpole movie (so called because it’s expected to be a blockbuster and support a studio’s profits for the season). “The film cost $50 million to make, took $400 million in revenues, yet studios showed a loss of $40 to $50 million,” he says. “This sort of accounting makes Enron look like the Vatican.”
Death by a thousand cuts
Mead Welles, president and CEO of hedge fund Octagon Asset Management, invests in film financing across various parts of the risk spectrum but is wary of slate deals because of the lack of transparency. Borrowing a phrase from a prominent entertainment lawyer in LA, Welles says: “You can die of a 1,000 small cuts in a studio slate deal. You may not see the bleeding from any single cut – together they can kill you.” He is referring to the various ways in which a studio can siphon cash out of the recoupment of a slate investment.
One executive with a co-financing vehicle on Wall Street laments: “Studios are just not transparent. It’s hard to see what is caught up in video reserves and they load overheads into their budgets. I can’t say I’ve seen anyone getting ridiculous levels of clarity in their deals, although we have implemented some risk controls.”
Recognizing this risk in co-financing Hollywood, Yablans and Bluebay have structured their fund to ensure investors complete transparency with a hedge fund-like structure and, therefore, the returns they are rightly due. De Lazlo says: “We’ve brought in Goldman Sachs to handle cash management, we have Spectrum as the fund administrator, Rothstein Kass as our independent auditor who will verify the expenditures of the budget of every film and qualify all drawdowns, and then when a film is released, revenues go directly into a lockbox account managed by the custodian, State Street, to which the investor has visual access to enable them to see exactly what revenues are coming in and precisely what returns to expect.” The Promenade vehicle is also offering the investor a piece of the distribution, which is usually “last money in, first money out” and is where the real returns are made, through such earning streams as DVD rentals, and is looking to give the investors a return of about 30% a year.
The transparency offered in the Promenade vehicle, together with the closer scrutiny that hedge funds in general will be applying, could have a broader beneficial impact on Hollywood. First, studios will be forced to increase their focus on cost control. Secondly, it could clean up the financing deals in Hollywood sufficiently to encourage other investors. “Everyone has a Hollywood horror story to tell,” says Intrepid’s Macy, “but a lot of recent slate co-financing deals involve seasoned studio professionals. And hedge funds know what they are doing. The contracts are robust. It is in the interest of both parties to have healthy partners.”
Beyond the box office
Ultimately whether Hollywood can continue to rely on its new financing partner will depend on the performance of the new slate financing deals. Although it is easy to point to Virtual’s Poseidon disaster and investor complaints that money has yet to roll in from other slate deals, box office numbers are rarely good indicators of the returns that can eventually be made through the sale of DVDs, cable contracts and TV sales. “It would be great to break even at the box office, but that is becoming rare,” says August Five’s Makoulis. “DVD sales are the largest participant in the revenue stream. The distribution environment has shifted so that a film’s box office run is often a loss leader and now serves as the DVD’s marketing campaign. The studios know that they can only expect to make so much on a film at the box. This is why a lot of films that should receive more attention don’t – everyone knows that the money is in home video – so films get pulled prematurely, the window to DVD gets shortened, and the studio primes the pumps for their next weekend release.”
It is argued that film quality has suffered as studios now have a vested interest in getting films out of the theatre and onto DVD as quickly as possible. Owning the copyright to the picture is therefore essential for any investors in film. “Any good investment would include all revenue streams of a film. Often, expected performance can improve over time,” says Macy. “If the entertainment dollar shifts from theatre to DVD, and then to internet films, you will still be able to produce revenues,” adds Robert Stanley, a director in Merrill Lynch’s global structured finance & investments group, which has been involved in film financing deals with Cold Spring/Dreamworks, First Look, Regent, Marvel and Melrose Investors/Paramount.
Laughing all the way to the bank
There is a possibility that Hollywood might turn its back on hedge fund investors if better sources of funding came up. But it seems to be a remote one. Inflows from wealthy foreign investors are drying up as changes in tax laws make investing in US films less attractive. Moreover, marketing and advertising costs are increasing faster than production costs. In equity slate financing deals, hedge funds offer studios the opportunity to spend less on producing the film but still to benefit from the distribution fees, lowering their own risk.
“Studios are laughing all the way to the bank,” says Gordon Clark of The Movie Portfolio Fund. “This new type of third-party capital is exactly what they’ve been looking for. They get to lay off a substantial part of the risk, keep 100% of creative control and handle their own distribution. When they distribute the movie they typically charge a 10% to 15% distribution fee before splitting the profits.” Clark set up The Movie Portfolio Fund in 2002 to offer institutions and high-net-worth investors the chance to invest in a slate of films with a heavy-hitting Hollywood producer and distributor. He adds: “In pure accounting terms they are lowering their need for internal capital, and therefore raising their own return on capital. Plus studios like a lot of product to distribute. With the extra funding they can produce more films to distribute.”
Has there been any scepticism about having hedge funds as financiers, as has happened in some other sectors? “Are you kidding?” says Yablans. “Any money coming into Hollywood is welcomed with open arms and a rubbing together of hands.”


