Société Générale
|
Also shortlisted in this category: |
Many dealing houses aspire to be leading players in equity derivatives but only one institution has consistently been at the forefront of innovation in an increasingly competitive area, and that institution is Société Générale, the recipient of this year’s inaugural equity derivatives award.SG has always had a stellar reputation for structuring complex equity-linked structured products and solutions but its equity derivatives business has matured to the point where the bank is able to fully deploy its engineering expertise across all asset classes and customer bases, while retaining a solid footing in its retail equity derivatives trading roots.
“In terms of sheer size, today we are the biggest equity derivatives player in the world. In our global equities and derivatives solutions business we have a total of 3,300 people, of whom 1,400 are front-office traders and financial engineers,” says David Escoffier, who runs SG’s global equities and derivatives solutions business from London. This assertion is backed by figures from analysts at JPMorgan, who put SG’s revenues from equity derivatives well ahead of its nearest competitor. They estimate SG’s annual equity derivatives revenues for 2007 will be close to €3.5 billion. Its closest competitor, BNP Paribas, comes in at around €1.9 billion, with Deutsche Bank in third place on an estimate of €1.3 billion.
 |
|
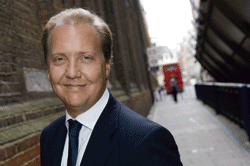
David Escoffier: SG is the biggest equity derivatives player in the world |
Several factors have come together to give SG a particularly strong equity derivatives business. It started trading equity derivatives 20 years ago but it was not until 2002 that it decided to break into the high-volume, plain-vanilla flow business. Until then the flow business had been dominated by the big US trading institutions, which had established themselves in the US listed options market. The European houses, and particularly the French banks, had tended to be strong when it came to complex products but slow on the flow side. “We invested in the flow side in 2002, developing a flow business in Europe and expanding it subsequently in the US and Asia,” says Dan Fields, the bank’s global head of flow trading.
The establishment of large amounts of flow business is paying off on the sophisticated structuring side, as the increased size of SG’s trading book means it can handle more risk. The bank also set about establishing an alternative risk transfer market, which not only enabled it to expand its trading capacity but also to offer new types of exposures to clients. The result was that in 2003 the bank became the first institution to trade a correlation swap with one of its hedge fund clients. “Many in the hedge fund community know us as the most innovative structured products house because we’re able to transfer risk from our complex exotic book to them as clients,” says Fields.
Any bank with a large equity derivatives and structuring business is invariably chronically short correlation. SG, however, was the first to take that risk, single it out and package it up in a correlation swap and then sell it to its established hedge fund clients. The funds are buying in order to speculate on correlation, says Fields, although some will have a natural opposite position on correlation, which can then be hedged via the swap. The standard deal that started to trade in 2003 involved selling correlation on a bespoke basket of 25 to 30 stocks, with a maturity of three to five years. The market has developed rapidly, however, such that SG can even offer correlation on a cross-asset basis, such as on foreign exchange against an equity underlying, or on commodity exposure against equities.
Giving clients exposure to correlation and other esoteric parameters, such as skew or “smile risk”, is one of the ways SG is innovating to give access to what Escoffier describes as hidden or implied assets. Much of the bank’s efforts today, such as its Generis Funds range, for example, involve giving clients exposure to what could be called new sources of alpha. The idea is that investing in traditional asset classes exposes investors not just to directional risks but also to second-degree risks such as volatility, correlation, dividend levels, and so on. SG is selling products that seek to isolate and profit from these risks.
The Generis Lyxor G-Volt product, for example, gives exposure to a stock volatility arbitrage strategy, and is designed to take advantage of inefficiencies in stock volatility pricing. Then there is G-Square, which is described as an “index volatility surface arbitrage strategy”. This is designed to take advantage of inefficiencies in implied index volatility prices. G-Sphere, meanwhile, is designed to take advantage of inefficiencies in spot volatility pricing via long/short positions.
The Generis funds are all single strategy, offering exposure to dispersion, index volatility and volatility smile. SG, via its Lyxor Asset Management subsidiary, also has a multi-strategy offering, Quantic Funds. These have varying performance objectives and are managed by an SG/Lyxor management committee. The overall aim is to seek out arbitrage opportunities using implied assets. In a market that can seem bereft of new ideas, the sourcing and establishment of new trading parameters is a big part of SG’s success story.




