
Shahril Ridza Ridzuan, CEO Employees Provident Fund
The Employees Provident Fund (EPF) matters.
It is not just that, with RM768.51 billion ($196.6 billion) under management as at December 31, 2017, it is one of the biggest pension funds in the region.
Nor that, with assets equivalent to more than half of the Malaysia Stock Exchange’s market capitalization, it is uncommonly powerful in its own country. Nor even that it is a vital sign of well-run institutional stability in a country where the political environment seems more of a circus by the day.
No, the broader significance of the EPF is what it tells us about the potential for Islamic finance in national pension and sovereign funds.
Few sovereign or pension vehicles in the Islamic world, from the UAE’s and Qatar’s sovereign wealth funds to Saudi Arabia’s central bank, are actually invested along Shariah principles, despite those countries having far stricter interpretations of Islam than Malaysia does. But the EPF, which now runs a Shariah-only stream of its main fund and has boosted Shariah compliance across all its assets, tells us a lot about the practicality of Shariah investment on this scale and about the crossover between Islamic finance and the environmental, social and corporate governance (ESG) world.
|
IN ADDITION |
|
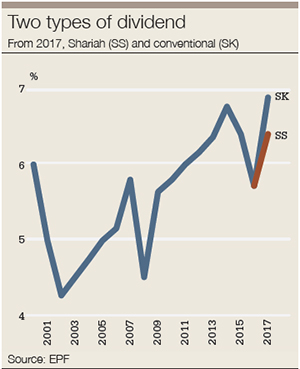
It is being closely watched by peers across the Islamic and conventional investment world – partly for its investment and partly for the enormous impact it has had on the development of Islamic asset management across the whole country. In February, the EPF declared its dividends for the year, for the first time in two separate streams: a 100% Islamic scheme and another that is conventional but derives 38% from Shariah-compliant sources.
“It’s been a fairly long journey,” Datuk Shahril Ridza Ridzuan, chief executive of the Employees Provident Fund, tells Euromoney in the institution’s Kuala Lumpur headquarters not far from Masjid Negara, the national mosque.
 |
| Datuk Shahril Ridza Ridzuan, chief executive of the Employees Provident Fund |
“I joined the EPF in 2009 as CIO. Even then it was quite obvious there was strong demand from the membership for a fully Shariah-compliant fund.”
What is instructive is the approach the EPF took in getting there. Its starting point was not religious compliance but ethical investment. In 2010, the fund developed clear guidelines on its ethical position – which industries it would continue to invest in and which it would disengage from and how it would apply ESG principles – and then considered Shariah as a development of that process, rather than the other way around.
Groundwork on the separate Shariah scheme began in 2013, only after the ESG position was fully articulated.
“You can understand the origins: faith-based investing that needed to comply with the understanding of Islam. But today we look at it in the context of broader finance and economics. It’s really just a subset of ethical investing with an added filter on leverage, sustainability and structure” – Shahril Ridza Ridzuan, Employees Provident Fund
“There has been an over-emphasis on the religious aspect of Shariah investing,” Shahril says. “More emphasis should be put on sustainable investing, de-emphasizing the religious aspect.
“You can understand the origins: faith-based investing that needed to comply with the understanding of Islam. But today we look at it in the context of broader finance and economics. It’s really just a subset of ethical investing with an added filter on leverage, sustainability and structure.
“There’s more scope, I think, for Shariah investing to really kick off in the mainstream.”
By December 31, about 10% of the fund’s total assets had switched to the Shariah-only option: some RM67.76 billion. The proportion is likely to change as familiarity grows and investors look at the returns from it. But even getting to this point would have been extremely difficult 10 years ago.
“From 2013, we started looking at the theoretical framework of how we could do it and, from an investment perspective, whether we could achieve the same risk reward matrix and risk profile” as conventional, Shahril says.
“What’s changed substantially from the early 2000s is the fact that there are now a lot more Shariah-compliant assets in the market – not just the amount of assets but across multiple asset classes.”
Up until about 2009, any discussion of Shariah assets tended to be synonymous with the sukuk market. “But now other avenues have opened up for us to have Shariah-compliant assets in the real space: property, infrastructure, private equity,” Shahril says.
“We wanted to maintain that if we did this, both sides would have reasonably similar risk characteristics and similar diversification opportunities.”
Launching the new stream also required amending the act of parliament that governs the fund, its own investment framework and even the way it collected money – Islamic finance does not allow for investors being penalized for falling short in their regular contributions, for example, so a new structure had to be devised for those default situations.
It also required managing expectations because, inevitably, conventional and Shariah portfolios are going to deliver different outcomes, determined chiefly by how conventional banks have done in any given year.
“We were very clear to the membership that the outcomes would be different,” Shahril says. “What was most important was to explain if you have two streams, you’re going to have two dividends. It’s not that one is better than the other, but it will reflect the underlying performance of each stream.”
 |
Running up to the dividend announcement: “We were keeping a close eye on whether people would find that an issue,” but as yet it has not proven to be the case.
In practice, the dividend was 6.9% for the conventional portfolio and 6.4% for the Shariah, although volatility is likely to be lower on the latter. “We try to remind people that saving for retirement is a 20-year process, not a one-year process. Keep an eye on that long-term horizon.”
The EPF is not the only institution in Malaysia thinking of itself in ESG terms. In February, KWAP, the second-biggest pension fund in the country, became the first in Malaysia and only the second in Asean to sign up to the United Nations-supported Principles for Responsible Investment.
“From our perspective, the principles for responsible investment are very compatible with Shariah compliant funds” – Fiona Reynolds, UNPRI
These six ESG principles have been signed up to by about 1,800 big funds around the world. KWAP also has a long-standing background in Shariah and its chief executive, Dato’ Wan Kamaruzaman Bin Wan Ahmad, has a similar view of the overlap between the Islamic and ESG fields.
“The Shariah background has some similar traits and methodology as ESG investment in good companies with good governance,” he says, speaking to Euromoney at the World Capital Markets Symposium in Kuala Lumpur. “That is why it is easy for us to shift from Shariah to ESG, because that’s the basis of where we started from.”
Fiona Reynolds, chief executive for the Principles for Responsible Investment, tells Euromoney: “From our perspective, the principles for responsible investment are very compatible with Shariah compliant funds.”
 |
| Fiona Reynolds, UNPRI |
But here’s the strange thing: Reynolds says that out of its whole membership, fewer than 20 funds from Organization of Islamic Cooperation countries are signatories: “It’s an area where we think there is great alignment and we would really like to see more Islamic finance organizations, banks and pension funds, work with the PRI.”
So why aren’t there more? Why, for that matter, is the EPF not a signatory?
“We’ve already adopted a lot of principles,” says Shahril. “We are one of the leaders here in terms of ESG. We have not formally signed off on UN PRI, not because we don’t believe in it, but because from our point of view we are already adopting a lot of their principles. So we’ve never really felt the need to have to sign up to something just to demonstrate we are doing it.”
There are, however, areas where the two do not exactly align; in the southeast Asian that is most clearly visible in palm oil investment.
“There is a bigger, broader debate in terms of what does ESG mean, according to where the different funds are coming from,” says Shahril. “As a Malaysian retirement fund coming out of a developing country, which still has a big emphasis on the agricultural sector and palm oil as a means of development and growth for the nation, sometimes that puts us at odds with our counterparts in Europe.
“Some funds in Europe have taken the view that all palm oil is bad and they are never going to invest in it. We prefer to take a different view. It is better for us to engage with these people: at the end of the day, their workers are our members as well, and as employers, they contribute to the fund.”
Shahril says the fund meets palm oil producers and tries to get them to comply with environmental standards and practice sustainability. The EPF has a powerful voice.
“I’m happy to note that a lot of the major palm oil producers are compliant, or trying their best to become fully compliant; where there’s an issue of non-compliance, we highlight it and ask the steps they are taking to reach full compliance,” says Shahril. “The problem is a bit further down the value chain: the smaller palm oil producers, smallholders, the families who own maybe 10 or 20 hectares and are working on the land.”
The reason Islamic finance has been a success in Malaysia is first and foremost because all the country’s key institutions have shared a vision for it for 20 years.
Bank Negara Malaysia, the Securities Commission and (by and large) the government have been consistent in their ambitions, with help from other key institutions such as the Bursa Malaysia stock exchange, the Khazanah sovereign wealth vehicle and the EPF.
The EPF’s chief contribution to the whole effort has been money. When the Malaysia International Islamic Financial Centre (MIFC) was launched in 2006, its ambition was to turn the country into a global hub for Islamic asset management. In order to attract international fund managers to set up, the EPF seeded several of them with mandates.
Certainly, it has been successful in attracting some big names – including Aberdeen, Principal and Nomura – even if there has always been some doubt whether it has attracted international capital to come to Malaysia or created an avenue for it to leave.
“We’ve had a fair amount of success,” says Shahril of the MIFC. “We tend to view the MIFC programme in conjunction with our broader interests.
“We’ve made it very clear to the fund managers who want to work with us: we are always willing to give them a chance, but we are also hoping that they will then reciprocate and put resources in place in Malaysia to service not only us but others.”
Shahril is clear, however, that foreign managers will not get funds automatically just by turning up.
“Just because they’ve been given a licence doesn’t automatically mean they are going to get funds,” he says. “In the early days, there was some misconception. People thought that as soon as they got a licence, we were going to throw money at them.”
Asked how many of the foreign fund managers and joint ventures in MIFC the fund deploys money to, he says: “I would imagine slightly less than half of the people who got licences.”
Another key shift of recent years at the EPF has been a move from domestic towards international assets.
When Shahril joined, about 5% of EPF’s assets were invested overseas; now it is about 28%, approaching what he describes as an optimal level of around 32%. It has taken eight years to get to this point, “with diversification not just of geography but of risk-return profiles,” and it is a challenge to elevate the international proportion of the fund when its asset base grows at about 11% a year anyway.
So far, returns have been good since the international shift. The fund’s benchmark is CPI plus 2%; it has been beating inflation by more than 3%.
Although this looks like good news for international fund managers, the EPF actually does most of its international investment in-house. Across the whole fund, only 14.5% is managed by external fund managers.
Going global presents some challenges for Shariah compliance, not so much for debt and equity but for real estate and other physical assets. The issue is the financing attached to real estate.
“There could be a perfectly good asset, which by itself is Shariah compliant, leased out to a telecoms or tech firm. But in Europe for instance, it is pretty hard to get euro-denominated Shariah-compliant funding for an asset like that because they don’t have the deposit base to support it.”
One challenge the EPF faces is its sheer scale relative to the market in which it sits. The EPF is easily the single largest trader on the market, which is one of the reasons it has set about diversifying globally.
“That provides an avenue for us to make sure we can obtain the desired risk-return diversification and optimal outcomes on our returns without overbalancing the Malaysian economy,” he says.
One area where this causes particular challenges is the banking sector. Malaysian banking is overcrowded. So it is no surprise that mergers are often proposed – and derailed with uncommon frequency. But there is nothing the EPF can do to help a merger over the line because it will always be a shareholder not just in one bank but both. In the case of the recent AmBank/RHB proposed merger, it was the biggest shareholder in both banks.
“It places us in a very difficult position,” says Shahril. “In Malaysia, we are a substantial shareholder of every single bank. When it comes to any discussions between them, we have to advise the banks that we need to be out of the discussion. In order to preserve our stance, we do not actively take part in any discussions.”
It would appear the issues of the fund’s scale are going to get more pronounced before they get better.
“ There will come a point in time, in simple mathematics, where it becomes a problem,” he says. The fund grows at 11% a year, the economy at 4.5% to 5%. “That’s already a mismatch. We have to be careful we are not overcrowding the market here.”
EPF’s Shahril slams Sarawak report allegationsThe EPF has, like Bank Negara, generally been seen as one of Malaysia’s best institutions, rising above the considerable political noise of the country. But in febrile, post-1MDB Malaysia, the whiff of scandal is never far away. In February, the EPF was accused of involvement in a scandal that recalled 1MDB – although the circumstances are very different and the EPF claims the whole thing is a long-known fraud. That month the Sarawak Report released a trove of apparently incriminating documents that appeared to have the EPF consorting with a grim cast of characters. The documents suggested that Ja’afar bin Rihan, a senior executive at the EPF, had participated in a transaction allowing two companies, Ladylaw Securites and Limage Holdings, to use RM10.64 billion ($2.72 billion) of bonds owned by the EPF as collateral to raise money, supposedly for a hospital investment. The Sarawak Report alleges the whole purpose of the exercise was to create an election slush fund for prime minister Najib Razak. An election must be held by August 24. Both Ladylaw Securities and Limage Holdings have been run by convicted criminals. Limage is owned by a US-based Hungarian called Gyorgy Matrai, who was sentenced to two years’ imprisonment for fraud; Ladylaw’s founder George Miller served time in the Philippines. The EPF claims all the documents are forgeries. Its case is very much strengthened by the fact that it says it reported the documents to the police well before Sarawak Report ever got hold of them. It says that a fake letter of indemnity alleging an agreement between the EPF and Limage was brought to its attention in October 2015 and was passed on to the police within days. It says that other letters were passed to the police with the suspicion of fraud in both 2016 and 2017. “I think it is a bit disappointing because we’ve quite clearly said many times that the documents that they are relying on are fake,” says Datuk Shahril Ridza Ridzuan, chief executive of the Employees Provident Fund. “They have never come from the EPF. “More importantly, the transactions they allege to have done are actually impossible to do. Bonds in Malaysia are scripless and can’t simply be managed and transferred in the way they seem to be alleging.” Two banks alleged to have been connected, RHB and HSBC, have both denied any involvement with any of the named companies at any time. It must be said that if it is a fraud, it is an extremely elaborate one. One of the documents using Ja’afar bin Rihan’s name appears to have been notarized by notary public Wong Kien Cheong, apparently on sight of bin Rihan’s ID card. The EPF has not been helped by denying having had any interaction with Ladylaw, when Ladylaw’s owner, Nic Manikis, has told Australian newspapers that he met bin Rihan personally (although it appears very likely this was about a different deal entirely, which never went forward. It is also possible that he may have met only someone claiming to be bin Rihan). Shahril points out that the documents use a number of email addresses for bin Rihan, several of them apparently invented googlemail addresses. There is one functioning EPF email address in the documents, but Shahril tells Euromoney: “The only email address which purports to be his address in the EPF is actually the email address of an office boy in Sarawak, who happens to share the same name.” He also pours scorn on the sophistication of the scam. “In this day and age, my 10-year-old daughter could fake it,” he says of the key document. “[One could] go to the EPF web site, do a GIF of the logo and the address and create your own letterhead.” Among Malaysia’s institutions, the opinion seems to be that the timing of the revelations is politically motivated and that Sarawak Report is backing one side. Shahril says: “Quite clearly they have their own interests of viewpoint they want to pursue,” and “they seem to be like a dog that’s got a bone it can’t let go of.” But it would be doing the Sarawak Report a disservice to suggest it were a fake news organization. Without it, we might never have heard of the 1MDB scandal. The vast majority of the key documents that led to that scandal’s exposure and ultimately to the US Department of Justice investigation, first appeared on the Sarawak Report site, which, despite its name, is based in London and run by investigative journalist Clare Rewcastle Brown. Nevertheless, the fact that EPF can prove it reported the documents to the police years before the public saw them supports its position and suggests we are not looking at another 1MDB. Instead the bigger question is what did the police do about the EPF’s complaints? There was an attempt to use RM10 billion of public money without the permission of the fund’s investment board. Surely there must have been an investigation? “We’re not sure. We left it with the police for them to investigate,” says Shahril. “The problem basically is that in the absence of any real leads, you don’t know who’s doing it. I can only imagine the difficulty the police would face in trying to work out who’s responsible for the fake documents.” Questioning the notary public who apparently authorized bin Rahim’s signature on documents would seem a logical place to start. Euromoney contacted the Royal Malaysia Police to ask about the progress of its investigation but received no reply. |



