|
Also shortlisted in this category: |
Standard Chartered
Almost every leading bank in the world claims to have a big presence in the emerging markets. In truth few actually do. But one bank whose emerging markets credentials cannot be questioned is Standard Chartered. The firm is headquartered in the UK but its heart lies very much in the developing world, specifically Africa, Asia and the Middle East.Over the past year Standard Chartered has stood out for its ability to generate tremendous momentum in its emerging markets business without compromising its financial base. In 2006, for example, the bank made acquisitions in Taiwan and Pakistan, rapidly expanded in China and India, made big strides in corporate finance and rolled out a new private bank.
At the same time, the bank delivered income growth of 26% year on year and profit before tax jumped by 19% to $3.18 billion. Normalized earnings per share increased at a compound annual growth rate of 21%. This was the fifth year in a row that Standard Chartered had delivered double-digit profit and EPS growth.
|
Peter Sands, Standard Chartered: success comes from our unique character |
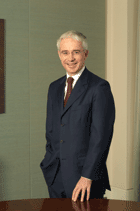 |
For Peter Sands, chief executive of Standard Chartered, the bank’s success lies in what he claims is its unique character. “No other bank is as focused on Asia, Africa and the Middle East in the way that we are. We grew up in India and China – these are our home markets.”
Undoubtedly the two big defining achievements of last year were the acquisitions of Union Bank in Pakistan for $487 million and of Hsinchu International Bank in Taiwan for $1.2 billion.
Both deals were groundbreaking, as Sands explains. “No foreign bank had made a controlling acquisition in either country before,” he says. Standard Chartered bought a 95.4% stake in Union Bank and a more than 51% share of Hsinchu. In Pakistan, the firm is now the biggest foreign bank, with 115 branches in 22 cities. In Taiwan, it has gone from having three branches to 86 in a single move.
Both acquisitions demonstrate Standard Chartered’s commitment to less than fashionable countries. They illustrate too the bank’s ability to spot opportunities even when local market conditions are not necessarily propitious. In Taiwan, for example, the bank took control of Hsinchu at the end of 2006 at a time when the country was still reeling from a consumer credit card crisis. “Sometimes the best time to make an acquisition,” says Sands, “is when things are not as rosy, as people are willing to sell and you are more likely to get value. But you need to have knowledge and confidence about how the market will develop.”
Where will the bank buy next? Although it is under no pressure to make further acquisitions and the emphasis generally is on accelerating organic growth, Sands confirms that it is considering another investment in China, where it already has a 19.99% stake in China Bohai Bank. Standard Chartered is also in talks to buy a 49% stake in Indian brokerage UTI Securities for about $17 million. This stake could eventually increase to 70%.
The bank is already delivering strong results in these two key markets. In China, for example, Standard Chartered more than doubled income last year to $300 million, tripled profits and expanded its network to 22 locations in 14 cities. It launched renminbi consumer banking following the incorporation of the business in April. In India, the bank made profits of $400 million, up 69% on 2005.
Standard Chartered is not just expanding geographically. It is building its products too. Last year it launched more than 230 wealth management products across its network, a private bank in Korea, a range of credit cards and consumer finance in Thailand, Korea and India.
Arguably, though, it’s the wholesale banking arm that is creating the greatest excitement. The bank’s key strategy is to intermediate investment and trade flows between the three emerging regions in which it focuses. Already it is becoming a growing force in the Asian M&A investment banking scene.
Last year, for example, Standard Chartered advised India’s Tata Steel on its takeover of Thailand’s Millennium Steel. It also played a leading role in the financing and, to a lesser extent, in the advising of the Indian company’s $11.3 billion acquisition of Anglo-Dutch steelmaker Corus.
Elsewhere, the bank is planning to build in commodity derivatives, principal finance and credit derivatives. Sands says that Standard Chartered is poised to invest in equity derivatives in Asia, too, although it has no plans to enter the cash equities business.
These initiatives should help Standard Chartered become a more visible force in investment banking and a firm to be taken more seriously by its rivals – something that is not always apparent. “I think we are underestimated in investment banking and corporate finance,” says Sands. “If you look at the league table rankings, in our markets we’re doing very well.”




